
Consumer Industry Update Q4 2025
A Record Year, Built in the Second Half
Global M&A closed 2025 at nearly $5 trillion, the strongest year for dealmaking on record, and the fourth quarter set a new North American high. Our Q4 2025 review of a market that paused in the spring, then sprinted through year-end.

global M&A value in 2025 across roughly 50,800 deals, up 37% year-over-year, the strongest year for dealmaking on record.
North American deal value in Q4, up 2.4% from Q3, a new quarterly high.
quarter-over-quarter jump in consumer deal value in Q4, on 3.7% fewer deals: fewer, larger transactions.
Food & Beverage transactions closed in Q4, up 17.0% versus Q4 2024 and the busiest quarter of the year.
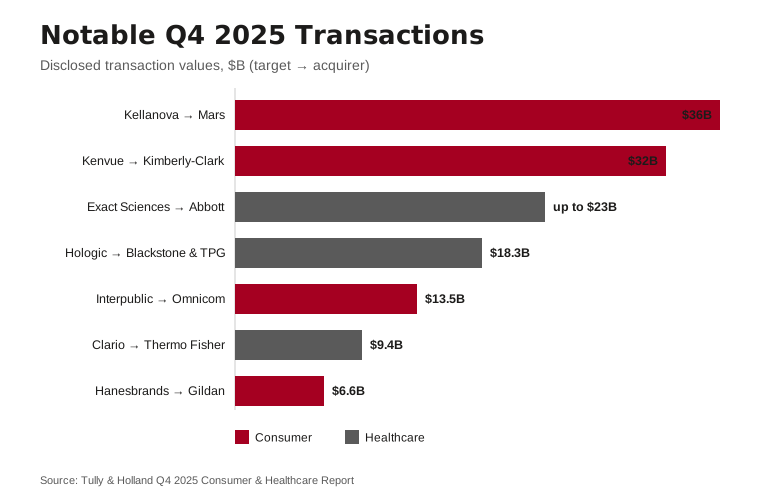
Mars closed its Kellanova acquisition and Kimberly-Clark announced its Kenvue deal, two megadeals that reshaped the consumer landscape.
healthcare services deals in 2025, up 9.6% year-over-year, with diagnostics drawing the quarter's biggest checks.
General Market Commentary
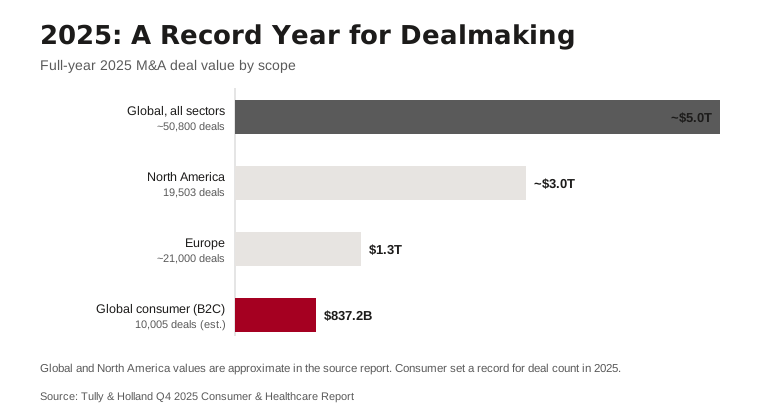
Global M&A activity closed 2025 at record levels, capping the strongest year for dealmaking on record. Total transaction value reached nearly $5 trillion across approximately 50,800 deals, representing a 37% increase in value and a 12% increase in volume YoY. After a brief pause in activity during the first half of the year amid macro uncertainty and tariff volatility, dealmaking accelerated sharply in the second half, with both Q3 and Q4 setting new records for transaction value. This resurgence was driven by renewed investor confidence, easing financing conditions following interest rate cuts, and a pronounced return of megadeals as buyers pursued scale, strategic realignment, and long-term growth opportunities.
Financial Sponsors
PE Details & Outlook
U.S. Private equity activity in 2025 totaled 9,019 completed transactions with an aggregate deal value of approximately $1.2 trillion, marking one of the strongest years on record for the asset class. Activity accelerated meaningfully in the second half following a slower Q2, with Q4 alone accounting for roughly $292 billion in deal value, as financing conditions stabilized and sponsors grew more comfortable underwriting large transactions.
Take-private activity was a notable contributor to year-end deal value, particularly in technology and B2B. Sponsors completed 80 take-private transactions in 2025, which is down 18.4% YoY, but aggregate take-private value climbed to $254.6 billion, up 67.2% YoY, making 2025 the second-highest year on record for take-private deal volume.
Exit activity improved over the course of the year, supporting capital recycling into year-end. PE exits totaled 1,619 transactions generating $728.1 billion in value, with Q4 exit value of approximately $229 billion, driven primarily by sponsor-to-sponsor and corporate buyer activity.
Looking ahead, the key variable is not capital availability but the pace of execution. With financing markets more open, sponsors appear positioned to remain active, though underwriting discipline and operating fundamentals will continue to shape deal flow.
VC Details & Outlook
Venture Capital activity maintained a strong dollar pace in Q4 2025. Total deal value reached approximately $91.6 billion during the quarter across 4,482 transactions. This represents one of the highest quarterly value totals since 2021, despite deal count remaining well below prior cycle peaks.
Momentum during the year was driven primarily by later-stage activity. Late-stage VC and venture-growth deal value increased 45.4% and 131.1% YoY, respectively. Rather than reflecting a broad expansion across the market, capital deployment remained concentrated in a relatively small number of outsized transactions, as investors prioritized scale and capital-intensive opportunities amid ongoing liquidity constraints.
Corporate participation played an increasingly important role in supporting deal value. VC deals with corporate venture capital (CVC) participation totaled $196.7 billion in 2025, the highest level of the past decade. This increase is largely attributable to artificial intelligence-focused transactions, where CVCs were very active in large funding rounds alongside traditional VC firms.
Key Regions
North America
In North America, M&A closed 2025 with record momentum. Including estimates for late reporting and nondisclosed deals, there were 19,503 announced or completed transactions in 2025, totaling approximately $3 trillion. Deal value accelerated in the back half of the year, with Q4 estimated deal value reaching $878.3 billion, up 2.4% QoQ, marking a new quarterly high.
Momentum was supported by improving financial conditions and a renewed shift toward megadeals. In H2, there were 194 megadeals contributing $1.2 trillion in M&A value. Sector activity also broadened into year-end, with healthcare and B2B posting the greatest QoQ value gains, up 102.2% and 58.1% respectively.
Europe
European M&A had a standout 2025, with nearly 21,000 announced or completed transactions representing $1.3 trillion in deal value, just shy of the 2021 peak. Activity accelerated over the course of the year, with H2 deal value up 31.4% versus H1 as overall macro conditions stabilized.
In Q4, deal value increases QoQ in both IT and financial services, rising 63.3% and 1.1%, respectively. Financial services delivered a record year for deal value, highlighted by the $7.4 billion take-private of Janus Henderson announced late in Q4, while IT momentum picked up into year-end, including the $6.8 billion Qualtrics agreement to acquire Press Ganey Forsta.
Asia Pacific
Asia-Pacific M&A activity remained subdued in 2025, with dealmaking constrained by ongoing macroeconomic uncertainty and heightened geopolitical complexity. Activity continued to lag North America and Europe, with weak conditions in China weighing on the overall regional momentum. Japan seems to be in a good spot with their new leadership, with early signs of economic growth heading into 2026 by rising wages, corporate investment, and a more supportive monetary policy.
Tully & Holland Focus: Consumer
Consumer M&A activity closed 2025 at historically elevated levels, with an estimated 10,005 announced or completed B2C deals and aggregate total deal value of $837.2 billion, marking the highest deal count on record for the sector. While deal value finished slightly below peak levels, activity built steadily throughout the year. In Q4 2025, consumer deal value increased 23.2% QoQ, despite a 3.7% decline in deal count. This reflects continued execution in larger transactions amid inflation, tariff cost pressures, and slowing economic growth. Against these conditions, acquirers remained focused on portfolio realignment and disciplined investment categories aligned with shifting consumer preferences.
Food & Beverage
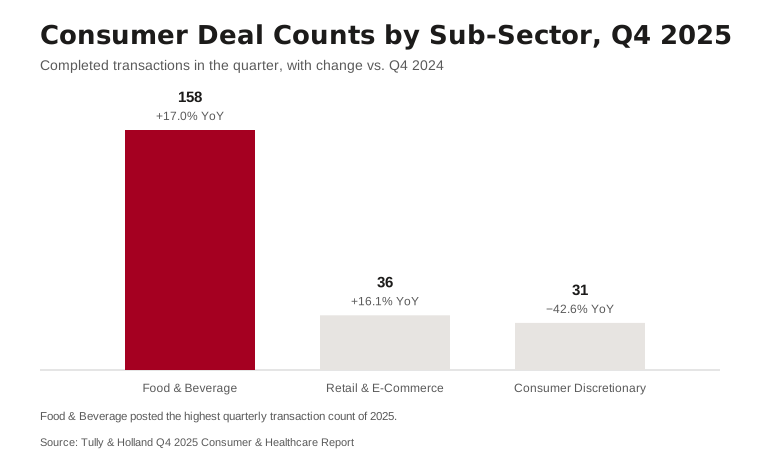
Food & Beverage M&A activity accelerated into year-end, with 158 transactions closed in Q4 2025, representing a 17.0% increase versus Q4 2024 and the highest quarterly transaction count of 2025. The second half of 2025 meaningfully outpaced the first, reinforcing improving momentum across the sector.
Several large transactions closed during the quarter. Mars completed its $36 billion acquisition of Kellanova in December, creating a combined global snacking platform. Investindustrial agreed to acquire TreeHouse Foods for $2.9 billion, adding a scaled private-label manufacturer to its portfolio. In beverages, Anheuser-Busch acquired a majority stake in BeatBox Beverages for approximately $490 million, expanding its footprint in ready-to-drink products.
Buyers continue to target snacking platforms, private-label manufacturing, functional brands (protein, energy in particular), and convenience-oriented products in Food & Beverage. Beverage activity remains concentrated in alternative and flavored alcohol formats. Across CPG, adoption of AI, discipline in go-to-market execution, and tighter portfolio construction and maintenance, will be key added-value differentiators for acquirers in 2026.
Retail & E-Commerce
Retail & E-Commerce M&A activity remained high through 2025 with dealmaking stabilizing into year-end after a softer first half. In Q4 2025, 36 transactions were completed, representing a 16.1% increases year YoY, and marking one of the most active quarters of the year despite continued pressure on discretionary consumer spending. Quarterly activity in 2025 ranged from 28 to 39 transactions, reflecting a steady but cautious deal environment.
On December 1, 2025, Gildan Activewear agreed to acquire Hanesbrands for approximately $6.6 billion. Hanesbrands manufactures basic and athletic apparel across brands including Hanes, Playtex, Maidenform, Bali, and Bonds, and sells through wholesale, department store, and direct-to-consumer channels. The transaction combines two vertically integrated apparel platforms with manufacturing and distribution operations across North America and Asia.
Earlier in the quarter, Capitol Hill Group and Worldwide Golf Shops acquired Big 5 Sporting Goods for approximately $341 million. Big 5 operates a network of sporting goods stores across the Western United States and maintains an e-commerce platform supported by a centralized distribution center in California.
Retail deal activity during Q4 also included additional mid-market transactions across specialty retail categories. These transactions contributed to steady quarterly deal flow, though large-scale transactions remained limited relative to prior cycles.
Looking ahead, retail deal activity is expected to remain selective. Premium brands and value-oriented platforms continue to come up more often in discussions, while mid-priced concepts face a higher bar. Buyers also continue to focus on clear brand positioning and defined operating models rather than broad assortment strategies. There is also more focus on data quality, go-to-market execution, and demand visibility as opportunities are evaluated.
Consumer Discretionary
Consumer Discretionary M&A activity softened into year-end. 31 transactions were completed in Q4 2025, down 42.6% YoY, making it the least active quarter of the year. Deal volume declined steadily over the course of 2025 following higher levels earlier in the cycle.
One of the largest transactions announced during the quarter was HNI’s acquisition of Steelcase, valued at approximately $2.8 billion. Steelcase designs and manufactures office and workplace furniture and serves corporate, education, and healthcare customers globally. The transaction represents a significant consolidation within the office furniture segment.
In October, Platinum Equity acquired PlayPower (Recreational Goods) for approximately $550 million. PlayPower manufactures commercial and recreational products, including playground and leisure equipment, and serves institutional and commercial end markets. The transaction added a scaled recreational platform to Platinum Equity’s consumer portfolio.
Additional activity during the quarter included Man Wah Holdings’ acquisition of Southern Motion for approximately $32 million, expanding Man Wah’s footprint in upholstered motion furniture manufacturing in the United States. Other completed transactions included Magnussen Home’s acquisition of Pulaski Furniture and SiteOne Landscape Supply’s acquisition of Red’s Home & Garden, reflecting continued deal flow across fragmented home and specialty consumer categories.
Consumer Discretionary deal activity is expected to remain centered on individual platform transactions rather than a broad recovery in volume, with larger, established assets accounting for most of the announced activity.
Tully & Holland Focus: Healthcare
Healthcare services M&A activity closed 2025 with an estimated 747 announced or completed deals, reflecting a 9.6% increase YoY in deal activity, though deal value finished 1.6% lower YoY despite several megadeals throughout the year. Q4 activity came in approximately 15% below the prior year’s level, driven primarily by weakness in physician practice management, where heightened regulatory burdens around PE ownership extended deal-process timelines across key states, like California. PE exit activity showed resilience, with exit count increasing 17.1% YoY and exit value rising 14.1%, highlighted by Cencora’s $7.4 billion acquisition of OneOncology and Ascension’s $3.9 billion acquisition of AMSURG.
Consumer Health & Diagnostics
Consumer Health & Diagnostics deal activity remained active into year-end, with acquirers continuing to prioritize scaled diagnostics, clinical data assets, and consumer-facing testing platforms. Among the largest announced transactions in Q4 2025, Abbott agreed to acquire Exact Sciences for up to approximately $23 billion, expanding its position in cancer screening and molecular diagnostics, while Thermo Fisher announced its acquisition of Clario for up to approximately $9.4 billion to deepen its capabilities in clinical trial data and digital health enablement. Industry fundamentals also remained supportive, with IBISWorld noting a rebound in Diagnostic & Medical Laboratories revenue and margin in 2025, alongside continued investment in automation, digital pathology, and strategic network expansion by major players such as Quest Diagnostics. Looking ahead, buyers are expected to remain focused on assets that combine recurring testing revenue with data-rich workflows, automation, and patient engagement, particularly as consumer diagnostics continue to push medtech further toward healthcare consumerization.
Wellness & Lifestyle
Wellness & Lifestyle deal activity remained selective in Q4 2025, but capital continued to favor platforms with clear consumer engagement, clinical utility, and potential for cross-category expansion across personalized care, women’s health, weight management, and sexual wellness. Hims & Hers’ announced acquisition of YourBio Health in December is emblematic of this trend, pairing a scaled digital health and wellness platform with at-home blood collection technology to support more personalized and decentralized care. More broadly, PitchBook’s 2026 Healthcare Outlook noted that healthtech funding remained concentrated in scaled, AI-enabled platforms, with 22 healthtech VC deals above $100 million year-to-date and Oura’s $907 million financing underscoring continued investor appetite for consumer-oriented health platforms with strong engagement and data advantages. Looking ahead, buyers and investors are likely to remain focused on businesses that blend brand strength with measurable health outcomes, recurring engagement, and differentiated data or clinical capabilities rather than stand-alone lifestyle offerings.
Petcare & Technology
Petcare & Technology transaction activity remained comparatively fragmented in Q4 2025 versus broader healthcare, with interest continuing to center on companion-animal health, preventative care, diagnostics, and technology-enabled service models. While the quarter did not produce the same volume of headline-size announced transactions seen in diagnostics or broader healthtech, underlying market fundamentals remained attractive, with the American Pet Products Association projecting U.S. pet industry expenditures of approximately $157 billion in 2025. At the same time, PitchBook’s healthcare services work indicates that veterinary remains one of the more meaningful areas of aged sponsor-backed inventory, which should support continued strategic and sponsor attention as firms look for exits, recapitalizations, and add-on opportunities. Looking ahead, we would expect buyers to remain focused on pet health categories with recurring demand and clearer differentiation – particularly diagnostics, supplements, monitoring, and other data-enabled tools that fit the broader premiumization and humanization trends shaping the category.
Notable Consumer Q4 2025 Transactions
- Mars acquired Kellanova in a transaction valued at approximately $36 billion, creating a scaled global snacking platform
- The combination brings together a portfolio of established brands, expanded manufacturing capabilities, and a broad distribution foodprint across North America and international markets
- Kimberly-Clark announced its acquisition of Kenvue on November 3, 2025, creating a combined consumer health and personal care business with an enterprise value of approximately $32 billion
- The transaction reunites Kenvue’s portfolio of self-care, skin health, and wellness brands with Kimberly-Clark’s core hygiene and personal care operations, positioning the combined company with broader category exposure and enhanced global reach
- Hershey acquired Lesser Evil during Q4 2025 for an undisclosed amount
- Lesser Evil adds a scaled better-for-you snack brand to Hershey’s portfolio, following a series of recent bolt-on transactions in adjacent snack categories
- Gildan Activewear agreed to acquire Hanes Brand in a transaction valued at approximately $6.6 billion
- The deal combines two global leaders in basic and athletic apparel, creating a larger, vertically integrated manufacturer with expanded sourcing, production, and distribution capabilities across North America and internationally
- Omnicom Group completed its acquisition of Interpublic Group in a transaction valued at $13.5 billion, following regulatory approval
- The combination brings together two of the world’s largest advertising and marketing services firms, creating a scaled platform with extensive agency networks, diversified client relationships, and broad geographic coverage across major global markets
- HNI corporation completed its acquisition of Steelcase Inc. on December 10, 2025, in a cash-and-stock transaction valued at approximately $2.2 billion
- This transaction combines two established public workplace furniture companies increasing HNI’s scale across corporate, education, and healthcare-focused customers
Notable Healthcare Q4 2025 Transactions
- Abbott Laboratories announced its acquisition of Exact Sciences in a transaction valued at up to approximately $23 billion, significantly expanding Abbott’s position in cancer diagnostics and early detection
- The transaction adds Exact Sciences’ Cologuard colorectal cancer screening test and oncology diagnostics portfolio to Abbott’s global diagnostics platform, strengthening its capabilities in preventive screening and precision medicine
- Blackstone and TPG agreed to acquire Hologic in a take-private transaction valued at approximately $18.3 billion, one of the largest medical device transactions in recent years
- The acquisition reflects strong investor conviction in women’s health and diagnostic platforms, with Hologic providing a leading portfolio spanning breast health imaging, diagnostics, and surgical solutions
- Thermo Fisher Scientific announced its acquisition of clinical trial technology provider Clario in a transaction valued at approximately $9.4 billion
- Clario provides clinical data collection and endpoint technologies used across global pharmaceutical trials, and the acquisition expands Thermo Fisher’s capabilities across clinical research, diagnostics, and life sciences services
- Hims & Hers Health announced its acquisition of YourBio Health, a developer of capillary blood collection technology designed for decentralized and at-home testing applications
- The transaction enables Hims & Hers to integrate at-home blood sampling capabilities into its consumer health platform, supporting the expansion of remote diagnostics and personalized healthcare services
- Zoetis announced the acquisition of a companion animal diagnostics and monitoring technology platform from Neogen to expand its capabilities in pet health testing and connected veterinary care.
- The transaction strengthens Zoetis’ position in the growing pet health technology market while supporting the development of data-driven diagnostic tools and preventative care solutions for companion animals
Text reproduced from the report as published by Tully & Holland. Photograph: 4300streetcar, CC BY 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q2 2025
Global deal count climbed 18.6% year-over-year while headline value slipped, and food and beverage turned in its busiest...
Read →
Consumer Industry Update Q3 2025
Global deal value jumped 35.1% year over year to $1.1 trillion, the strongest quarter since late 2021, while consumer de...
Read →
Consumer Industry Update Q1 2026
Global deal value set an all-time record while capital crowded into a handful of megadeals, and healthcare capital inves...
Read →