
Consumer Industry Update Q3 2025
The Recovery Showed Up. Consumer Buyers Kept Their Standards.
Global deal value jumped 35.1% year over year to $1.1 trillion, the strongest quarter since late 2021, while consumer dealmaking held steady and rewarded resilient brands over everything else. Our review of the third quarter of 2025.

global M&A deal value in Q3 2025, up 25.6% quarter over quarter and 35.1% year over year, the strongest quarter since late 2021.
North American deal value, a new quarterly record, up 23% from Q2 as the Fed's September and October rate cuts eased financing.
global consumer deal value across 2,404 transactions, essentially flat quarter over quarter in a selective market.
Ferrero's completed acquisition of WK Kellogg, at 1.2x revenue and 11.0x EBITDA, the quarter's largest food and beverage deal.
Keurig Dr Pepper's agreement to acquire JDE Peet's, with a planned split into separate beverage and coffee companies.
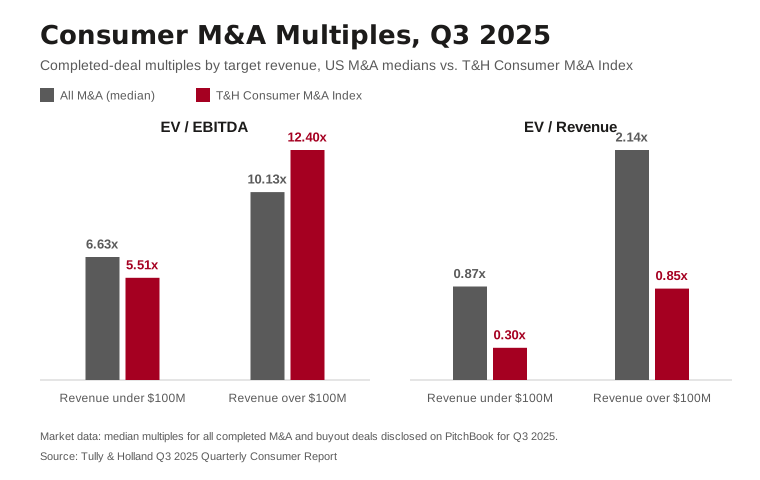
EV/EBITDA on the T&H Consumer M&A Index for targets above $100 million in revenue, versus 5.51x below that line.
General Market Commentary
The global M&A market gained strong momentum in Q3 2025, with total deal value rising 25.6% QoQ and 35.1% YoY to $1.1 trillion, while deal count increased 3.8% QoQ and 18.6% YoY to reach 12,916. The quarter marked the strongest activity since late 2021, supported by renewed investor confidence and a surge in large-cap transactions. Key themes included the return of megadeals, easing financing conditions following recent rate cuts, and continued cross-border realignment between North America and Europe.
Financial Sponsors
PE Details & Outlook
Private equity activity in Q3 2025 posted YoY increases in both deal volume (up 11.7%) and deal value (up 38%). Compared to the previous quarter, deal volume was up 3.7%, while deal value jumped by 28%. Add-ons remained the major driver of deal volume as buyers continue to seek scale.
Take-private deal volume increased during the quarter due to several megadeals in the Technology and B2B spaces, including the $55 billion take-private of Electronic Arts (EA) announced by PIF, Silverlake, and Affinity Partners in late September and Thoma Bravo’s $12.3 billion acquisition of HR software provider Dayforce announced in late August. Carveout deal volume is slightly up QoQ as large corporate players continue to evaluate the future growth potential of portfolios.
Looking ahead, PE activity will experience tailwinds from recovering risk appetite in equity markets and the Fed’s recent rate cuts. Consumer credit quality and inflation continue to be factors to monitor.
VC Details & Outlook
VC deal activity experienced a slight QoQ rebound, with deal value of $80.9 billion (up 4.9%) across 4,208 transactions (up 5.5%). On a YoY basis, the growth trend persists, with deal volume up 17.3% and deal value up 90%. Large deals account for an increasing portion of total deal value, signaling selective capital allocation.
Investment in Artificial Intelligence (AI) and Machine Learning (ML) increased from 58.6% of all deployed venture capital in Q2 2025 to 62.7% in Q3. A handful of large deals drove deal volume, including Anthropic’s $13 billion Series F and xAI’s $10 billion funding round, both completed at significantly higher valuations than previous financings.
IPO exit activity continued its modest recovery with 23 public listings compared to last quarter’s 14. Technology IPOs dominated, with notable listings including Figma, Firefly Aerospace, Gemini, and Figure. Healthcare and Biotech IPOs remain well below pre-pandemic levels as companies in the sector navigate policy uncertainty. Going forward, tight fundraising conditions are likely to persist unless exit opportunities and liquidity continue on a path to meaningful improvement.
Key Regions
North America
In North America, M&A activity accelerated in Q3 2025, with deal count up 5% QoQ to 5,066 transactions and deal value surging 23% to $762.2 billion, setting a new quarterly record and marking the strongest performance since 2021. This rebound follows a flat Q2 as investor confidence improved and the U.S. Federal Reserve’s long-anticipated rate cuts in September and October eased financing conditions. With activity on pace to surpass $2.7 trillion for the year, 2025 is positioned to be another year of growth for North American M&A.
Momentum was driven by a resurgence in megadeals and large-scale strategic transactions, particularly within the B2B, materials & resources, and energy sectors. B2B deal value rose 65% QoQ to $159.6 billion, highlighted by Union Pacific’s $89 billion acquisition of railroad operator Norfolk Southern announced in July. The return of high-value transactions underscores renewed risk appetite and optimism among North American dealmakers heading into year-end.
Europe
European M&A surged in Q3 2025, with deal value up 37.8% QoQ to $380 billion and deal count at a five-year high of 5,282. Activity was driven by rate cuts that lowered borrowing costs and reignited investor appetite, especially in financial services, healthcare, and technology, where consolidation accelerated amid cost pressures and digitalization demands. While B2B and B2C remained subdued, abundant private equity capital, favorable financing, and competitive valuations have kept Europe’s M&A market robust and positioned for continued momentum into 2026.
Asia Pacific
Asia-Pacific M&A remained subdued in 2025, with deal value down roughly 19% YoY to about $284 billion, marking a ten-year low as geopolitical tensions, regulatory uncertainty, and weaker valuations weighed on sentiment. Activity was uneven across markets, Japan stood out with record deal volume and strong value growth, while China, Southeast Asia, and Australia saw softer conditions. Despite the slowdown, strategic dealmaking continued in technology, infrastructure, and renewables, and a robust pipeline in digital and clean-energy assets positions the region for recovery once macro and policy headwinds ease.
Consumer Sector
Global M&A activity in the Consumer sector remained steady in Q3 2025, with aggregate deal value of $158.9 billion across 2,404 transactions, representing slight QoQ decreases of 1% and 4%, respectively. Despite persistent inflation, softening consumer sentiment, and tariff uncertainty, the sector is on pace to exceed 2024 levels as buyers pursue consolidation and portfolio realignment. Notable dealmaking occurred in restaurants, hotels & leisure and media, including McLaren Racing’s $4.7 billion acquisition by Bahrain’s sovereign wealth fund and Abu Dhabi-based CYVN Holdings and Nexstar Media Group’s $6.2 billion announced purchase of TEGNA, which will create the largest local broadcasting company in the U.S.
Food & Beverage
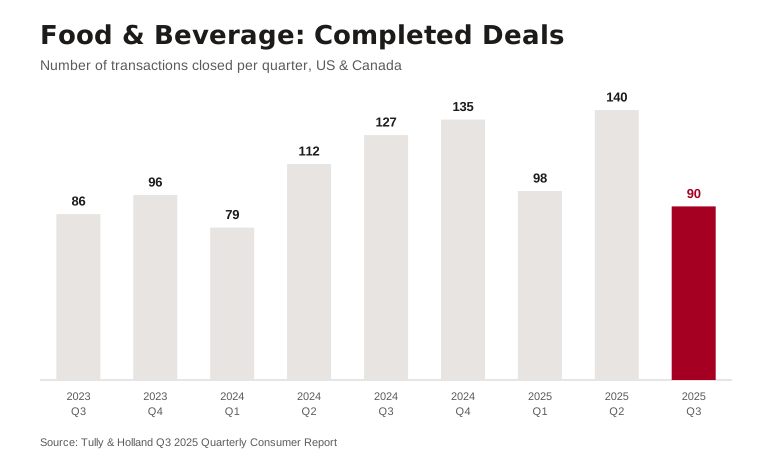
Food & Beverage M&A activity slowed during the quarter, with 90 completed deals, down 29.1% YoY and 35.7% QoQ. Against the backdrop of worsening consumer credit and concerns about rising inflation, both financial and strategic buyers are becoming more selective in their capital allocation. Companies with resilient business models and strong fundamentals remain attractive targets despite the slowdown. Major themes in Q3 2025 included international expansion, continued corporate portfolio realignments, consolidation in pursuit of enhanced scale, and diversification into growing clean-label and better-for-you categories through acquisitions.
The quarter’s largest completed transaction in the sub-sector was Ferrero International’s $3.1 billion acquisition of WK Kellogg. The deal will accelerate Ferrero’s expansion in North America by providing diversification beyond the Company’s core confectionary business and into “breakfast and snacking occasion” consumption. In addition to realizing operational synergies and gaining a well-established manufacturing, distribution, and retail footprint in the region, Ferrero can revitalize a legacy product portfolio to tap into growing consumer trends like health consciousness and anytime snacking. Reflecting a similar approach to North American expansion, private equity firm Apheon acquired Cain Foods as an add-on to its existing investment, Millbio. The combination creates a global clean bakery ingredients leader aimed at capturing growth in natural and functional baking solutions.
Another notable transaction finalized this quarter was Rhône Group’s $700 million acquisition of the fast-casual chain Freddy's Frozen Custard & Steakburgers. The deal gives Freddy’s fresh growth capital and an experienced consumer platform partner as traffic and spending in the quick service restaurant (QSR) segment face mounting challenges. With macroeconomic headwinds and changing consumer habits affecting the industry, operational efficiency through technology adoption and a sharpened value proposition that balances affordability with brand differentiation become key levers for value creation.
Throughout Q3, large corporates continued to realign their portfolios through targeted acquisitions that strengthen category focus and expand exposure to high-growth segments. On August 29, PepsiCo announced a $585 million investment that deepens its strategic partnership with Celsius Holdings (NAS: CELH), building on its initial $550 million (8.5%) stake from 2022. The deal enables the beverage giant to take over most of the distribution for Alani Nu, which Celsius snapped up earlier this year for $1.8 billion. Celsius in turn acquired PepsiCo’s Rockstar Energy brand in the US and Canada and will lead its distribution. The move will diversify Celsius’ portfolio and enhance PepsiCo’s positioning in the emerging performance drink segment.
In line with the realignment theme, on August 25, Keurig Dr Pepper (NAS: KDP) entered into a definitive agreement to acquire JDE Peet’s (AMS: JDEP) for $18 billion and announced its plan to subsequently separate into two independent companies: “Beverage Co.” and “Global Coffee Co.” The acquisition and future restructuring underscore a dual strategic objective of sharpening category focus to unlock shareholder value while achieving a broadened global reach.
Looking ahead, deal activity in Food & Beverage will likely remain selective but strategically driven, with buyers prioritizing assets that offer scale, category focus, and exposure to resilient or high-growth segments such as clean-label, functional, and performance-oriented products.
Retail & E-Commerce
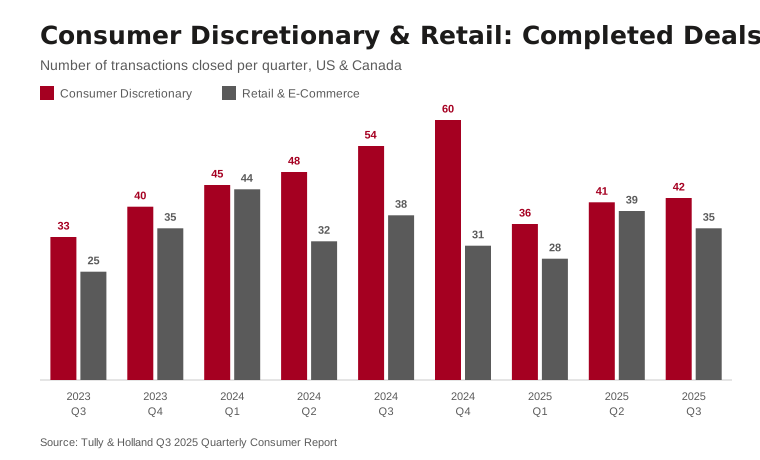
Retail and E-Commerce deal volume remained relatively steady in Q3 2025, with 35 completed transactions, down 7.9% from a strong previous quarter and 10.3% YoY. Amid broader Consumer-sector headwinds, dealmaking in the sub-sector reflected the same portfolio realignment and specialization themes seen in Food & Beverage, with heightened focus on specialty retail. The largest transaction of the quarter was Dick’s Sporting Goods’ (NYS: DKS) $2.4 billion acquisition of Foot Locker, which was announced during Q2 and completed on September 8. The acquisition will position Dick’s as a global leader in sports retail through expanded international reach, deeper brand partnerships, and operational synergies.
A big corporate divestiture in the space was Dollar Tree’s $1 billion sale of Family Dollar to Brigade Capital Management and Macellum Capital Management, completed on July 7. Dollar Tree originally acquired Family Dollar in 2014 for approximately $9.2 billion, and the recent sale reflects its decision to streamline operations and refocus on higher-margin segments after years of integration challenges, store overlap, and underperformance at the Family Dollar chain.
Further notable transactions spanned several specialty retail segments, including beauty, apparel, and home furnishings. In beauty, Mitchell Family Office announced the acquisition of luxury multi-brand retailer Cos Bar on September 16. The transaction is expected to accelerate growth in the prestige beauty space by expanding geographic reach, enhancing client experience, and leveraging operational and technology expertise. In apparel, American Exchange Group’s acquisition of VENUS Fashion continues a series of strategic purchases aimed at expanding its lifestyle platform and strengthens its position in women’s fashion by leveraging VENUS’s loyal customer base and manufacturing capabilities. In home furnishings, Auction Technology Group (ATG) acquired vintage furniture marketplace Chairish for USD $85 million on August 4. ATG aims to bolster its presence in the global art and antiques market by combining Chairish’s curated inventory, premium seller base, and design-savvy community with its own auction platform ecosystem.
Going forward, Retail & E-Commerce M&A is expected to center on portfolio reshaping and brand specialization, as buyers pursue focused growth opportunities in premium, digital, and experiential retail formats amid a cautious consumer environment.
Consumer Discretionary
Transaction volume in the Consumer Discretionary sub-sector remained nearly flat in Q3, with 42 completed deals, up 2.4% from the previous quarter’s 41. On a YoY basis, activity is down 22.2%, reflecting selective capital allocation stances from both strategic and financial buyers and a shift towards fewer, but larger, deals.
Several previously announced megadeals were completed during the quarter, including Sycamore Partners’ $23.7 billion acquisition of Walgreens Boots Alliance, 3G Capital’s $9.4 billion take-private of Skechers, and James Hardie Industries’ $8.8 billion acquisition of The AZEK Company, creating a leading platform in exterior and outdoor-living products.
Beauty continued to be a pocket of strong activity as buyers targeted brands with clear identities, loyal communities, and scalable growth potential. On September 9, Bansk Group announced the acquisition of BYOMA, highlighting continued investor interest in science-backed, Gen Z–focused skincare with accessible price points and strong digital traction. In the lucrative fragrance category, TSG Consumer acquired Phlur on August 15, reflecting growing appetite for indie fragrance labels built on storytelling, authenticity, and exceptional sensorial appeal. On September 9, L’Oreal (PAR: OR) finalized the acquisition of premium haircare products manufacturer Color Wow. The deal expands the beauty conglomerate’s professional haircare portfolio with a high-performance, salon-trusted brand known for innovation and social reach. In makeup, Windsong Global’s acquisition of KVD Beauty underscores private equity’s focus on revitalizing established clean and vegan makeup brands through sharper positioning and renewed digital engagement.
In the near term, Consumer Discretionary dealmaking is likely to stay uneven, with activity driven by large strategic transactions and selective bets on standout brands in beauty, apparel, and lifestyle that can sustain growth amid a cautious spending environment.
Tully & Holland remains committed to guiding entrepreneurs, family-owned businesses, and financial sponsors through dynamic market cycles. We look forward to helping our clients capitalize on these evolving opportunities in 2025 and beyond.
Notable Q3 2025 Transactions
- The company was acquired by Generous Brands, via its financial sponsors Butterfly Equity, Northleaf Capital Partners, Shumway Capital, and Rabo Investments, through a $500 million LBO on August 5, 2025.
- The deal will complement existing portfolio brands Bolthouse Farms, Evolution Fresh, and Sambazon. The new portfolio, nearing $1 billion in sales, will have the scale, channel strength, and owned manufacturing capabilities to cement its leadership position in the category.
- On August 15, TSG Consumer completed the acquisition of PHLUR, a subsidiary of The Center, through an LBO for an undisclosed amount.
- PHLUR has built a loyal community through sophisticated, sensorially rich fragrances crafted in collaboration with master perfumers. The brand has scaled rapidly through D2C and retail channels.
- On September 9, The Company entered into a definitive agreement to be acquired by Bansk Group through an LBO for an undisclosed sum.
- BYOMA has become one of the fastest-growing skincare brands globally due to its clinically proven solutions and prestige formulas offered at an accessible price point. The transaction brings Bansk Group’s deep expertise in scaling purpose-driven consumer brands to BYOMA, unlocking an accelerated growth trajectory.
- Garage Beer, the light lager brand co-owned by Jason and Travis Kelce and CEO Andy Sauer, was acquired by MavenHill Capital and Durational Capital Management through an LBO on August 9, 2025, for an undisclosed amount. The transaction values the company at an estimated $200 million.
- The deal will accelerate Garage Beer’s nationwide rollout and significantly expand its marketing and sales resources.
- The Company was acquired by Vilore Foods Company for an undisclosed amount on July 21, 2025.
- The acquisition marks a strategic step in expanding Vilore Foods' portfolio of authentic and beloved brands for today's diverse American consumer.
- On August 6, Freeman Spogli acquired Philz Coffee, a specialty coffee chain with 70+ U.S. locations, through a $145 million LBO.
- The transaction brings Freeman Spogli’s deep consumer and restaurant-sector expertise to Philz Coffee to accelerate its national expansion and build on its handcrafted, community-driven coffee brand while maintaining its core leadership and culture.
Text reproduced from the report as published by Tully & Holland. Photograph: MBH, CC BY 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q4 2025
Global M&A closed 2025 at nearly $5 trillion, the strongest year for dealmaking on record, and the fourth quarter set a ...
Read →
Consumer Industry Update Q2 2025
Global deal count climbed 18.6% year-over-year while headline value slipped, and food and beverage turned in its busiest...
Read →
Consumer Industry Update Q4 2024
Global consumer deal value climbed 44.2% in 2024, the sector's best showing since 2021, and the fourth quarter was the b...
Read →