
Consumer Industry Update Q4 2024
Buyers Got Their Appetite Back
Global consumer deal value climbed 44.2% in 2024, the sector's best showing since 2021, and the fourth quarter was the busiest B2C quarter of the year. Our review of the quarter the rebound became a trend.

global consumer (B2C) deal value in 2024, up 44.2% year over year, the sector's strongest full-year growth since 2021.
global B2C transactions in 2024, up 22.9% from 8,081 in 2023, with Q4 the highest-volume quarter of the year.
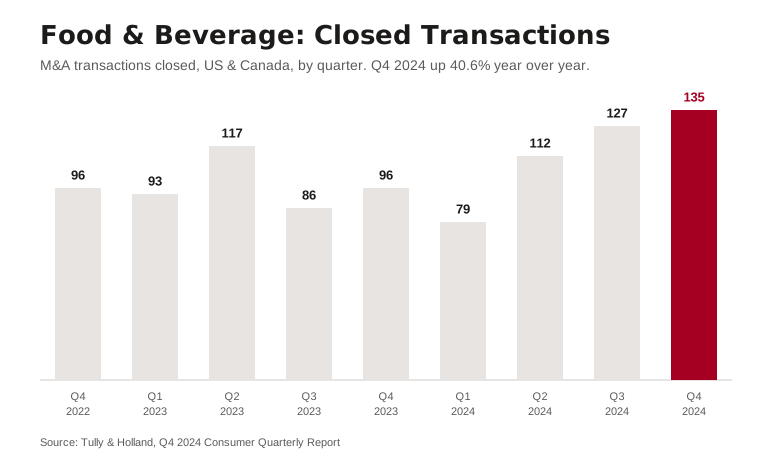
food and beverage deals closed in the US and Canada in Q4, up 40.6% year over year and the highest count in the report's nine-quarter window.
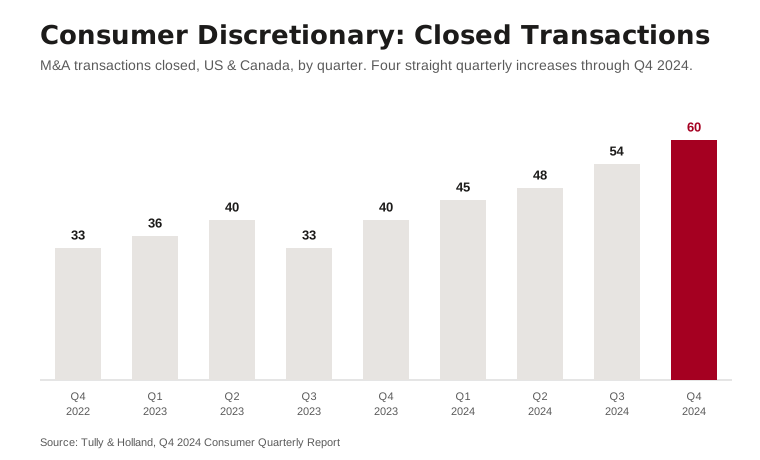
year-over-year growth in Q4 consumer discretionary closings (60 deals), the fourth consecutive quarterly increase.
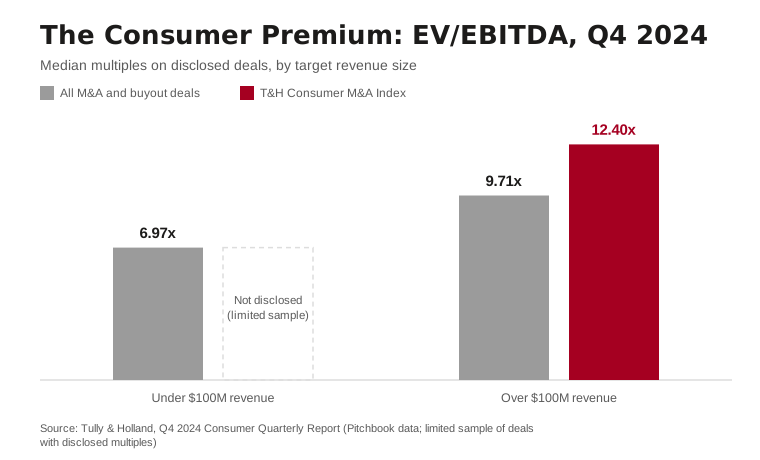
median EV/EBITDA on the T&H Consumer M&A Index for targets above $100 million in revenue, versus 9.71x across the broader deal market.
cumulative Fed rate cuts in 2024, with the 10-year Treasury closing the year at 4.37%.
General Market Commentary
Global M&A activity achieved robust growth in 2024, fueled by more supportive macroeconomic conditions and stabilizing valuations. In North America, deal value surpassed $2 trillion across 17,509 deals, marking a 16.4% YoY increase in value and a 9.8% jump in count. While the pace moderated slightly compared to Q3, market sentiment remained optimistic as buyers adjusted to a more favorable financing environment. A cumulative 100-basis-point reduction in interest rates by the Federal Reserve during 2024 has contributed to improved credit conditions and a narrowing of valuation gaps, encouraging strategic and sponsor-backed deals alike. The S&P 500 and Dow Jones both hovered near all-time highs, reflecting investor confidence. However, as the Trump administration prepared to take office, concerns lingered around potential tariffs, rising interest costs, and regulatory shifts. With the U.S. 10-year Treasury yield closing the year at 4.37%, and an inverted yield curve still in place, the bond market continued to price in economic uncertainty. Still, pent-up buyer demand, especially among strategic acquirers and PE firms, supports continued dealmaking in 2025.
VC Details & Outlook
U.S. venture capital activity ended 2024 with $209 billion in total deal value across 15,260 deals. Both figures surpass pre-pandemic and 2023 totals but are still far from zero interest-rate-policy (ZIRP)-era highs.
Fundraising remained subdued, with $76.1 billion raised across 508 funds, down from $97.5 billion in 2023, as LPs continued to evaluate liquidity and distributions.
Exit activity totaled 1,259 exits worth $149.2 billion, marking a 10% increase in volume and a 24.3% increase in value YoY, aided by a handful of large M&A exits and a slowly re-emerging IPO market.
PE Details & Outlook
8,473 deals closed with a total value of $838.5 billion, up 12.8% and 19.3% YoY, respectively. Growth was driven by improved financing, strong tech and healthcare performance, and normalization of seller expectations.
Fundraising dipped to $285 billion, down from $395 billion in 2023, though late-reported fund closures may bring the final figure higher.
Exit activity surged, with 1,501 exits generating $413.2 billion, up 16.6% in count and 49% in value, reflecting renewed confidence and increased sponsor-to-sponsor and corporate buyer activity.
Europe
European M&A finished 2024 on a strong note, with deal value rising 29.2% year-over-year and deal count increasing 17.5% YoY, according to PitchBook. The fourth quarter was particularly active, featuring several high-profile transactions such as ADNOC’s €14.7 billion acquisition of Covestro and DNB’s acquisition of Carnegie Investment Bank. These deals helped drive momentum in the materials and financial services sectors, reflecting a rebound in confidence amid stabilizing inflation and improved financing conditions. While challenges related to regulation and geopolitical tensions persist, 2025 could see further dealmaking strength as corporate and sponsor activity picks up.
Asia Pacific
The region benefited from Japan’s robust dealmaking and increased private equity engagement in India and Southeast Asia. However, cross-border transactions remained challenged by U.S.-China tensions and localized regulatory scrutiny. Private equity continued to support datacenter and AI infrastructure deals, signaling investor preference for scalable digital infrastructure.
North America
North American M&A activity in 2024 totaled $2.03 trillion across 17,509 deals, reflecting a 16.4% increase in deal value and a 9.8% increase in deal count year over year. While the full-year results were strong, Q4 saw a 23% sequential decline in deal value and a 2% drop in deal count compared to Q3, as the pace of large-cap take-private transactions slowed amid rising public market valuations.
Despite the Q4 pullback, activity remained elevated in sectors like technology, energy, and healthcare. Key transactions included Apollo’s $6.7 billion acquisition of Pactiv Evergreen and Patient Square Capital’s $4.1 billion buyout of Patterson Companies, both reflecting sponsor appetite for scaled, cash-generating platforms. Looking ahead, easing credit conditions and reduced regulatory friction under the Trump administration may support continued strength in North American M&A through 2025.
Consumer Sector
Consumer M&A activity rebounded in 2024, with global B2C deal volume rising 22.9% year over year to 9,933 transactions, and total deal value climbing 44.2% to $635.1 billion, marking the highest full-year growth in the sector since 2021.
Key trends shaping consumer M&A included:
- Increased demand for digitally native and direct-to-consumer (DTC) brands.
- High interest in categories that enable functional wellness, sustainability, and ingredient transparency.
- Strategic focus on "acquihire" transactions, particularly in e-commerce and GenAI-enabled platforms.
- Growth in PE-backed bolt-on deals to scale brand portfolios and unlock synergies.
Food & Beverage
The space remained highly attractive due to:
- Sustained consumer interest in low-sugar, high-protein, and plant-based offerings.
- Increased market share for private-label products amid price-sensitive shoppers.
- Demand for functional foods and beverages, including those with probiotics, nootropics, and adaptogens.
Notable Q4 transactions included:
- 1440 Foods' $700 million acquisition of FITCRUNCH, strengthening its portfolio in active nutrition and protein-rich snacking.
- Ongoing interest from global strategics and PE-backed consolidators, particularly targeting vertically integrated manufacturers and clean-label producers.
Outlook
M&A activity is expected to continue its upward trajectory, driven by increased demand for health-focused convenience, ethical sourcing, and category disruptors with strong consumer followings.
Retail, Catalog and E-Commerce
Retail and e-commerce M&A activity remained active in Q4 2024, buoyed by large-scale transactions such as the $6.3 billion Nordstrom take-private and strategic acquisitions aimed at brand consolidation and digital integration. While PitchBook does not provide quarterly retail-specific deal counts, it notes that Q4 saw the highest B2C deal volume of the year, signaling sustained appetite for consumer-facing assets. Retail M&A was heavily driven by:
- Acquisitions of DTC brands with loyal communities and scalable logistics.
- Integration of AI-driven personalization tools, including virtual try-ons and recommendation engines.
- Increased activity around omnichannel enablers, including last-mile logistics and checkout optimization platforms.
Acquirers focused on:
- Building multi-brand platforms with unified back-office operations.
- Investing in customer experience (CX) tech stacks, combining physical and digital journeys.
- Leveraging first-party data and CRM-driven marketing.
Noteworthy themes:
- Larger strategics acquiring specialty retailers and curated marketplaces.
- PE sponsors executing buy-and-build strategies to consolidate fragmented niche segments (e.g., premium beauty, outdoor gear).
Consumer Discretionary
Consumer discretionary M&A activity gained momentum in 2024, supported by investor interest in brands aligned with evolving lifestyle, wellness, and sustainability trends. While PitchBook does not provide a specific quarterly deal count for this sub-sector, it comments that Q4 recorded the highest volume of B2C M&A activity for the year, capping off a strong recovery in consumer-facing dealmaking with 9,933 deals recorded for 2024 vs. 8,081 in 2023.
Acquirers focused on:
- Eco-conscious brands gaining favor amid ESG mandates.
- Pet care and wellness continuing as standout growth categories.
- Increased investment in at-home fitness, well-being tech, and personal care innovation.
Noteworthy themes:
- Continued PE activity in pet health platforms, reflecting the humanization of pets trend.
- Strategic acquisitions in home and leisure tech, including connected fitness and smart appliances.
- Strong buyer demand for durable discretionary brands with clear identity and strong digital channels.
As 2024 closed, the global M&A and private markets environment appeared cautiously optimistic. The U.S. economy remained resilient, bolstered by a strong labor market, lower interest rates, and improved credit availability. While geopolitical risks and regulatory uncertainty continued to create friction, strategic buyers and financial sponsors alike were prepared to act decisively. Sellers considering a liquidity event may find now an opportune time to engage, particularly as buyer interest and valuations trend upward.
Tully & Holland remains committed to guiding entrepreneurs, family-owned businesses, and financial sponsors through dynamic market cycles. We look forward to helping our clients capitalize on these evolving opportunities in 2025 and beyond.
Notable Q4 2024 Transactions
- FITCRUNCH, a Florida-based provider of high-protein snacks and nutrition bars, was acquired by 1440 Foods for $700 million, with the transaction announced on November 1, 2024.
- This strategic deal enhances 1440 Foods' portfolio and scale in the functional snacking category, aligning with increased demand for performance nutrition and better-for-you snack options.
- GHOST, a Nevada-based lifestyle sports nutrition brand specializing in energy drinks and nutritional supplements, was acquired by Keurig Dr Pepper (NASDAQ: KDP) in a transaction announced on October 24, 2024.
- Under the terms of the agreement, KDP will initially purchase a 60% stake in GHOST for $990 million, with plans to acquire the remaining 40% in 2028.
- noosa yoghurt, a Colorado-based producer of Australian-style yogurt, was divested by Campbell Soup Company and acquired by Lakeview Farms, LLC in a transaction announced in November 2024.
- The sale aligns with Campbell’s strategy to focus on its core product categories following its acquisition of Sovos Brands earlier in the year. The transaction includes noosa’s manufacturing facility in Bellvue, Colorado, and the transfer of approximately 240 employees to Lakeview Farms. Financial terms were not disclosed.
- Sour Strips, a Texas-based sour candy brand founded in 2019 by social media personality Maxx Chewning, was acquired by The Hershey Company in a transaction announced on November 8, 2024.
- The acquisition enhances Hershey's sweets portfolio and aims to expand its reach to new consumers across more snacking occasions. Chewning will continue to lead marketing and innovation efforts for the brand under Hershey's ownership. Financial terms of the deal were not disclosed.
- Nordstrom Inc., a Seattle-based luxury department store chain, announced on December 23, 2024, that it has agreed to be acquired and taken private by members of the Nordstrom family in partnership with Mexican retailer El Puerto de Liverpool. The move aims to provide Nordstrom with greater flexibility to navigate the evolving retail landscape away from the pressures of public markets.
- The all-cash transaction values Nordstrom at approximately $6.25 billion, with shareholders receiving $24.25 per share, representing a 42% premium over the stock price prior to reports of the potential deal.
Text reproduced from the report as published by Tully & Holland. Photograph: Axisadman, CC BY-SA 3.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q3 2024
Consumer M&A closed 219 transactions in Q3 2024, up 52% from a year earlier, as a first Fed rate cut and post-election o...
Read →
Consumer Industry Update Q2 2025
Global deal count climbed 18.6% year-over-year while headline value slipped, and food and beverage turned in its busiest...
Read →
Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →