
Consumer Industry Update Q3 2024
The Recovery Showed Up in the Deal Count
Consumer M&A closed 219 transactions in Q3 2024, up 52% from a year earlier, as a first Fed rate cut and post-election optimism put buyers back to work. Our review of the quarter that confirmed the rebound, preserved from the period.

global M&A deal value in Q3 2024, up 14.0% year over year and the fourth consecutive quarter of improving trends.
consumer M&A transactions closed in the US and Canada across the three verticals we track, up 52% from Q3 2023.
year-over-year growth in closed deals for Food & Beverage, Retail & E-Commerce, and Consumer Discretionary.
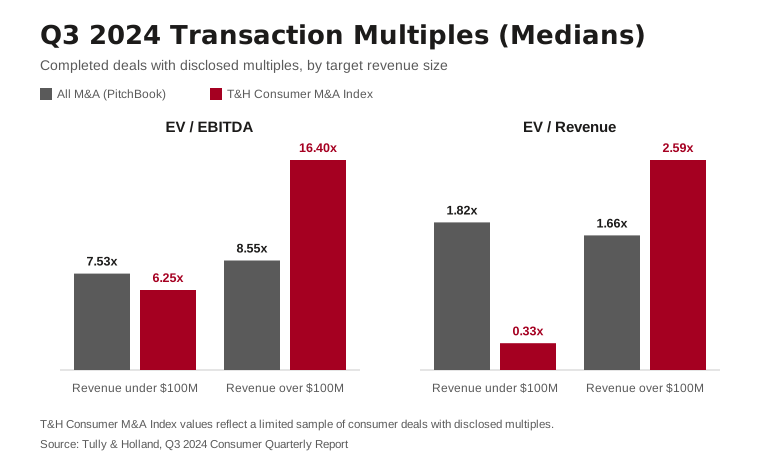
median EV/EBITDA in our consumer index for targets above versus below $100M of revenue, a premium for scale (limited sample).
Mars's acquisition of Kellanova, the quarter's defining consumer transaction.
year-over-year jump in US private equity exit value ($107.1B), as sponsors returned to both sides of the table.
General Market Commentary
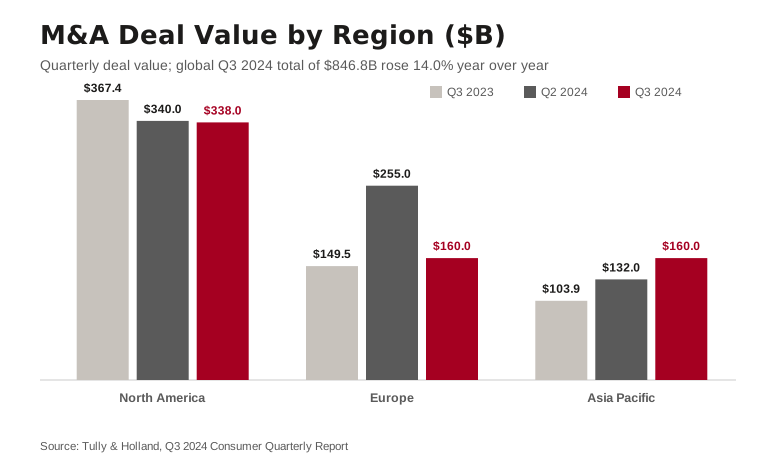
Global M&A activity for Q3 of 2024 increased 14.0% on a YoY basis from approximately $742.8 billion (Q3 2023) to $846.8 billion (Q3 2024). We are encouraged by Q3's strong year-over-year increase in transactions, marking four consecutive quarters of improving M&A trends since Q2 2023. The Federal Reserve's recent 25 basis point interest rate cut, coupled with the re-election of President Donald Trump, has significantly influenced the financial markets. Investors perceive the rate reduction as a supportive measure for economic growth, contributing to record highs in major stock indices. The S&P 500 closed above 6,000 for the first time, and the Dow Jones Industrial Average surpassed 44,000. Additionally, the election outcome has fueled optimism among banks and investors, anticipating that the Trump administration will implement policies favorable to mergers and acquisitions (M&A) activity. This sentiment is reflected in the surge of equity values and increased market confidence. However, the bond market has expressed concerns that increased spending and trade policies could push costs higher, potentially leading the Fed to pause. Currently, market expectations for another Federal Reserve rate cut in December are mixed. Some investors anticipate a further reduction at the December 17-18 meeting. However, recent economic indicators, such as a slight uptick in inflation and robust labor market data, have led others to believe the Fed may pause additional cuts to assess the economy's trajectory. Analysts are closely monitoring upcoming economic reports and Federal Reserve communications for clearer guidance on future rate decisions. Despite these uncertainties, M&A sentiment remains positive, supported by significant pent-up demand. Any business owner contemplating a sale may wish to take advantage of these favorable marketplace conditions.
VC Details & Outlook
Through Q3, US VC firms completed approximately 11,834 deals with a cumulative value of $131.4 billion, 2 representing a marginal decrease in dealmaking, but a 4% increase in deal value compared to 2023 figures (11,935 deals totaling $125.9 billion).3
US VC firms had raised $65.1 billion across 380 funds at the end of Q3,2 representing an approximate 52% YoY increase in US VC fundraising dollars and a 14% increase in participating funds compared to 2023’s figures ($42.7 billion raised across 334 funds at the end of Q3 2023).3
During Q3, sponsors exited approximately 243 US VC-backed companies with a cumulative exit value of $10.4 billion,2 representing an approximate 14% YoY decrease in exit count, and a 71% decrease in exit value compared to Q3 2023 figures (284 companies valued at $35.8 billion).3
PE Details & Outlook
Through Q3, US PE firms completed approximately 6,375 deals with a cumulative value of 650.2 billion,4 representing a 3% increase in dealmaking and a 6% increase in deal value compared to 2023 figures (6,162 deals totaling $611.6 billion). 5
US PE firms had raised $263.3 billion across 220 funds at the end of Q3,4 representing an approximate 9% YoY increase in US PE fundraising dollars, but a 15% YoY decrease in participating funds compared to 2023’s figures ($242.0 billion raised across 258 funds at the end of Q3 2023).5
During Q3, sponsors exited approximately 394 US PE-backed companies with a cumulative exit value of $107.1 billion,4 representing an approximate 43% YoY increase in exit count, and a 143% increase in exit value compared to Q3 2023 figures (275 companies valued at $44.1 billion).5
Europe
M&A deal value in Europe totaled approximately $160.0 billion in Q3 2024, down 37% from Q2 2024 ($255.0B), but up 7% from Q3 2023 ($149.5B). Noteworthy transactions during Q3 included Harbour Energy’s (LON: HBR) acquisition of Wintershall Dea’s asset portfolio for $11.2 billion, a Russian consortium of investors’ acquisition of Yandex’s Russian assets for $5.4 billion, and Cinven’s acquisition of Alter Domus for $5.4 billion. Despite persistent challenges from inflation, geopolitical uncertainty, and regulatory complexities, sectors like renewable energy, industrial manufacturing and financial technology are expected to drive deal activity.
Asia Pacific
M&A deal value in Asia totaled approximately $160.0 billion in Q3 2024, up 21% from Q2 2024 ($132.0B) and 54% from Q3 2023 ($103.9B). Of note were the acquisitions of American Tower Corporation’s (NYS: AMT) India unit, ATC India, by GIC, British Columbia Investment Management, and Brookfield Asset Management (TSE: BAM) for $2.5 billion, Hollysys Automation Technologies Ltd by Ascendent Capital Partners for $1.66 billion, and Infocom Corp (TSE: 4348) by Blackstone (NYS: BX) for $1.65 billion. Increased regulatory oversight and ongoing geopolitical tensions, particularly between China and Western nations, are influencing cross-border M&A activity in Asia-Pacific. Despite slowing economic growth in some markets, Japan stands out as a key player, experiencing another strong M&A year spurred by shifts in corporate governance, demographic changes, and the increasing role of private equity.
North America
M&A deal value in North America totaled approximately $338.0 billion in Q3 2024, down slightly from Q2 2024 ($340.0B), and down 8% from Q3 2023 ($367.4B). Noteworthy Q3 deals included the acquisitions of Kellanova (NYS: K) by Mars for $35.9 billion, Endeavor Energy Resources by Diamondback Energy (NAS: FANG) for $26.0 billion, and WestRock (NYS: WRK) by Smurfit Kappa Group (DUB: SK3) for $11.0 billion. The M&A landscape in North America is anticipated to stay resilient throughout the year, even as it navigates persistent challenges from regulatory scrutiny and economic pressures, including elevated interest rates and inflation. Companies are increasingly adopting strategic approaches to dealmaking, focusing on transactions that balance cost synergies with opportunities for growth, especially in high-priority sectors such as technology and energy.
Consumer Sector
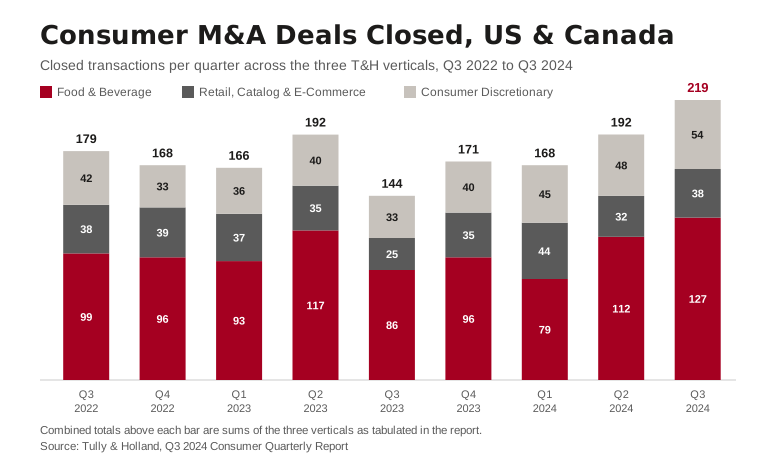
A total of 219 M&A transactions closed in the US and Canada in Q3 2024 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is up approximately 14% from Q2 2024 (192), and 52% from Q3 2023 (144). Notably, BCG emphasizes “the ongoing push for digitization remains a major driver of deals. Recent advances in generative AI (GenAI) and robotics, in particular, will continue to fuel M&A activity as companies pursue emerging technological solutions and tech-enhanced capabilities. In this context, “acquihire” deals-in which the acquirer’s primary goal is to gain access to a company’s highly skilled employees-are likely to become more common.”
Food & Beverage
A total of 127 M&A transactions closed in the US and Canada in Q3 2024 in the Food & Beverage sector, up approximately 13% from Q1 2024 (112), and 48% from Q3 2023 (86). Looking ahead, we expect M&A activity in this large sector to stay strong, driven by demand for health-focused products like plant-based proteins, low-sugar beverages, and snacks with simple ingredients. Sustainable practices and transparency in sourcing are also attracting interest, making these areas ripe for continued growth.
Retail, Catalog and E-Commerce
A total of 38 M&A transactions closed in the US and Canada in Q3 2024 in the Retail, Catalog and E-Commerce sectors, up approximately 19% from Q2 2024 (32), and 52% from Q3 2023 (25). Retailers are increasingly using M&A to integrate experiential commerce, acquiring platforms that offer virtual try-ons and interactive shopping to deepen customer engagement. Additionally, they are buying direct-to-consumer brands with strong digital followings to expand their reach and investing in AI-powered data analytics to enhance personalization and drive customer experiences.
Consumer Discretionary
A total of 54 M&A transactions closed in the US and Canada in Q3 2024 in the Consumer Discretionary sector, up approximately 13% from Q2 2024 (48), and 64% from Q3 2023 (33). M&A activity in Consumer Discretionary sub-sector is increasingly focused on eco-friendly brands, pet wellness products, and home fitness tech, reflecting consumer demand for sustainable, health-centered, and lifestyle-enhancing options.
As we move through Q4 2024, the U.S. 10-year Treasury rate, a critical measure for the M&A landscape, stands at 4.37%, which is elevated compared to the 10-year historical average of around 2.5%. Notably, the yield curve is currently inverted, with a negative spread of approximately 44 basis points between the overnight rate and the 10-year rate, signaling bond market concerns about future economic conditions. We believe these concerns stem from the Trump administration’s spending and trade policies, which could influence future Fed rate decisions. Despite this, we remain optimistic about the M&A sector, supported by the current strength of the U.S. economy and significant pent-up buyer demand driving M&A activity. In the consumer sector where we operate, trends such as sustainability, wellness, private label, and omnichannel connectivity are becoming increasingly important. As mentioned in our opening paragraph, sellers considering entering the market would benefit from starting the process sooner rather than later. For over 30 years, Tully & Holland has been dedicated to advising, serving, and advocating for owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q3 2024 Transactions
- Kellanova (NYS: K), a Michigan-based global manufacturer and marketer of salty snacks, snack bars, frozen breakfast fare, meat alternatives, and other packaged goods, was acquired by Mars for $35.9 billion on August 20th, 2024.
- The acquisition enables Mars to significantly expand its snacking platform, allowing it to even more effectively meet consumer needs and drive profitable business growth.
- Varsity Brands, a Texas-based operator of a sports apparel agency intended for educators, coaches, and students, was acquired by Kohlberg Kravis Roberts (NYS: KKR) through a $4.75 billion LBO on August 26th, 2024.
- The transaction was supported by $2.78 billion debt financing and KKR plans to introduce a broad-based equity ownership program for all Varsity Brands employees, an incentive traditionally reserved for senior executives.
- Maple Leaf Sports & Entertainment (MLSE), a Toronto-based operator of sports teams and venues serving sports enthusiasts, was acquired by Rogers Communications (TSE: RCI.B) for $3.47 billion on September 18, 2024.
- Rogers and Bell (TSE: BCE) initially acquired a majority stake in MLSE in 2012. With the recent purchase of Bell’s 37.5% stake, Rogers will double its ownership, gaining control of some of Canada’s most popular sports teams.
- José Santiago, a Puerto Rico-based distributor specializing in traditional foodservice products, as well as specialty, gourmet, and value-added offerings, was acquired by Performance Food Group (NYS: PFGC) for $1.0 billion on July 1, 2024.
- This acquisition enhances PFG's foodservice business by expanding into new geographic territories in the Caribbean, which offer significant potential for sales and profit growth.
- BioVectra, a Canada-based provider of contract development and manufacturing services for intermediates and active pharmaceutical ingredients, was acquired by Agilent Technologies (NYS: A) for $925 million on September 20, 2024.
- The acquisition provides Agilent Technologies with the ability to expand the range of capabilities available to global pharmaceutical partners working on next-generation treatments and therapeutics that will improve patients’ lives.
Text reproduced from the report as published by Tully & Holland. Photograph: ChristianBier, CC BY-SA 3.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →
Consumer Industry Update Q2 2024
Consumer M&A closings returned to 192 in the second quarter of 2024, up 14% from Q1, with food and beverage transactions...
Read →
Consumer Industry Update Q4 2024
Global consumer deal value climbed 44.2% in 2024, the sector's best showing since 2021, and the fourth quarter was the b...
Read →