
Consumer Industry Update Q1 2024
The Thaw Takes Hold
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the mix underneath shifted. Our Q1 2024 review, published in spring 2024, of a market twelve months into its rebound.

global M&A deal value in Q1 2024, up 31% from $575.1 billion a year earlier, capping roughly twelve months of improving trends.
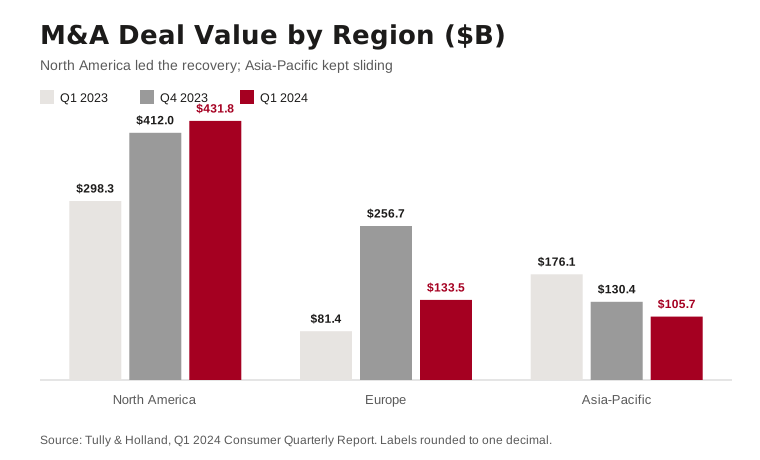
North America deal value, up 45% year over year and 5% over Q4 2023, the strongest of any region.
consumer M&A transactions closed in the US and Canada across the three verticals we track, within a few deals of both the prior quarter and the prior year.
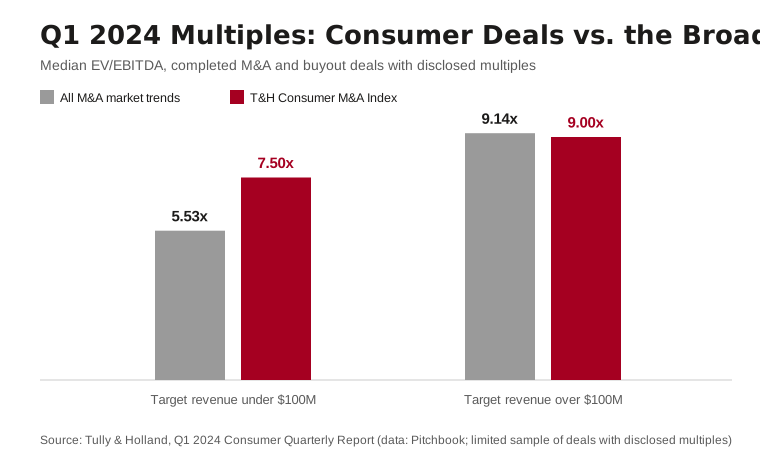
median EV/EBITDA for sub-$100M-revenue targets in our Consumer M&A Index versus the broad M&A market, a premium for consumer specificity.
year-over-year deal-count growth in Retail, Catalog & E-Commerce and in Consumer Discretionary, while Food & Beverage counts fell 15%.
Campbell Soup's purchase of Sovos Brands, maker of Rao's, one of five headline consumer deals profiled in the quarter.
General Market Commentary
Global M&A activity for Q1 of 2024 increased 31% on a YoY basis from approximately $575.1 billion (Q1 2023) to $755.1 billion (Q1 2024). We are encouraged by the Q1 increase, especially given that we have now seen essentially 12 months of improving trends since the beginning of Q2 2023. On a macro-economic basis, despite the Fed sending somewhat mixed messages about future action, the fact the Fed has paused any additional rate hikes since July is a positive. Stability of rates, even when we would of course prefer to see a downward trend, allows buyers and sellers alike to have an easier time establishing an equilibrium of expectations around valuation metrics and the attendant cost of debt. We anticipate that this “quiet” period will remain the status quo for the Fed as we make our way into Q3 of 2024, as trade-offs between major catalysts for action, such as inflation and unemployment, continue to offset each other. Marry this macro-overlay with strong, pent-up demand to become more proactive in the PE space, and we anticipate the YOY quarterly increases to sustain. The current strength of the public markets year to date, and some exceptionally large M&A announcements that have already been made in 2024, would only seem to lend credence to this viewpoint. For owners/sellers who are contemplating a transaction, we would recommend acting soon given this backdrop and before the potential overhang of November Presidential elections kicks in.
VC Details & Outlook
During Q1 2024, US VC firms completed approximately 3,925 deals with a cumulative value of $36.6 billion,2 representing a 1% YoY increase in dealmaking, but a 1% YoY decrease in deal value compared to Q1 2023 figures (3,888 deals totaling $37.0 billion).3
During Q1 2024, US VC fundraising totaled approximately $9.3 billion spread across 100 funds,2 representing an approximate 21% YoY decrease in fundraising dollars, but a 1% YoY increase in participating funds compared to Q1 2023 figures ($11.7 billion spread across 99 funds).3
During Q1 2024, sponsors exited approximately 300 US VC-backed companies with a cumulative exit value of $18.4 billion,2 representing an approximate 32% YoY increase in exit count and a 217% YoY increase in exit value compared to Q1 2023 figures (227 companies valued at $5.8 billion).3
PE Details & Outlook
During Q1 2024, US PE firms completed approximately 2,105 deals with a cumulative value of $145.4 billion,4 representing a 3% YoY decrease in dealmaking and a 36% YoY decrease in deal value compared to Q1 2023 figures (2,161 deals totaling $227.15 billion).5
During Q1 2024, US PE fundraising totaled approximately $76.8 billion spread across 63 funds,4 representing an approximate 15% YoY increase in fundraising dollars, but a 14% YoY decrease in participating funds compared to Q1 2023 figures ($66.8 billion spread across 73 funds).5
During Q1 2024, sponsors exited approximately 316 US PE-backed companies with a cumulative exit value of $66.7 billion,4 representing an approximate 13% YoY increase in exit count, but a 26% YoY decrease in exit value compared to Q1 2023 figures (279 companies valued at $90.1 billion).5
Europe
M&A deal value in Europe totaled approximately $133.5 billion in Q1 2024, down 48% from Q4 2023 ($256.72B), but up 64% from Q1 2023 ($81.4B). Noteworthy transactions during Q1 included Novozymes’ (CSE: NSIS B) acquisition of Chr. Hansen (CPH: CHR) for $12.3 billion, Attestor Capital, EP Equity Investment, and Fimalac Group’s collective acquisition of Casino Guichard-Perrachon (PAR: CO) for $1.32 billion, and One Rock Capital Partners’ acquisition of Constantia Flexibles for $1.23 billion. M&A activity in Europe is expected to recover, supported by stronger performance/confidence in the public markets and expectations of monetary easing.
Asia Pacific
M&A deal value in Asia totaled approximately $105.7 billion in Q1 2024,1 decreasing 19% from Q4 2023 ($130.43B) and 40% from Q1 2023 ($176.1B). Of note were the acquisitions of Vinda International Holdings (HKG: 03331) by Asia Pacific Resources International Holdings for $1.87 billion, OUTSOURCING Inc. (TSE: 2427) by Bain Capital for $1.53 billion, and Tokopedia by ByteDance for $1.5 billion. Asia-Pacific’s PE market paralleled global trends, with Japan emerging as a standout. Notably, deal value in Japan rose 183% over the prior five-year average, making it the region’s No. 1 deal market.
North America
M&A deal value in North America totaled approximately $431.8 billion in Q1 2024, up 5% from Q4 2023 ($411.98B) and 45% from Q1 2023 ($298.3B). Noteworthy Q1 deals included the acquisitions of Masonite (NYS: DOOR) by Owens Corning (NYS: OC) for $3.9 billion, Alterra Mountain by KSL Capital Partners for $3.0 billion, and Sovos Brands (NAS: SOVO) by Campbell Soup (NYS: CPB) for $2.7 billion. Primary catalysts for dealmaking are anticipated to be the potential for lower interest rates in 2024 and increased activity from private equity buyers, who are poised to deploy substantial reserves of dry powder.
Consumer Sector
A total of 168 M&A transactions closed in the US and Canada in Q1 2024 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is down approximately 2% from Q4 2023 (171) but up 1% from Q1 2023 (166). Notably, McKinsey mentions that while having a strong M&A engine is more important than ever, “sophisticated acquirers also adopt a mindset of mutual partnership with the target companies to protect what made them successful and to help them grow.”
Food & Beverage
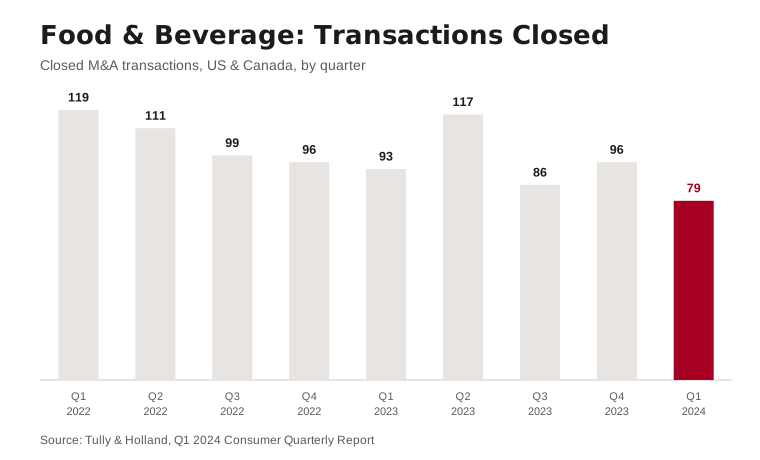
A total of 79 M&A transactions closed in the US and Canada in Q1 2024 in the Food & Beverage sector, down approximately 18% from Q4 2023 (96) and 15% from Q1 2023 (93). Going forward, we anticipate that beverages, especially health and wellness drinks, will attract heightened interest from both strategic and financial investors.
Retail, Catalog and E-Commerce
A total of 44 M&A transactions closed in the US and Canada in Q1 2024 in the Retail, Catalog and E-Commerce sectors, up approximately 26% from Q4 2023 (35) and 19% from Q1 2023 (37). The pursuit of omni-channel strategies is expected to remain a key driver of M&A activity, with online businesses striving to engage customers in physical store settings.
Consumer Discretionary
A total of 45 M&A transactions closed in the US and Canada in Q1 2024 in the Consumer Discretionary sector, up approximately 13% from Q4 2023 (40) and 25% from Q1 2023 (36). We expect M&A volumes in this sub-sector to sustain its momentum, buoyed by the increasing trends in consumer wellness products and the rise in pet ownership and spending.
As we migrate through Q2 of 2024, with valuations seeming to have settled into a new normal, we expect to see a continued acceleration of transaction volumes and absolute values in the M&A sector. This is especially likely given that the Fed seems satisfied at the current static posture, with a slight tilt towards potential rate cuts towards the end of this year. This stabilization of the economic backdrop, along with the resilience of certain sought after themes and trends in high-demand targets, should prove a stable base from which to accelerate M&A. Specifically, in the consumer sector where we do our work, trends of sustainability, wellness, transparent supply chains, private label, and omnichannel connectivity continue to rise to the forefront of import. Further, as stated in our opening paragraph, sellers considering going to market would be well served to begin that process sooner rather than later. We at Tully & Holland, as we have for over 30 years, remain ready to advise, serve, and advocate on behalf of owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q1 2024 Transactions
- Masonite (NYS: DOOR), a Tampa-based manufacturer and distributor of interior and exterior doors serving both repair and remodel and new construction demand, was acquired by Owens Corning (NYS: OC) for $3.9 billion on March 15th, 2024.
- The addition of Masonite to Owens Corning marks a significant milestone for Owens Corning, as it further strengthens its position as a market leader in building and construction materials.
- Sovos Brands, a California-based producer of food products, was acquired by Cambell Soup (NYS: CPB) for $2.7 billion on March 12th, 2024.
- Sovos’ products include Rao’s Homemade pasta sauces (including tomato-based sauces, Alfreda sauces, and Pesto sauces), pizza sauces, and dry pasta; Rao’s Homestyle meat-based pasta sauces; and Rao’s Made for Home frozen entrees and soups.
- The transaction strengthens and diversifies Cambell Soup’s meals and beverages portfolio with additional brands.
- Resident Home, a San Francisco-based manufacturer of household products intended to specialize in the home goods space, was acquired by Ashley Furniture Homestore for nearly $1.0 billion on March 6th, 2024.
- Resident Home expects to experience improved sourcing and efficiencies to foster additional growth in both its direct-to-consumer and wholesale businesses.
- Melissa & Doug, a Connecticut-based manufacturer of toys and children’s products intended for creating a fun learning experience, was acquired by Spin Master (TSE) for $950 million on January 2nd, 2024.
- The acquisition bolsters Spin Master’s position as a leader in the children’s entertainment industry and will bring complementary capabilities to early childhood toys by adding the company’s offerings of open-ended, creative, and developmental wooden toys.
- Chico FAS (NYS: CHS), a Florida-based apparel retailer with a portfolio of private-label brands that sell women’s clothing and accessories, was acquired by Sycamore Partners Management through a $1.0 billion public-to-private LBO on January 5th, 2024.
- The Chico’s brands will be merged under Sycamore’s recently formed Knitwell Group, which includes the Ann Taylor and Loft specialty fashion chains.
Text reproduced from the report as published by Tully & Holland. Photograph: Clark Young clark1, CC0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q3 2024
Consumer M&A closed 219 transactions in Q3 2024, up 52% from a year earlier, as a first Fed rate cut and post-election o...
Read →
Consumer Industry Update Q4 2023
Global M&A rose 13% year-over-year in Q4 2023, consumer deal counts jumped 19% from the prior quarter, and quality consu...
Read →
Consumer Industry Update Q3 2023
Global M&A value slipped just 3% year over year in Q3 2023 while the Fed held still, and deal metrics began to normalize...
Read →