
Consumer Industry Update Q4 2023
A Quiet Fed and a Busier Market
Global M&A rose 13% year-over-year in Q4 2023, consumer deal counts jumped 19% from the prior quarter, and quality consumer businesses commanded roughly twice the market's median EBITDA multiple. Our review of the quarter the recovery took hold, as we saw it then.

global M&A value in Q4 2023, up 13% year-over-year, extending the run of YoY quarterly gains that began in Q2 2023.
consumer M&A transactions closed in the US and Canada, up 19% from Q3 2023 and ahead of the prior-year quarter.
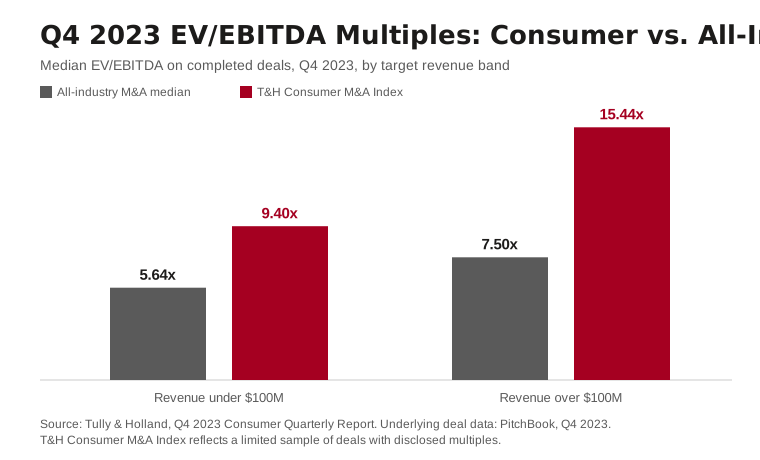
median EV/EBITDA on T&H Consumer M&A Index deals above $100 million of revenue, versus a 7.50x all-industry median.
The J.M. Smucker Co.'s acquisition of Hostess Brands, the quarter's headline consumer transaction.
Europe's quarter-over-quarter surge in deal value to $256.72 billion; North America rose 10% to $411.98 billion.
Q4 US private equity fundraising, up 49% from Q3, dry powder stacking up for 2024.
General Market Commentary
Global M&A activity for Q4 of 2023 increased 13% on a YoY basis from approximately $774.2 billion (Q4 2022) to $872.5 billion (Q4 2023), bringing 2023’s full-year M&A value to $2.9 trillion, representing a 19% YoY decline from 2022’s $3.6 trillion. We are encouraged by the Q4 increase, in light of the continuing positive YOY quarterly comparisons trends we have been seeing since the beginning of Q2 of 2023. This increasing trend of deal value metrics makes even more logical sense, and is in keeping with past cycles, given that the Fed has paused any additional rate hikes since July. It is no coincidence, now or over historical periods, that when the Fed quiets its activity, both buyers and sellers alike have an easier time establishing an equilibrium of expectations around valuation metrics and the attendant cost of debt. We anticipate that this “quiet” period will remain the status quo for the Fed as we make our way through the first half of 2024, as trade-offs between major catalysts for action, such as inflation and unemployment, continue to offset each other. Marry this macro-overlay with strong pent-up demand to become more proactive in the PE space, and we anticipate the YOY quarterly increases to continue. The current strength of the public markets year to date, and some exceptionally large M&A announcements that have already been made in 2024, would only seem to lend credence to this viewpoint. For owners/sellers who are contemplating a transaction we would recommend acting soon, given this backdrop and before the potential overhang of November Presidential elections kicks in.
VC Details & Outlook
In 2023, US VC firms completed approximately 15,766 deals with a cumulative value of $170.6 billion, representing a 10% YoY decrease in dealmaking and 30% decrease in deal value compared to 2022 figures (17,592 deals totaling $242.2 billion).2
During Q4, US VC fundraising totaled approximately $24.2 billion, representing a 157% sequential increase from Q3 2023 ($9.4 billion).2
US VC fundraising totaled approximately $66.9 billion across 474 funds for the year, representing an approximate 61% YoY decrease in fundraising dollars and 65% decrease in participating funds ($172.8 billion raised 1,340 funds at the end of 2022).2
In 2023, sponsors exited approximately 1,129 US VC-backed companies with a cumulative exit value of $61.5 billion, representing an approximate 19% YoY decrease in exit count and 22% decrease in exit value compared to 2022 figures (1,401 companies valued at $78.6 billion).2
PE Details & Outlook
In 2023, US PE firms completed approximately 7,346 deals with a cumulative value of $645.3 billion, representing a 16% YoY decrease in dealmaking and 29% decrease in deal value compared to 2022 figures (8,755 deals totaling $915.1 billion).3
During Q4, US PE fundraising totaled approximately $132.8 billion, representing a 49% sequential increase from Q3 2023 ($89.0 billion).3
US PE fundraising topped $374.8 billion across 381 funds for the year, representing an approximate 1% YoY decrease in fundraising dollars and 51% decrease in participating funds ($379.2 billion raised across 779 funds at the end of 2022).3
In 2023, sponsors exited approximately 1,121 US PE-backed companies with a cumulative exit value of $234.1 billion, representing an approximate 17% YoY decrease in exit count and 23% decrease in exit value compared to 2022 figures (1,356 companies valued at $306.0 billion).3
Europe
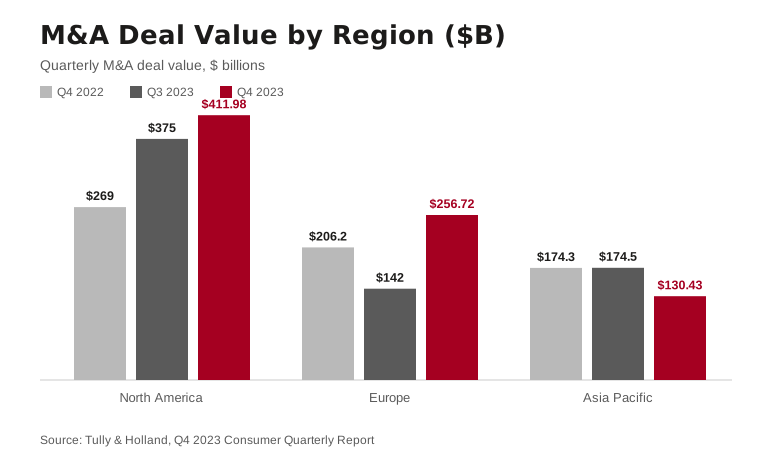
M&A deal value in Europe totaled approximately $256.72 billion in Q4, up 81% from Q3 2023 ($142.0B) and 25% from Q4 2022 ($206.2B). Noteworthy transactions during Q4 included Kering’s (PAR: KER) acquisition of Creed Fragrances for $3.83 billion, Orora’s (ASX: ORA) acquisition of Saverglass for $1.43 billion, and Georg Fischer’s (SWX: GF) acquisition of Uponor (HEL: UPONOR) for $2.22 billion. M&A activity in this region is poised for growth amid easing monetary policies, heightened ESG focus, and booming sectors like artificial intelligence (AI), technology, and consumer health.
Asia Pacific
M&A deal value in Asia totaled approximately $130.43 billion in Q4,5 decreasing 25% from Q3 2023 ($174.5B) and Q4 2022 ($174.3B). Of note were the acquisitions of Jabil’s (NYS: JBL) manufacturing operations in Chengdu and Wuxi by BYD Electronic (HKG: 00285) for $2.2 billion, Ramsay Sime Darby Health Care by Columbia Asia for $1.22 billion, and ALLCAR by Auto Hands for $1.04 billion. Escalating geopolitical tensions between China and the US have subdued cross-border activity and overall M&A; however, a potential boost is anticipated from the heightened M&A volumes in Japan, where deal value increased by 23% YoY (~ $100 billion in 2022) and delivered roughly $123 billion in 2023.
North America
M&A deal value in North America totaled approximately $411.98 billion in Q4, up 10% from Q3 2023 ($375.0B) and 53% from Q4 2022 ($269.0B). Noteworthy Q4 deals included the acquisition of Activision Blizzard (NAS: ATVI) by Microsoft (NAS: MSFT) for $68.1 billion, the acquisition of Hostess Brands (NAS: TWNK) by The J.M. Smucker Co. (NYS: SJM) for $5.6 billion, and the acquisition of Newly Weds Foods by Redwood Holdings through an estimated $4.0 billion LBO. As we discussed in our Q3 Report, North American markets appear to be displaying signs of improvement as easing inflation inspires hope for future interest rate declines.
Consumer Sector
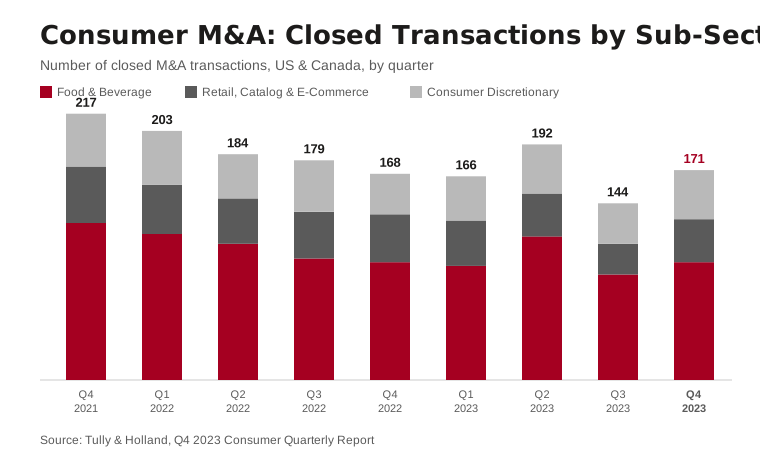
A total of 171 M&A transactions closed in the US and Canada in Q4 2023 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is up approximately 19% from Q3 2023 (144) and 2% from Q4 2022 (168). While the Consumer Sector dealmaking landscape has faced challenges over the past two years, PwC notably predicts “acquisitions will continue to be driven by the need for technology and sustainability capabilities as well as deals that enhance supply chain security or help build resilience, such as expansion in adjacent markets.”
Food & Beverage
A total of 96 M&A transactions closed in the US and Canada in Q4 2023 in the Food & Beverage sector, up approximately 12% from Q3 2023 (86) and flat from Q4 2022 (96). Ongoing buyer interest for key trends such as Clean Label, private label, sustainable/ethical sourcing, and “better for you” ingredients, along with companies’ ability to handle cost changes and pricing pressures, is expected to support M&A activity in this sub-sector.
Retail, Catalog and E-Commerce
A total of 35 M&A transactions closed in the US and Canada in Q4 2023 in the Retail, Catalog and E-Commerce sectors, up approximately 40% from Q3 2023 (25) and down 10% from Q4 2022 (39). Despite in-person shopping continuing to dominate the majority of purchases made in the United States, e-commerce has emerged as a crucial component of company strategies. Embracing an omnichannel approach that seamlessly integrates physical and digital presences, while leveraging disruptive technologies such as artificial intelligence (AI), is anticipated to drive both category growth and acquisition activity.
Consumer Discretionary
A total of 40 M&A transactions closed in the US and Canada in Q4 2023 in the Consumer Discretionary sector, up approximately 21% from Q3 2023 (33) and Q4 2022 (33). With inflation showing signs of moderation, we expect this sub-sector to sustain its momentum from Q4 2023.
As we migrate through Q1 of 2024, valuations seem to have settled into a new normal, we expect to see a continued acceleration of transaction volumes and absolute values in the M&A sector. This is especially likely given that the Fed seems satisfied at the current static posture, with a slight tilt towards potential rate cuts in the coming months. This stabilization of the economic backdrop, along with the resilience of certain sought after themes and trends in sought after targets, should prove a stable base from which to rebound. Specifically, in the consumer sector where we do our work, trends of sustainability, wellness, transparent supply chains, and omnichannel connectivity continue to rise to the forefront of import. Further, as stated in our opening paragraph, sellers considering going to market would be well served to begin that process sooner rather than later. We at Tully & Holland, as we have for over 30 years, remain ready to advise, serve, and advocate on behalf of owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q4 2023 Transactions
- Hostess Brands Inc. (NAS: TWNK), a Kansas-based developer, manufacturer, and distributor of sweet snacks, was acquired by The J.M. Smucker Co. (NYS: SJM) for $5.60 billion on November 7th, 2023.
- Hostess provides sweet baked goods, cookies, bread, and buns that are sold under the Hostess, Voortman, Dolly Madison, Cloverhill, and Big Texas brands.
- With the Hostess acquisition, J.M. Smucker has gained a stronger position in this highly attractive segment with popular brands that consumers love.
- Newly Weds Foods, an Illinois-based producer of food products, was acquired by Redwood Holdings through an estimated $4.00 billion LBO on December 1st, 2023.
- Newly Weds Foods provides a range of offerings including ingredients for raw meat and poultry, food coatings, food safety and functional ingredients, as well as seasoning and sauce products.
- The transaction was supported by approximately $2.43 billion of debt financing.
- Creed Fragrances, a U.K.-based manufacturer of luxury perfumes, was acquired by Kering (PAR: KER) for $3.88 billion on October 17th, 2023.
- The acquisition provides Kering with the required scale, financial foundation, and strategic platform for fostering growth of additional Kering fragrance franchises.
- Alphia, a Utah-based manufacturer of health-focused pet foods and treats, was acquired by PAI Partners through a $1.36 billion LBO on October 2nd, 2023.
- With the support of PAI Partners, the company will accelerate further North American growth, both organically and through acquisitions.
- The transaction was supported by $751.27 million of debt financing.
- The chewing gum business of Mondelez International (NAS: MDLZ) was acquired by Perfetti Van Melle for $1.35 billion on October 2nd, 2023.
- The acquisition complements Perfetti Van Melle’s portfolio of global brands and advances Mondelez’s portfolio reshaping strategy, as it continues striving to deliver 90% of revenue in its core categories of chocolate, biscuits, and baked snacks.
Text reproduced from the report as published by Tully & Holland. Photograph: Dietmar Rabich, CC BY-SA 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →
Consumer Industry Update Q3 2023
Global M&A value slipped just 3% year over year in Q3 2023 while the Fed held still, and deal metrics began to normalize...
Read →
Consumer Industry Update Q2 2023
Global deal value fell hard in Q2 2023, yet the number of deals getting done rose almost everywhere, and consumer volume...
Read →