
Consumer Industry Update Q2 2023
The Recovery Shows Up in Volume First
Global deal value fell hard in Q2 2023, yet the number of deals getting done rose almost everywhere, and consumer volumes turned before the broader market. Our archived quarterly read on the moment the M&A rebound began.

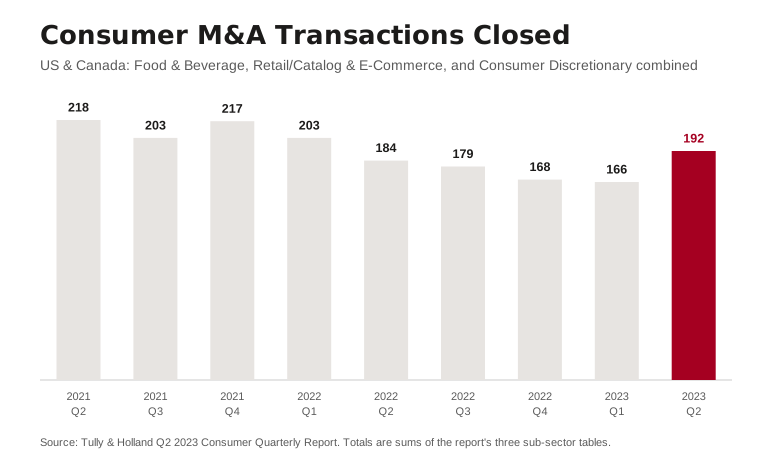
consumer M&A transactions closed in the US and Canada in Q2 2023 across our three tracked sectors, up roughly 16% from Q1.
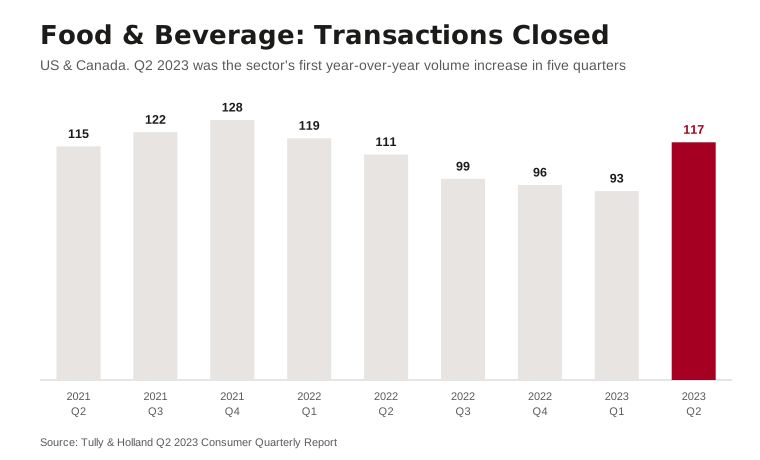
Food & Beverage transactions closed, up 26% from Q1 and the sector's first year-over-year volume increase in five quarters.
global M&A value in Q2 2023, down roughly 36% from $1.14 trillion a year earlier, even as deal counts rose in most geographies.
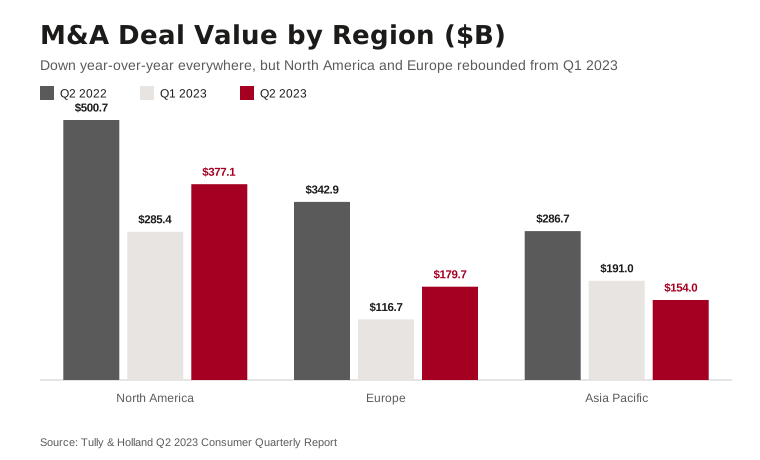
North America deal value, up 32% from Q1 2023 though still 25% below Q2 2022.
median EV/EBITDA on the T&H Consumer M&A Index for disclosed deals above $100 million in revenue, versus 5.15x for the broad market.
the runway to the 2024 US election, the report's case for sellers and buyers to become active now rather than wait.
General Market Commentary
Global M&A activity for Q2 of 2023 declined approximately 36% on a YoY basis from $1.14 trillion (Q2 2022) to $732.82 billion (Q2 2023). Taken on its face, this is obviously a continuation of the negative trends we have been commenting on for the past 18 months. That said, and as delineated in more detail below, there is a fair amount of data to bring about renewed optimism that the M&A markets, both globally and within the United States, are beginning to rebound. More specific, while the total “value” of the deals completed is down significantly on a dollar basis, the actual “volume” of deals completed was up (for most geographies) on a YOY basis. While somewhat incongruous at first blush, it actually stands to reason (and we have certainly seen in past cycles) that the volume of deals completed will be the leading indicator of recovery in the M&A sector. Put another way, while the actions of the Fed, as well as other central banks, have caused a significant rise in the cost of debt over the past 18 months, it has necessitated a resetting/lowering of the multiples paid for acquisitions. As we predicted in our past reports, this “reset” would take time as both the “pricing equations” of acquirers, and the “pricing expectations” of sellers, found a new equilibrium. With the Fed now seemingly much closer to the end of its hawkish rate rises, and with recent Fed raises being more digestible at 25pbs (rather than 75 bps), we feel optimistic that the worst of the M&A downturn is behind us. To take the point even further, given that we are approximately 15 months away from the next U.S. Presidential Election, we anticipate an acceleration in dealmaking activity in the next 9-12 months in order to complete transactions before a typical lag due to political uncertainty kicks in late next summer. To that end, should sellers, or buyers, be balancing when to enter the market for a given transaction, we would advise they become active now.
VC Details & Outlook
Through the first half of 2023, US VC firms completed approximately 8,195 deals with a cumulative value of $85.6 billion, 2 representing a 13% decrease in dealmaking and 41% decrease in deal value compared 2022’s figures (9,421 deals totaling $144.2 billion).3
US VC firms had raised $33.3 billion across 233 funds at the end of Q2,2 representing an approximate 73% YoY decrease in US VC fundraising dollars ($121.5 billion raised across 415 funds at the end of Q2 2022).3
During Q2, sponsors exited approximately 207 US VC-backed companies with a cumulative exit value of $5.5 billion,2 representing an approximate 45% YoY decrease in exit count, and 69% decrease in exit value compared to Q2 2022’s figures (380 companies valued at $18.0 billion).3
PE Details & Outlook
Through the first half of 2023, US PE firms completed approximately 4,338 deals with a cumulative value of $418.3 billion,4 representing an 8% increase in dealmaking and 5% increase in deal value compared to 2022’s figures (4,000 deals totaling $400.0 billion). 5
US PE firms had raised $153.0 billion across 160 funds at the end of Q2,4 representing an approximate 13% YoY decrease in US PE fundraising dollars ($176.0 billion raised across 191 funds at the end of Q2 2022).5
During Q2, sponsors exited approximately 289 US PE-backed companies with a cumulative exit value of $87.3 billion,4 representing an approximate 1% YoY decrease in exit count, and 8% decrease in exit value compared to Q2 2022’s figures (293 companies valued at $94.5 billion).5
Europe
M&A deal value in Europe totaled approximately $179.7 billion in Q2,6 up 54% from Q1 2023 ($116.7B), but down 48% from Q2 2022 ($342.9B). Noteworthy transactions during Q2 included ViaSat's (NAS: VSAT) acquisition of Inmarsat for $7.3 billion, ALD Automotive's (EPA: ALD) acquisition of LeasePlan for $5.4 billion, and Sika Group's (SWX: SIKA) acquisition of MBCC Group for $5.7 billion. As inflation continues to cool in the UK (decreased from 8.7% in May to 7.9% in June),7 deal activity in the region is expected to rise alongside growing investor confidence and reduced expectations of future rate hikes.
Asia Pacific
M&A deal value in Asia totaled approximately $154.0 billion in Q2,6 decreasing 19% from Q1 2023 ($191.0B), and down 46% from Q2 2022 ($286.7B). Of note was the acquisition of Evident (Tokyo), a subsidiary of Olympus (TKS: 7733), by Bain Capital through a $3.1B LBO on April 3rd, 2023. This region’s M&A environment faces challenges stemming from the continuing regulatory crackdown on China’s major tech companies and rising tensions between Beijing and Washington over Ukraine.
North America
M&A deal value in North America totaled approximately $377.1 billion in Q2, up 32% from Q1 2023 ($285.4B), but down 25% from Q2 2022 ($500.7B). Noteworthy Q2 deals included the acquisition of Shaw Communications (TSXV: SJR.A) by Rogers Communications (TSE: RCI.B) for nearly $19.0B, the acquisition of Oak Street Health (NAS: OSH) by CVS Health (NYS: CVS) for $10.6B, and the acquisition of Prometheus Biosciences (NAS: RXDX) by Merck & Co. (NYS: MRK) for $10.8B. Despite widespread uncertainty, the region’s M&A volume should be supported from the anticipated slowdown in the pace of rate hikes and subsequent debt market stability.
Consumer Sector
A total of 192 M&A transactions closed in the US and Canada in Q2 2023 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is up approximately 16% from Q1 2023 (166) and 4% from Q2 2022 (184). Although deal volumes may not reach levels achieved in 2021, PwC notably expects “to see a healthy level of fiscal year 2023 M&A activity in the latter half of the year, as businesses’ focus remains on increased profitability, portfolio diversification, and optionality for consumers.”
Food & Beverage
A total of 117 M&A transactions closed in the US and Canada in Q2 2023 in the Food & Beverage sector, up approximately 26% from Q1 2023 (93) and 5% from Q2 2022 (111). For the first time in five consecutive quarters, Food & Beverage M&A transaction volume increased year-on-year in the 2nd quarter of 2023, returning to levels realized in 2021 and early 2022.
Retail, Catalog and E-Commerce
A total of 35 M&A transactions closed in the US and Canada in Q2 2023 in the Retail, Catalog and E-Commerce sectors, down approximately 5% from Q1 2023 (37) and Q2 2022 (37). This sub-sector remains relatively stable and should continue to enjoy tailwinds as organizations continue leveraging the use of technology and cater to evolving consumer preferences.
Consumer Discretionary
A total of 40 M&A transactions closed in the US and Canada in Q2 2023 in the Consumer Discretionary sector, up approximately 11% from Q1 2023 (36), and Q2 2022 (36). This sub-sector has demonstrated resiliency amidst consumer cost pressures, and we anticipate continued decreases in inflation will support deal volumes in subsequent quarters.
As we migrate through Q3 of 2023, while valuations continue to settle into a new normal, we expect to see a continued acceleration of transaction volumes in the M&A sector. The Fed should soon signal a migration to a status-quo posture, or perhaps even slightly more dovish, given the backdrop of the economy and the historical reticence of the Fed to act (unless it absolutely has to) in a Presidential Election year. This stabilization of the economic backdrop, along with the resilience of certain sought after themes and trends in sought after targets, should prove a stable base from which to rebound. Specifically, in the consumer sector where we do our work, trends of sustainability, wellness, transparent supply chains, and omnichannel connectivity continue to rise to the forefront of import. Further, as stated in our opening paragraph, sellers considering going to market would be well served to begin that process sooner rather than later. We at Tully & Holland, as we have for over 30 years, remain ready to advise, serve, and advocate on behalf of owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q2 2023 Transactions
- Spectrum Plastics Group, a manufacturer of polyethylene bags, films and tubing for food and industrial packaging applications, was acquired by DuPont de Nemours (NYS: DD) for $1.75 billion on May 2nd, 2023.
- The acquisition will complement DuPont’s existing offerings for biopharma and pharma processing, medical devices, and packaging, as well as strengthen its position in fast-growing healthcare markets.
- TravelCenters of America (NAS: TA), an operator of travel centers and standalone restaurants based in Westlake, Ohio, was acquired by BP (LON: BP) on May 15th, 2023, for $1.3 billion.
- The company’s customers include trucking fleets and their drivers, independent truck drivers, highway and local motorists, and casual diners.
- The acquisition marks a milestone for BP’s US-based strategic convenience and mobility business.
- The Company, a division of The J.M. Smucker Co. (NYS: SJM), was acquired by Post Holdings (NYS: POST) for approximately $1.2 billion on April 28th, 2023.
- The divestiture comes on the heels of two others by The J.M. Smucker Co., having sold its private label dry pet food business to Diamond Pet Foods and Natural Balance brand to Nexus Capital Management in 2021.
- Novataste, a subsidiary of International Flavors & Fragrances (NYS: IFF), and producer and supplier of flavor and ingredients created to offer tastier and healthier products to its customers, was acquired by PAI Partners through a $900.0 million LBO on May 31st, 2023.
- In support of the transaction, the company received debt financing in the form of a loan from undisclosed lenders. PAI plans to expand the business in Europe and North America both organically and through acquisitions.
- The Hardware & Home Improvement Division of Spectrum Brands (NYS: SPB), was acquired by Assa Abloy (STO: ASSA B) for $4.3 billion on June 20th, 2023.
- The acquisition advances Assa Abloy's strategy to strengthen its position by adding complementary products to the core business and further accelerating the transition from mechanical to digital solutions.
Text reproduced from the report as published by Tully & Holland. Photograph: Chareinity, CC BY-SA 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q4 2023
Global M&A rose 13% year-over-year in Q4 2023, consumer deal counts jumped 19% from the prior quarter, and quality consu...
Read →
Consumer Industry Update Q3 2023
Global M&A value slipped just 3% year over year in Q3 2023 while the Fed held still, and deal metrics began to normalize...
Read →
Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →