
Consumer Industry Update Q3 2023
The Quarter the Market Found Its Floor
Global M&A value slipped just 3% year over year in Q3 2023 while the Fed held still, and deal metrics began to normalize after a bruising down cycle. Our review of the quarter we told sellers to stop waiting.

global M&A value in Q3 2023, down about 3% year over year, a near-flat reading after steep declines.
consumer transactions closed in the US and Canada across our three tracked verticals, down 25% from Q2 2023.
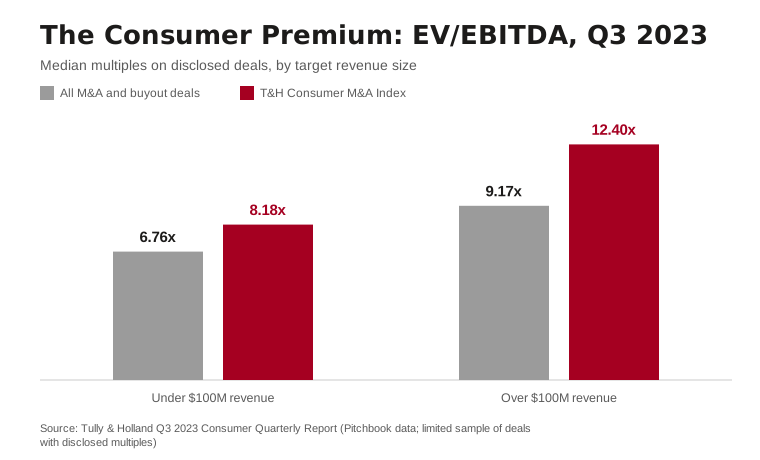
EV/EBITDA on the T&H Consumer M&A Index for targets above $100 million in revenue, versus 9.17x across the broader deal market.
North America deal value, up 46% year over year on the strength of strategic acquirers.
Roark Capital's estimated LBO of Subway, the quarter's headline consumer transaction.
year-over-year jump in US VC exit value (to $35.8 billion), even as exit count slipped 6%.
General Market Commentary
Global M&A activity for Q3 of 2023 declined approximately 3% on a YoY basis from $738.1 billion (Q3 2022) to $719.0 billion (Q3 2023). These relatively “flat” YOY results bode well, in our opinion, for the belief that we are lapping, and improving upon, the worst of the recent down cycle. More specific, whereas last quarter we spoke about the actual “volume” of deals completed being up (for most geographies) on a YOY basis, we can now also say that the enormous decreases in deal “values” we had seen are only slightly down to neutral, dependent on geography and sector. This normalizing of deal value metrics makes even more logical sense, and is in keeping with past cycles, given that the Fed has paused any additional rate hikes since July. It is no coincidence, now or over historical periods, that when the Fed quiets its activity, both buyers and sellers alike have an easier time establishing an equilibrium of expectations around valuation metrics and the attendant cost of debt. With the Fed now seemingly at, or very close to, the end of its hawkish rate rises, we feel optimistic that the worst of the M&A downturn is behind us. To take the point even further, given that we are approximately 12 months away from the next U.S. Presidential Election, we anticipate an acceleration in dealmaking activity in the next 9 months in order to complete transactions before a typical lag due to political uncertainty kicks in late next summer. To that end, should sellers, or buyers, be balancing when to enter the market for a given transaction, we would advise they become active now.
VC Details & Outlook
Through Q3, US VC firms completed approximately 11,935 deals with a cumulative value of $125.9 billion, 2 representing a 0.5% increase in dealmaking, but 35% decrease in deal value compared to 2022 figures (11,871 deals totaling $194.9 billion).3
US VC firms raised $42.7 billion across 344 funds at the end of Q3,2 representing an approximate 72% YoY decrease in US VC fundraising dollars and 42% decrease in participating funds ($150.9 billion raised across 593 funds at the end of Q3 2022).3
During Q3, sponsors exited approximately 284 US VC-backed companies with a cumulative exit value of $35.8 billion,2 representing an approximate 6% YoY decrease in exit count, but 156% increase in exit value compared to Q3 2022 figures (302 companies valued at $14.0 billion).3
PE Details & Outlook
Through Q3, US PE firms completed approximately 6,162 deals with a cumulative value of $611.6 billion,4 representing a 6% decrease in dealmaking and 25% decrease in deal value compared to 2022 figures (6,530 deals totaling $819.2 billion). 5
US PE firms raised $242.0 billion across 258 funds at the end of Q3,4 representing an approximate 6% YoY decrease in US PE fundraising dollars and 13% decrease in participating funds ($258.8 billion raised across 296 funds at the end of Q3 2022).5
During Q3, sponsors exited approximately 275 US PE-backed companies with a cumulative exit value of $44.1 billion,4 representing an approximate 18% YoY decrease in exit count and 50% decrease in exit value compared to Q3 2022 figures (337 companies valued at $89.0 billion).5
Europe
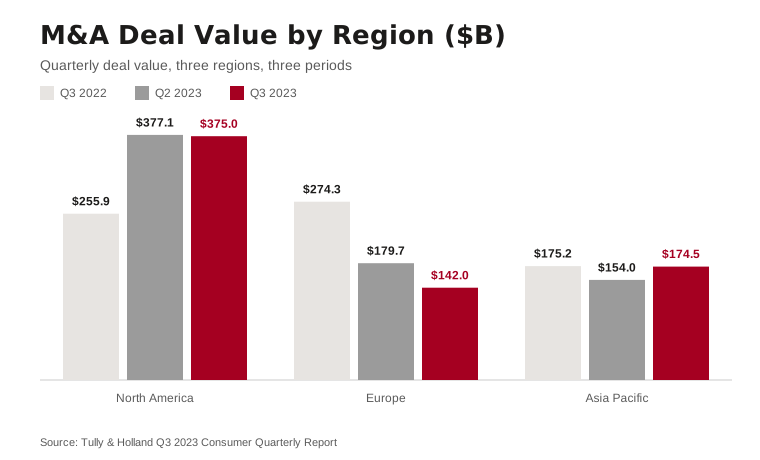
M&A deal value in Europe totaled approximately $142.0 billion in Q3, down 21% from Q2 2023 ($179.7B), and down 48% from Q3 2022 ($274.3B). Noteworthy transactions during Q3 included A.S.R. Nederland’s (AMS: ASRNL) acquisition of Aegon Nederland, a subsidiary of Aegon (AMS: AGN), for $5.32 billion, Concentrix’s (NAS: CNXC) acquisition of Webhelp for $4.80 billion, and Deutsche Börse Group’s (ETR: DB1) acquisition of SimCorp (CSE: SIM) for $4.60 billion. Inflationary pressures coupled with high interest rates continue to dampen M&A volumes in Europe, but the region may show signs of recovery due to recent signals from the ECB and Bank of England suggesting a pause in further interest rate hikes.
Asia Pacific
M&A deal value in Asia totaled approximately $174.5 billion in Q3, increasing 13% from Q2 2023 ($154.0B), and basically flat with Q3 2022 ($175.2B). Of note was the acquisition of Toshiba (Tokyo) (TKS: 6502) by Japan Industrial Partners through a $13.62 billion LBO on September 21st, 2023. Geopolitical tensions and global macroeconomic headwinds have created a fairly large bifurcation between the various Asian markets, causing trends to emerge on a country-specific basis rather than within broader regional contexts.
North America
M&A deal value in North America totaled approximately $375.0 billion in Q3, down 0.6% from Q2 2023 ($377.1B), but up 46% from Q3 2022 ($255.9B). Noteworthy Q3 deals included the acquisition of World Wrestling Entertainment (NYS: WWE) by Endeavor (NYS: EDR) for $21.0 billion, the acquisition of Black Knight (NAS: BKI) by Intercontinental Exchange (NYS: ICE) for $13.1 billion, and the acquisition of Life Storage (NYS: LSI) by Extra Space Storage (NYS: EXR) for $12.7 billion. The Fed’s pause in rate rising since July has set the table for M&A resurgence in North America, where we have already seen demonstrated signs of persistence supported largely by strategic acquisitions, and the attendant synergies they can recognize in the immediate near term.
Consumer Sector
A total of 144 M&A transactions closed in the US and Canada in Q2 2023 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is down approximately 25% from Q2 2023 (192) and 20% from Q3 2022 (179). Despite the decline in volumes in the Consumer Sector, PwC notably mentions “portfolio optimisation remains high on CEOs’ agendas, and this, combined with the need to transact to accelerate strategic transformation, will drive opportunities for value creation through M&A.”
Food & Beverage
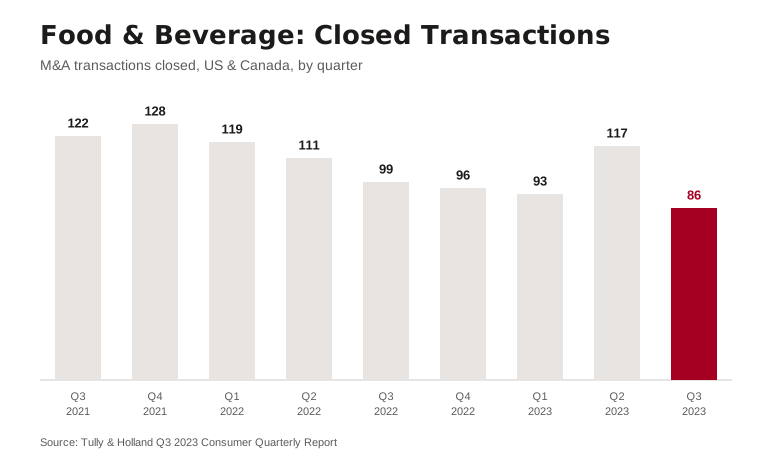
A total of 86 M&A transactions closed in the US and Canada in Q3 2023 in the Food & Beverage sector, down approximately 26% from Q2 2023 (117) and 13% from Q3 2022 (99). Ongoing buyer demand for key trends such as clean-label production, private label, sustainable/ethical sourcing, and plant-based/“better for you” ingredients is expected to support M&A volume in this sub-sector going forward.
Retail, Catalog and E-Commerce
A total of 25 M&A transactions closed in the US and Canada in Q3 2023 in the Retail, Catalog and E-Commerce sectors, down approximately 29% from Q2 2023 (35) and 34% from Q3 2022 (38). Companies focused on omnichannel presence, of which e-commerce is a critical component, not only enjoy significantly higher ROI but also streamline the collection, analysis, and retention of customer data more effectively.
Consumer Discretionary
A total of 33 M&A transactions closed in the US and Canada in Q3 2023 in the Consumer Discretionary sector, down approximately 18% from Q2 2023 (40), and 21% from Q3 2022 (42). This sub-sector has remained relatively stable over the past two years but may face headwinds as ongoing inflationary pressures weigh on households and discretionary spending.
As we migrate through Q4 of 2023, and while valuations continue to settle into a new normal, we expect to see a continued acceleration of transaction volumes in the M&A sector. This is especially likely given that the Fed seems satisfied at the current static posture, and will perhaps become slightly dovish, given the backdrop of the economy and the historical reticence of the Fed to act (unless it absolutely has to) in a Presidential Election year. This stabilization of the economic backdrop, along with the resilience of certain sought after themes and trends in sought after targets, should prove a stable base from which to rebound. Specifically, in the consumer sector where we do our work, trends of sustainability, wellness, transparent supply chains, and omnichannel connectivity continue to rise to the forefront of import. Further, as stated in our opening paragraph, sellers considering going to market would be well served to begin that process sooner rather than later. We at Tully & Holland, as we have for over 30 years, remain ready to advise, serve, and advocate on behalf of owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q3 2023 Transactions
- Alphia, a manufacturer of pet foods and treats intended to offer enriched diets for pets’ health based in Utah, was acquired by PAI Partners for $1.40 billion on September 29th, 2023.
- With the support of PAI Partners, the company will accelerate further North American growth, both organically and through acquisitions.
- The transaction was supported by $750 million of debt financing from BMO Financial Group, Citizens Financial Group, Deutsche Bank, Jefferies Finance, Morgan Stanley, Rabobank Group, Sumitomo Mitsui Trust Bank, The Goldman Sachs Group, and Wells Fargo.
- Qunol, a manufacturer and seller of health supplements intended to provide proper nutrition based in New Jersey, was acquired by Sanofi (PAR: SAN) for $1.40 billion on September 29th, 2023.
- Sanofi officials said this transaction will strengthen Sanofi’s Consumer Healthcare’s vitamin, mineral, and supplements category, one of the largest and fast-growing consumer health categories in the U.S., with a focus on the active ‘healthy aging’ segment.
- Subway, an operator of a global quick-service restaurant chain based in Milford, Connecticut, entered into a definitive agreement to be acquired by Roark Capital Group through an estimated $9.55 billion LBO on August 24th, 2023.
- According to Reuters, Roark prevailed over a rival bidding group led by buyout firms TDR Capital and Sycamore Partners, whose final offer was for $8.75 billion including an earn-out, and $8.25 billion without.
- Kevin’s Natural Foods, a manufacturer and supplier of health-forward food products based in California, was acquired by Mars for $810 million on August 1st, 2023. Mars plans to grow its food business through more potential acquisitions in the near term.
- Kevin’s offers a full line of healthy vacuum-chilled meat and vegetable snacks, as well as a complementary line of sauces and condiments, thereby allowing consumers to cook healthy, restaurant-quality food in minutes.
- Boardriders, a designer, manufacturer, and distributor of apparel and accessories designed for sporting activities, was acquired by Authentic Brands Group, via its financial sponsors BlackRock Private Equity Partners, CVC Capital Partners, General Atlantic, GIC, HPS Investment Partners, Jasper Ridge Partners, Leonard Green Partners, and Lion Capital, through an estimated $1.25 billion LBO on September 1st, 2023.
Text reproduced from the report as published by Tully & Holland. Photograph: Shixart1985, CC BY 2.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →
Consumer Industry Update Q1 2023
Global deal value fell by nearly half in the first quarter of 2023, yet consumer M&A closings in the US and Canada slipp...
Read →
Consumer Industry Update Q4 2023
Global M&A rose 13% year-over-year in Q4 2023, consumer deal counts jumped 19% from the prior quarter, and quality consu...
Read →