
Consumer Industry Update Q2 2024
The Recovery Showed Up in the Deal Count
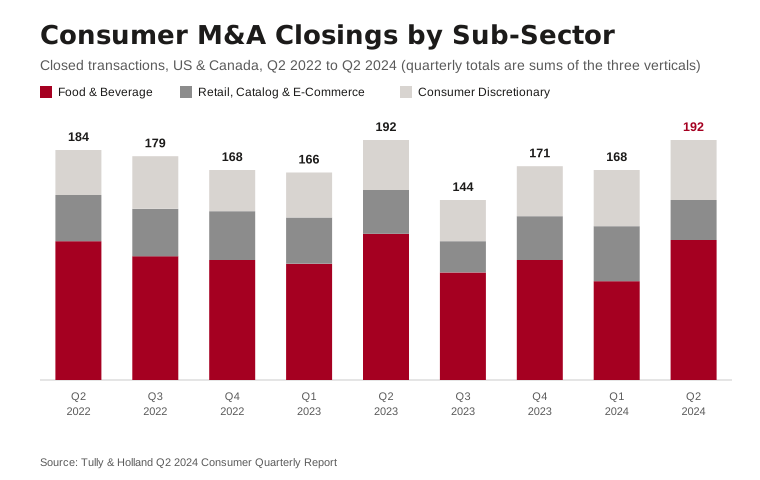
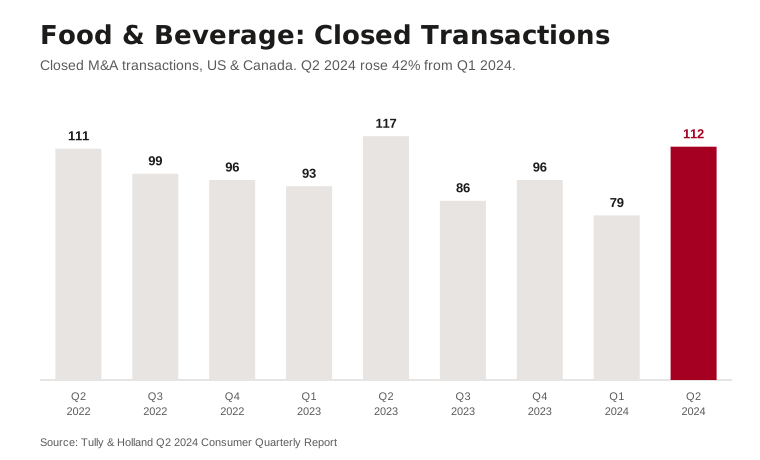
Consumer M&A closings returned to 192 in the second quarter of 2024, up 14% from Q1, with food and beverage transactions jumping 42%. Our Q2 2024 review of a market where rate relief was arriving and consumer businesses were commanding a premium to the broad market.

consumer M&A transactions closed in the US and Canada in Q2 2024 across our three tracked verticals, up 14% from Q1 (168) and even with Q2 2023.
the quarter-over-quarter jump in Food & Beverage closings, from 79 in Q1 to 112 in Q2 2024.
global M&A deal value in Q2 2024, up 3.7% year-over-year and extending more than 12 months of improving activity.
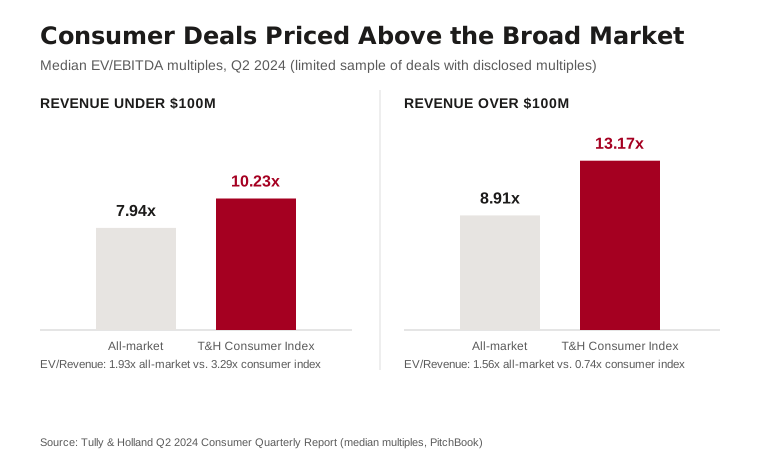
median EV/EBITDA for the T&H Consumer M&A Index (under and over $100M revenue), ahead of the 7.94x and 8.91x all-market medians.
year-over-year growth in Consumer Discretionary closings (48), driven by demand for vitamins, supplements, and wellness products.
the Fed rate cut noted in the report's outlook, making debt cheaper and setting up a more active back half of 2024.
General Market Commentary
Global M&A activity for Q2 of 2024 increased 3.7% on a YoY basis from approximately $741.5 billion (Q2 2023) to $769.0 billion (Q2 2024). We are encouraged by Q2’s increase in transactions and have seen more than 12 months of improving activity trends since the beginning of Q2 2023. The Fed’s recent decision to lower rates by 50 basis points signals an effort to prevent a potential recession caused by earlier rate hikes. The future of the Federal Reserve's neutral rate remains uncertain, particularly regarding the pace of potential rate cuts. Fed Chair Jerome Powell highlighted this ambiguity, noting that the post-pandemic neutral rate is likely significantly higher than it was prior to the pandemic. However, he emphasized, “I just don’t think we know” what the new neutral rate will ultimately be. Although a clearly defined neutral rate is still elusive, lower interest rates have historically encouraged transactions by making debt more affordable. These reduced rates also tend to boost valuations, potentially increasing business owners’ interest in selling. When combined with strong, pent-up demand for M&A activity, we anticipate heightened activity in the private equity space and continued year-over-year quarterly increases. The robust performance of public markets year-to-date, along with several significant M&A announcements in 2024, further supports this outlook. For owners/sellers considering a transaction, we recommend acting soon considering this favorable environment.
VC Details & Outlook
Through the first half of 2024, US VC firms completed approximately 8,247 deals with a cumulative value of $93.4 billion, 2 representing a .6% YoY increase in dealmaking, and a 9% YoY increase in deal value compared to Q2 2023 figures (8,195 deals totaling $85.6 billion).3
US VC firms had raised $37.4 billion across 255 funds at the end of Q2,2 representing an approximate 12% YoY increase in US VC fundraising dollars and a 9% YoY increase in participating funds compared to 2023’s figures ($33.3 billion raised across 233 funds at the end of Q2 2023).3
Through Q2, sponsors exited approximately 634 US VC-backed companies with a cumulative exit value of $49.0 billion,2 representing an approximate 8% YoY increase in exit count and a 308% YoY increase in exit value compared to 2023 figures (588 companies valued at $12.0 billion).3
PE Details & Outlook
Through the first half of 2024, US PE firms completed approximately 4,210 deals with a cumulative value of 325.2 billion,4 representing a 3% decrease in dealmaking, and a 22% YoY decrease in deal value compared to 2023’s figures (4,338 deals totaling $418.3 billion). 5
US PE firms had raised $155.0 billion across 129 funds at the end of Q2,4 representing an approximate 1% YoY increase in US PE fundraising dollars, but a 19% YoY decrease in participating funds compared to 2023’s figures ($153.0 billion raised across 160 funds at the end of Q2 2023).5
Through Q2, sponsors exited approximately 626 US PE-backed companies with a cumulative exit value of $141.4 billion,4 representing no change in exit count, and a 1% YoY increase in exit value compared to 2023 figures (626 companies valued at $139.7 billion).5
Europe
M&A deal value in Europe totaled approximately $255.0 billion in Q2 2024, up 39% from Q1 2024 ($183.0B), and 42% from Q2 2023 ($179.7B). Noteworthy transactions during Q2 included Blackstone (NYS: BX), General Atlantic, Permira, and TCV’s acquisition of Adevinta (OL: ADEA), Hg, Intermediate Capital Group (LON: ICG), and Leonard Green & Partners’ acquisition of IRIS Software Group for $4.0 billion, and Sonoco’s (NYS: SON) acquisition of Eviosys for $3.9 billion. Despite ongoing challenges from inflation, geopolitical tensions, and regulatory hurdles, sectors such as energy, materials, and technology are poised to lead deal activity. The increasing focus on ESG (Environmental, Social and Governance) factors presents both obstacles and growth opportunities for companies aiming to adapt to evolving sustainability standards.
Asia Pacific
M&A deal value in Asia totaled approximately $132.0 billion in Q2 2024,6 flat from Q1 2024 ($132.0B) and down 14% from Q2 2023 ($154.0B). Of note were the acquisitions of Wanda Plaza by Abu Dhabi Investment Group, CICC Capital, PAG, Ares Management (NYS: ARES), and Mubadala Investment Company for $8.32 billion, Withnix by DongKook Pharmaceutical Company (KRX: 086450) for $2.2 billion, and Benefit One (TKS: 2412) by Dai-Ichi Life Insurance (TKS: 8750) for $1.9 billion. Increased regulatory scrutiny and heightened geopolitical tensions, especially between China and the U.S., could impact cross-border M&A activity. Significant interest is concentrated in the technology, healthcare, and consumer sectors, driven by the accelerated digital transformation and pandemic effects that have intensified investments in technology and healthcare.
North America
M&A deal value in North America totaled approximately $340.0 billion in Q2 2024, down 21% from Q1 2024 ($431.8B) and 10% from Q2 2023 ($377.1B). Noteworthy Q2 deals included the acquisitions of Pioneer Natural Resources (NYS: PXD) by Exxon Mobil (NYS: XOM) for $64.5 billion, SRS Distribution by The Home Depot (NYS: HD) for $18.25 billion, and NFP by AON (NYS: AON) for $13.4 billion. The M&A landscape in North America is experiencing renewed optimism, characterized by a strong focus on innovation, sustainability, and strategic growth across key industries, with corporate and private equity deals driving leadership’s pursuit of acquisitions to enhance technology and production capabilities.
Consumer Sector
A total of 192 M&A transactions closed in the US and Canada in Q2 2024 across the Food & Beverage; Retail, Catalog and E-Commerce; and Consumer Discretionary sectors (as defined on page 7). The number of closed M&A transactions in these verticals is up approximately 14% from Q1 2024 (168), while remaining consistent with Q2 2023 levels (192). BCG predicts that private equity firms and large corporations, with ample dry powder, will focus on acquiring capability and technologies that align with their strategic goals, while simultaneously pursing transformational deals to future-proof business models, enhance resilience, and address capital constraints.
Food & Beverage
A total of 112 M&A transactions closed in the US and Canada in Q2 2024 in the Food & Beverage sector, up approximately 42% from Q1 2024 (79), but down 4% from Q2 2023 (117). Looking ahead, we expect M&A activity in this sub-sector to maintain its momentum, driven by growing health trends such as functional beverages, kombucha, and puffed baked snacks.
Retail, Catalog and E-Commerce
A total of 32 M&A transactions closed in the US and Canada in Q2 2024 in the Retail, Catalog and E-Commerce sectors, down approximately 27% from Q1 2024 (44) and 9% from Q2 2023 (35). Despite these trends, retailers are increasingly using M&A to diversify beyond traditional operations, focusing on growth areas such as third-party marketplaces, business-to-business (B2B) services, and monetizing logistics and customer data.
Consumer Discretionary
A total of 48 M&A transactions closed in the US and Canada in Q2 2024 in the Consumer Discretionary sector, up approximately 7% from Q1 2024 (45) and 20% from Q2 2023 (40). M&A volumes in this sub-sector remain strong, with sustained activity driven by growing demand for health-conscious products. Investors are particularly focused on vitamins, supplements, and alternative health solutions, as more consumers turn to affordable, over-the-counter healthcare options that support preventative care and wellness.
As we progress through Q3 of 2024, rates are significantly lower than at the beginning of the quarter (although elevated on a recent historical basis). This supportive environment is slightly offset by the overhang of the upcoming presidential election and lack of clarity as to future rate cuts. However, we expect to see a continued acceleration of transaction volumes and absolute values in the M&A sector. The continued health of the US economy, along with the resilience of certain sought after themes and trends in high-demand targets, should prove a stable base from which to accelerate M&A. In the consumer sector where we operate, trends such as sustainability, wellness, private label, and omnichannel connectivity are becoming increasingly important. As mentioned in our opening paragraph, sellers considering entering the market would benefit from starting the process sooner rather than later. For over 30 years, Tully & Holland has been dedicated to advising, serving, and advocating for owners, entrepreneurs, strategic acquirers, and private equity firms across the consumer spectrum. We look forward to working with you.
Notable Q2 2024 Transactions
- SRS Distribution, a Texas-based distributor of residential roofing materials, was acquired by The Home Depot (NYS: HD) for $18.25 billion on June 18th, 2024.
- The combination of the two businesses will accelerate Home Depot’s growth with the residential professional customer. SRS complements The Home Depot’s capabilities and enables the company to better serve the complex purchase occasion, while also establishing The Home Depot as a leading specialty trade distributor across multiple verticals.
- Subway, a Connecticut-based operator of a quick-service restaurant chain intended to serve globally, was acquired by Roark Capital Group through an estimated $9.55 billion LBO on April 30th.
- In announcing the deal’s closing, Subway said the acquisition came on the heels of three years of sales growth and positive net restaurant growth for the first time since 2016.
- The transaction was supported by $5 billion of debt financing.
- Tropical Smoothie Cafe, a Georgia-based operator of a restaurant chain intended to serve fresh food and smoothies, was acquired by Blackstone (NYS: BX) through an estimated $2.0 billion LBO on June 10th, 2024. Tropical Smoothie Cafe began operating as a single location on a beach in Destin, Florida in 1997, and has grown into a nationally recognized brand with more than 1,400 locations in 44 states today.
- The acquisition helps position the company for continued success and innovation for the benefit of its guests and franchisees.
- Hibbett Inc. (NAS: HIBB), an Alabama-based retailer of sporting goods, was acquired by JD Sports Fashion (LON: JD.) for $1.1 billion on April 25th, 2024.
- As JD Sports looks to grow its presence across the south-eastern U.S., it confirmed that it will pay $87.50 per Hibbett share in cash, representing a premium of about 20% the U.S. firm’s last closing price.
- Lucas Meyer Cosmetics, Quebec-based manufacturer of ingredients intended for the cosmetics and personal care industry and subsidiary of International Flavors & Fragrances (NYS: IFF), was acquired by Clariant International for $810 million on April 2nd, 2024.
- The acquisition expands Clariant International’s reach into the high-value cosmetic ingredient space, based on customer-driven innovation and natural solutions.
Text reproduced from the report as published by Tully & Holland. Photograph: Alabama Extension, CC0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q3 2024
Consumer M&A closed 219 transactions in Q3 2024, up 52% from a year earlier, as a first Fed rate cut and post-election o...
Read →
Consumer Industry Update Q1 2024
Global M&A rose 31% from a year earlier, North America led the recovery, and consumer deal counts held steady while the ...
Read →
Consumer Industry Update Q1 2023
Global deal value fell by nearly half in the first quarter of 2023, yet consumer M&A closings in the US and Canada slipp...
Read →