
Consumer Industry Update Q2 2025
More Deals, Not Bigger Ones
Global deal count climbed 18.6% year-over-year while headline value slipped, and food and beverage turned in its busiest quarter in the nine we track. Our Q2 2025 review of a consumer M&A market that rewarded brands with real momentum.

global M&A deal value in Q2 2025, down a slight 4.7% from Q1 but up 13.4% year-over-year.
estimated global transactions, up 18.6% year-over-year; the recovery showed up in volume before value.
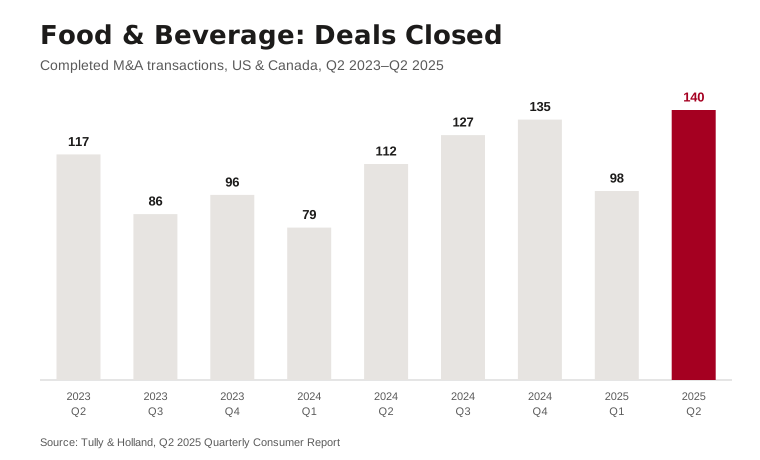
food and beverage transactions closed in the US and Canada, up 42.9% quarter-over-quarter and the most in the nine quarters we track.
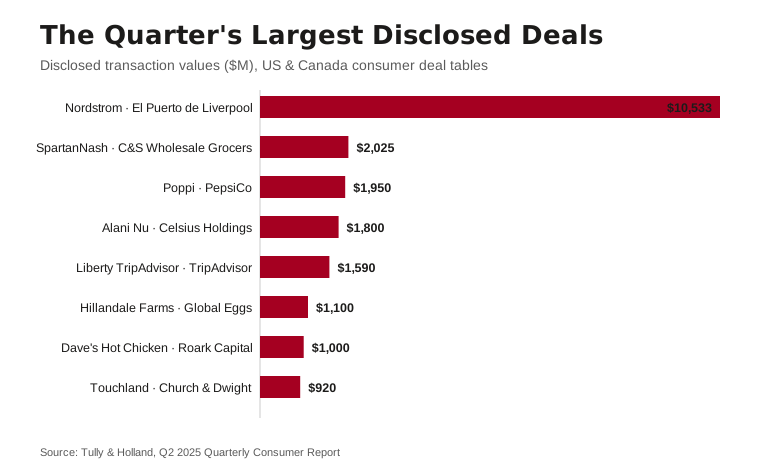
Nordstrom's take-private by the Nordstrom family and El Puerto de Liverpool, the quarter's largest disclosed consumer deal.
EBITDA multiple on C&S Wholesale Grocers' $2.03 billion acquisition of SpartanNash, struck at a 52.5% premium.
what e.l.f. Beauty agreed to pay for rhode, the quarter's clearest price tag on brand momentum.
General Market Commentary
The global M&A market demonstrated resilience through the first half of 2025 despite persistent macroeconomic headwinds. In Q2 2025, global deal value came in at $988 billion, which is a slight 4.7% QoQ decrease but a 13.4% increase on a YoY basis. Deal count is estimated at 12,605, which represents an increase of 3.4% QoQ and 18.6% YoY. Key themes included strategic cross-border consolidation as well as portfolio and sector realignment. North American deal value was supported by several large-cap deals and is poised to further ramp up in the second half of the year, while macroeconomic factors and valuations drove up deal counts in Europe.
Financial Sponsors
PE Details & Outlook
Private equity activity cooled down compared to Q1 2025 but posted YoY increases in both deal volume and deal value. Add-on transactions, including several megadeals, were a meaningful contributor as sponsors pursued scale. Notably, in Food & Beverage, Hometown Food Company, backed by Brynwood Partners, acquired the packaged food company Chef Boyardee as an add-on for $600 million.
Take-private transactions slowed down during the quarter due to soaring public equity valuations, but pockets of opportunity in the Consumer sector were highlighted by 3G Capital’s acquisition of Skechers, C&S Wholesale Grocers’ acquisition of SpartanNash, and the completion of Nordstrom’s acquisition by members of the Nordstrom family and Mexican retailer El Puerto de Liverpool.
Looking ahead, major factors expected to affect PE activity throughout the remainder of 2025 include further trade policy developments, changes in the Fed policy rate, and credit quality across business and consumer loans.
VC Details & Outlook
VC deal activity slowed down 24.8% QoQ, with deal value of $69.9 billion across 4,001 deals. This still marks a 40% YoY increase in deal value and a 5% increase in deal volume, indicating sustained growth, albeit below last quarter’s levels.
A slowdown in Artificial Intelligence (AI) and Machine Learning (ML) investment contributed to the lower aggregate deal value for the quarter. 58% of all VC capital went to AI and ML companies in Q2, down from 71% in Q1 2025. The largest deal in the AI/ML space was Meta Platforms’ $14.3 billion investment in Scale AI, well below OpenAI’s $40 billion round completed in Q1.
IPO activity picked up slightly, with 15 public listings compared to last quarter’s 12. After considering a delay, Hinge Health successfully completed its public listing on May 22. Three FinTech IPOs boosted activity, with Chime, Circle, and Slide Insurance all going public in June 2025. Figma’s July 31 IPO created further momentum and bolstered a positive outlook on market activity throughout H2 2025.
Key Regions
North America
In North America, deal value in Q2 was $596.8 billion across an estimated 4,814 transactions. Both deal value and deal count were slightly down QoQ but showed double-digit increases compared to Q2 2024 of 31.3% and 10.7%, respectively. Strategic acquirers were more active than financial sponsors during the quarter, often driven by opportunities for improving scale through consolidation. Dealmaking overall was more muted in April, likely on the back of tariff negotiations, but picked up in May and June. This upward trend continues into Q3 2025 with a notable spike in M&A activity across sectors as some policy and trade uncertainties begin to ease.
In Q2, the Top 10 deals accounted for 26% of deal value, continuing a trend from the previous quarter. While the two largest deals were in the IT sector, overall sector representation in the megadeal segment was diverse, including Technology, Financial Services, B2B, B2C, Energy, and Healthcare. The portion of Top 10 deals backed by private equity players fell to 30%, down from 50% in Q1 2025 and in Q2 2024, likely reflecting a need to exit aged holdings as opposed to adding to portfolios.
Europe
European M&A activity remained stable QoQ in Q2 2025, with deal value of $256.3 billion across an estimated 5,205 transactions. A widening valuation gap between US and European companies as well as diverging central bank policies have been supporting European deal counts in the last couple of years. A notable example is DoorDash’s acquisition of Deliveroo for $3.8 billion announced on May 6.
Asia Pacific
Countries in the region are strongly affected by the changing geopolitical landscape, which has prompted increases in deal activity as companies seek to innovate and diversify their revenue streams. Intra-regional deals are on the rise, but more notably, investment from the region into the Americas has doubled on a YoY basis in H1 2025, highlighting the persistent attractiveness of American, and specifically US-based, assets to foreign buyers.
Consumer Sector
The global consumer sector is sensitive to tariff uncertainty, which has prompted increased caution from corporate and financial buyers alike. Global deal value for the quarter was $134.8 billion across 2,385 transactions, representing QoQ declines. Footwear was a notable pocket of increased activity, with 3G Capital’s $9.4 billion take-private acquisition of Skechers and Dick’s Sporting Goods’ $5.2 billion acquisition of Foot Locker.
Food & Beverage
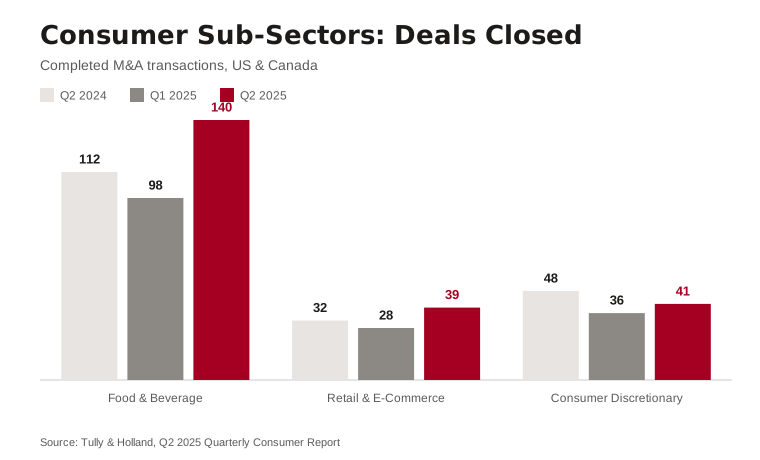
Food & Beverage M&A activity enjoyed a strong quarter, with 140 completed deals, up 25.0% YoY and 42.9% QoQ. Major themes in Q2 2025 included consolidation trends among food distributors and beverage producers, continued diversification into clean-label, plant-based, and better-for-you categories through acquisitions, selective divestitures of non-core business lines, and renewed pursuit of international expansion opportunities.
The quarter’s largest transaction in the sub-sector was C&S Wholesale Grocers’ acquisition of SpartanNash for $2.03 billion, which will combine and streamline the two companies’ complementary food distribution networks. Another recent megadeal, Global Eggs’ acquisition of Hillandale Farms for $1.1 billion, is a strategic step in the acquirer’s international expansion plan. Similarly, Marubeni’s acquisition of Bubbies Homemade Ice Cream & Desserts marks the Japanese conglomerate’s entry into the US ice cream industry. High Liner Foods’ $42 million acquisition of the frozen breaded and battered seafood brands Mrs. Paul’s and Van de Kamp’s from Conagra Brands was a key transaction in the seafood category and a strategic milestone for High Liner Foods, who had been co-manufacturing the brands‘ products for the previous owner.
The push to secure presence in the plant-based, clean-label, and better-for-you categories can be seen across market segments. Examples include Hershey’s (NYSE: HSY) purchase of its joint venture with Irish protein bar company Fulfil Nutrition; Danone’s (PAR: BN) acquisition of US plant-based nutrition company Kate Farms; and Canadian Dare Foods’ acquisition of better-for-you snack manufacturer Mary’s Gone Crackers through its US subsidiary, Rosseau Incorporated. In a niche deal, Michigan-based Birmingham Chocolate acquired Macalat, a North Carolina–based organic, sugar-free dark chocolate brand.
More recently, on July 21, 2025, Vilore Foods Company announced the acquisition of Tia Lupita, a popular Mexican packaged foods brand. The deal complements Vilore Foods’ portfolio of Hispanic staples by adding a culturally authentic, clean-label brand with a distinctive taste profile. This reflects the broader trend of established players expanding into the better-for-you category through strategic acquisitions, while empowering emerging brands with the scale and distribution needed to accelerate growth.
On July 22, Generous Brands, backed by Butterfly Equity, announced the acquisition of kombucha maker Health-Ade for $500 million. The move will expand Generous Brands’ portfolio to four premium beverage brands and marks the company’s entrance into the increasingly popular kombucha category. Find out more in Tully & Holland’s recent Kombucha Industry Update.
Looking ahead, changing consumer preferences and ever-increasing demand for health-conscious products and responsible, sustainable supply chains are likely to continue driving deal activity as companies strive to adjust their positioning.
Retail & E-Commerce
Retail and E-Commerce deal volume increased to 39 transactions in Q2 2025, up 21.9% YoY and 39.3% compared to the previous quarter. The largest deal in the sub-sector was Nordstrom’s $10.5 billion acquisition by the Nordstrom family and Mexican retailer El Puerto de Liverpool, reflecting the continued importance of omnichannel presence in retail.
Another key transaction was Franchise Group’s corporate divestiture of The Vitamin Shoppe, a leading retailer of vitamins and nutritional supplements. The Vitamin Shoppe was acquired by Kingswood Capital Management and Performance Investment Partners for $193.5 million in a buyout transaction completed on April 21, 2025. The deal reflects private equity interest in specialty retail, where there is room for growth and consolidation, while also playing into the broader health and wellness theme seen across the Consumer sector.
Digital tools and platforms targeting various parts of the e-commerce ecosystem were also attractive acquisition targets during Q2, as evidenced by transactions such as PMG’s acquisition of Momentum Commerce, which seeks to fully integrate the two companies’ operations, and the sale of Lucky Labs to PE-backed Spins, the leading provider of data, analytics, and omnichannel activation solutions for the natural products industry.
Going forward, continued revision of strategic portfolios and consolidation opportunities across traditional retail as well as e-commerce and related technology will likely remain key drivers of deal activity in Retail & E-Commerce.
Consumer Discretionary
Transaction volume in the Consumer Discretionary sub-sector decreased 14.6% YoY, with 41 deals completed in Q2 2025. On a QoQ basis, this represents a 13.9% increase. Most of this quarter’s activity was concentrated in a few categories, notably beauty, wellness, and personal care as well as home décor and furnishings.
In the beauty, wellness, and personal care category, strong brand equity remained an attractive feature to buyers. On May 28, e.l.f. Beauty announced the $1 billion acquisition of Hailey Bieber’s rhode, a founder-led, rapidly growing, skincare-focused brand that will complement e.l.f. Beauty’s existing portfolio. Further, Church & Dwight’s $880 million acquisition of trendy hand sanitizer brand Touchland and the sale of Freck Beauty, the company behind the viral freckle pen, showcase opportunities to capitalize on social media momentum. On June 23, Unilever announced an agreement to buy men’s personal care brand Dr. Squatch, whose growth has similarly been boosted by viral social media status. Going forward, consumers are likely to shift their focus to functionality and price, raising the bar for product quality in a fairly saturated, yet still growing, market.
Across categories, companies with strong brands bringing functional products to market are poised to continue to be attractive acquisition targets throughout the remainder of the year.
Tully & Holland remains committed to guiding entrepreneurs, family-owned businesses, and financial sponsors through dynamic market cycles. We look forward to helping our clients capitalize on these evolving opportunities in 2025 and beyond.
Notable Q2 2025 Transactions
- Arizona-based Bubbies Homemade Ice Cream & Desserts, Inc. was acquired by Japanese conglomerate Marubeni on June 30, 2025.
- The acquisition marks Marubeni’s entry into the US ice cream manufacturing business. Marubeni aims to leverage the knowledge and expertise gained from its food manufacturing and distribution businesses in Japan and the ASEAN region to further expand the scale of Bubbies’ business and improve profitability.
- SpartanNash (Nasdaq: SPTN) was acquired by C&S Wholesale Grocers for $2.03 billion in a transaction announced on June 23, 2025.
- The transaction price represents a 52.5% premium over SpartanNash's closing price on June 20, 2025, of $17.64. The strategic rationale for the deal is improved efficiency and scale to be achieved by integrating the two companies’ complementary food distribution networks.
- Hillandale Farms, a subsidiary of Cal-Maine Foods (NAS: CALM), was acquired by Global Eggs, a Luxembourg holding company led by Brazilian entrepreneur Ricardo Faria for $1.1 billion on May 12, 2025.
- The deal follows Global Eggs’ acquisition of Hevo Group, the second-largest egg producer in Spain, in November 2024 and is a strategic step in the company’s international expansion efforts.
- The Wine Group has acquired several popular, premium and ultra-premium wine brands from Constellation Brands, Inc.: Cook’s, J. Rogét, Meiomi, Robert Mondavi Private Selection, SIMI, and Woodbridge in a transaction announced on June 2, 2025.
- The acquisition increases TWG’s premium and ultra-premium offerings and brings three new facilities alongside approximately 6,600 owned and leased vineyard acres throughout California.
- Church & Dwight Co., Inc. (NYSE: CHD) announced the acquisition of hand sanitizer brand Touchland on May 12, 2025, for a total purchase price of up to $880 million.
- Through this acquisition, Church & Dwight will augment its portfolio of market leading personal care brands and accelerate Touchland’s growth by leveraging existing scale and capabilities.
- On May 28, 2025, e.l.f. Beauty (NYSE: ELF) signed a definitive agreement to acquire rhode, Hailey Bieber’s fast-growing, multi-category lifestyle beauty brand known for its high-performance skincare products.
- The $1 billion deal diversifies e.l.f. Beauty’s existing portfolio and underscores the two brands’ shared focus on disruption and product innovation, setting the stage for transformative global expansion.
Text reproduced from the report as published by Tully & Holland. Photograph: USDAgov, Public domain, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q1 2025
Consumer M&A opened 2025 at an estimated $162 billion in global value, food and beverage deal counts jumped 24.1%, and P...
Read →
Consumer Industry Update Q4 2024
Global consumer deal value climbed 44.2% in 2024, the sector's best showing since 2021, and the fourth quarter was the b...
Read →
Consumer Industry Update Q4 2025
Global M&A closed 2025 at nearly $5 trillion, the strongest year for dealmaking on record, and the fourth quarter set a ...
Read →