
Consumer Industry Update Q1 2025
A Running Start Into an Uncertain Year
Consumer M&A opened 2025 at an estimated $162 billion in global value, food and beverage deal counts jumped 24.1%, and PepsiCo paid up twice for better-for-you brands, all while new tariffs gathered on the horizon. Our review of a quarter that kept moving as the forecast darkened.

global consumer (B2C) M&A value in Q1 2025 across an estimated 2,299 deals, up 9.4% in value and 2.8% in volume year-over-year.
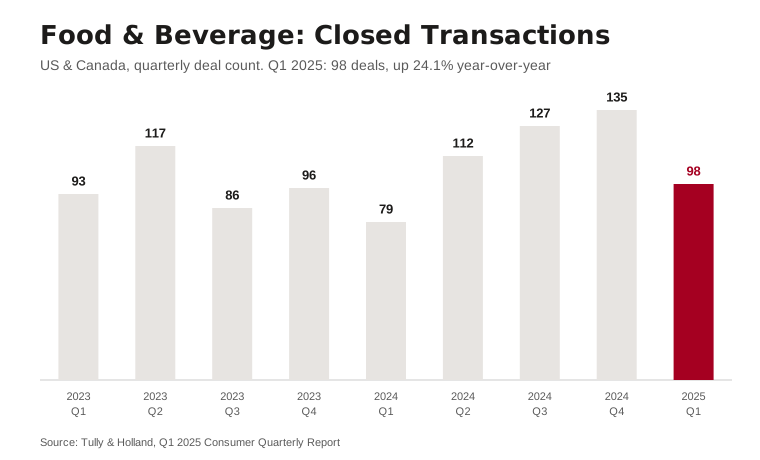
food and beverage transactions closed in the US and Canada, up 24.1% from Q1 2024 and the third straight quarter of year-over-year growth.
Sycamore Partners' take-private of Walgreens Boots Alliance, the largest PE-backed take-private since the global financial crisis.
PepsiCo's acquisition of prebiotic soda maker Poppi, the quarter's marquee functional-beverage deal.
the median North American EV/EBITDA multiple, holding steady at a normalized level relative to pre-pandemic years.
share of Q1 US venture capital that went to AI and machine learning companies, a measure of how narrow risk appetite had become.
General Market Commentary
The global M&A market maintained strong momentum in early 2025, buoyed by robust dry powder, improved financing conditions, and pockets of optimism despite rising macroeconomic headwinds. In North America, deal value reached $259.7 billion across an estimated 2,263 transactions in Q1, reflecting a 24.6% increase in value and an 11.8% increase in deal count year-over-year. While optimism persisted across sponsors and strategics, geopolitical volatility – particularly around new tariffs – and concerns about consumer credit quality began to weigh on sentiment.
VC Details & Outlook
On the venture side, activity remained concentrated but elevated. U.S. VC deal value rose to $91.5 billion in Q1 across 3,990 deals, up 18.5% QoQ and supported by blockbuster AI transactions such as OpenAI’s $40 billion round and Anthropic’s dual financings totaling $4.5 billion.
Notably, 71% of all VC capital in Q1 went to AI and ML companies, reflecting an increasingly narrow pool of favored investment themes.
However, IPO markets remained soft, with only 12 public listings during the quarter, and Klarna and Hinge Health among those delaying IPO plans amid heightened volatility
PE Details & Outlook
Private equity activity continued at a solid pace, highlighted by Sycamore Partners' $23.7 billion acquisition of Walgreens Boots Alliance, the largest PE-backed take-private since the global financial crisis.
Overall, consumer sector M&A reached an estimated 2,299 B2C deals globally in Q1, totaling $162 billion in value.
This performance, while resilient, occurred against a backdrop of looming tariff costs, which are expected to filter down to consumers and compress margins in the near term.
Europe
In Europe, M&A cooled from Q4 2024 highs but maintained a solid trajectory. Deal count increased 17.5% YoY and value climbed 29.2%, bolstered by headline transactions such as ADNOC’s €14.7 billion acquisition of Covestro.
Asia Pacific
Asia-Pacific saw bifurcation – Japan and India remained active, while U.S.-China tensions dampened cross-border dealmaking. Southeast Asia gained attention for data center and healthcare investments amid regional digitalization trends
North America
North American M&A activity totaled $613.8 billion across 4,934 deals in Q1 2025, representing a 10.3% year-over-year increase in value despite a 1.9% dip in deal count. The quarter was led by a surge in large-scale transactions, including Alphabet’s $32 billion acquisition of cybersecurity firm Wiz and the $33 billion merger of social media platform X with xAI, underscoring continued appetite for technology and AI-linked assets.
Private equity remained active, accounting for half of the top 10 deals by value. Sectors such as IT, energy, and healthcare saw the most consistent activity, while tariff and recession concerns caused mid-quarter caution and could temper future dealmaking. Notably, the median EV/EBITDA multiple in North America held steady at 9.6x, reflecting a normalized valuation environment relative to pre-pandemic levels.
Despite growing policy and trade uncertainty under the new U.S. administration, improved credit markets, reduced regulatory pressure, and an open lending environment supported resilient deal flow across mid- and large-cap segments.
Consumer Sector
The global consumer sector delivered another strong quarter, with Q1 2025 B2C M&A activity totaling $162 billion across 2,299 transactions. This represents a 9.4% increase in value and a 2.8% increase in volume over Q1 2024, supported by significant consolidation in subcategories like food delivery, beauty, and fitness.
Food & Beverage
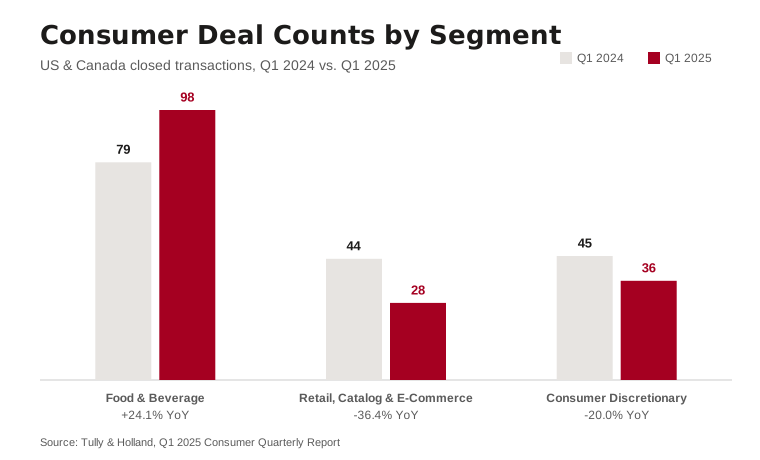
Food & Beverage M&A remained robust into Q1 2025 following a strong close to 2024, when 98 deals were recorded – a 24.1% year-over-year increase from Q1 2024. This sector continued to benefit from durable consumer demand for health-conscious, functional, and plant-based products. Q1 activity reflected sustained strategic and PE interest in vertically integrated platforms, private-label manufacturers, and better-for-you snack brands.
PepsiCo’s $1.7 billion acquisition of prebiotic soda maker, Poppi, exemplifies this trend, reinforcing the shift toward functional beverages with wellness-oriented positioning. Similarly, Hershey’s acquisition of Sour Strips aims to broaden its appeal among younger consumers and expand its snacking occasions portfolio.
Looking ahead, investors are likely to continue targeting brands with clear health credentials, efficient supply chains, and scalable production – particularly as tariffs raise input costs and favor domestic sourcing strategies.
Retail, Catalog and E-Commerce
Retail and e-commerce deal volume declined to 28 transactions in Q1 2025, down 36.4% YoY, yet the period was marked by landmark deals. Notably, Tempur Sealy announced its $4 billion purchase of Mattress Firm, reflecting a trend of companies’ seeking to strengthen their omnichannels.
Buyers remain focused on DTC brands with strong communities, AI-powered personalization tech, and omnichannel enablers such as checkout optimization platforms. Other themes include the consolidation of specialty retail (e.g., premium beauty and curated marketplaces) and PE-led rollups in fragmented segments.
Although tariffs could challenge import-reliant retailers, interest remains high in businesses with resilient supply chains, loyal customer bases, and differentiated CX models.
Consumer Discretionary
The global consumer sector delivered another strong quarter, with Q1 2025 B2C M&A activity totaling $162 billion across 2,299 transactions. This represents a 9.4% increase in value and a 2.8% increase in volume over Q1 2024, supported by significant consolidation in subcategories like food delivery, beauty, and fitness.
As mentioned above, Key transactions included Prosus’ €4.1 billion acquisition of Just Eat Takeaway.com and Sycamore Partners’ $23.7 billion take-private of Walgreens Boots Alliance – the largest PE-backed healthcare retail deal since the financial crisis. Buyers continue to target assets aligned with consumer health, convenience, and digitization trends, including functional foods, pet wellness, and tech-enabled retail.
Private equity’s role in B2C remained dominant, driven by buy-and-build platforms and carveouts of non-core assets. Deal momentum, however, may face headwinds from shifting consumer spending, input cost inflation, and rising import tariffs – especially in discretionary categories.
Nonetheless, strong brand equity, scalable digital infrastructure, and margin resilience remain key investment themes as sponsors and strategics seek long-term growth in a recalibrated macroeconomic environment.
Tully & Holland remains committed to guiding entrepreneurs, family-owned businesses, and financial sponsors through dynamic market cycles. We look forward to helping our clients capitalize on these evolving opportunities in 2025 and beyond.
Notable Q1 2025 Transactions
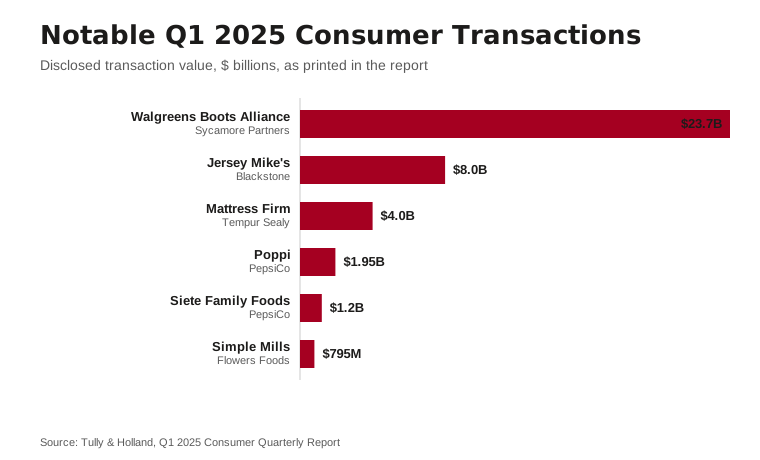
- Poppi, a Texas-based producer of a healthy alternative to traditional soda, was acquired by PepsiCo for $1.95 Billion, with the initial transaction announced on March 17, 2025.
- This acquisition enhances PepsiCo’s portfolio and scale in the functional beverage category, aligning with increased demand for gut health focused and better-for-you drink options.
- Walgreens Boots Alliance (NASDAQ: WBA), an Illinois-based pharmacy retailer, was acquired by Sycamore Partners in a transaction announced on March 6, 2025.
- The acquisition broadens Sycamore Partners’ footprint in the retail and health services space, while leveraging Walgreens Boot Alliance’s established position within the retail and consumer services market. The transaction was valued at $23.7 billion.
- Mattress Firm, a Texas-based mattress store chain, was acquired by Tempur Sealy in a $4 billion cash-and-stock deal in a transaction announced on February 5, 2025.
- The acquisition aligns with Tempur Sealy’s goal to accelerate their U.S. omni-channel strategy. Tempur Sealy now has 3,000 retail stores, 30 e-commerce platforms, and 75 manufacturing and R&D facilities. The deal also included the transfer of 8,100 employees to Tempur Sealy.
- Jersey Mike’s, a New Jersey based sandwich company, was acquired by Blackstone on January 16, 2025.
- Blackstone’s partnership gives Jersey Mike’s the necessary capital to accelerate expansion across the U.S. as well as internationally. Jersey Mike’s also plans to continue its investment in technology and digital transformation.
- Flowers Foods Inc., announced on January 8, 2025, that it has entered an agreement to acquire Simple Mills in a $795 million all-cash.
- The acquisition of Simple Mills expands Flowers Foods existing portfolio beyond traditional baked foods, diversifying into the better-for-you snacking category. Simple Mills also brings significant brand exposure with products available nationwide in more than 30,000 nationwide stores.
Text reproduced from the report as published by Tully & Holland. Photograph: Wilfredor, CC BY-SA 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q2 2025
Global deal count climbed 18.6% year-over-year while headline value slipped, and food and beverage turned in its busiest...
Read →
Consumer Industry Update Q3 2025
Global deal value jumped 35.1% year over year to $1.1 trillion, the strongest quarter since late 2021, while consumer de...
Read →
Consumer Industry Update Q4 2024
Global consumer deal value climbed 44.2% in 2024, the sector's best showing since 2021, and the fourth quarter was the b...
Read →