
Consumer Industry Update Q1 2026
Records at the Top, Discipline Everywhere Else
Global deal value set an all-time record while capital crowded into a handful of megadeals, and healthcare capital invested climbed to $145.8 billion. Our Q1 2026 review of a market rewarding scale, focus, and recurring revenue.

estimated global M&A value in Q1 2026, up 8.8% quarter-over-quarter and 50.6% year-over-year, a record.
the SpaceX and xAI transaction, the largest deal on record; even excluding it, the top 10 North American deals totaled $268.5 billion.
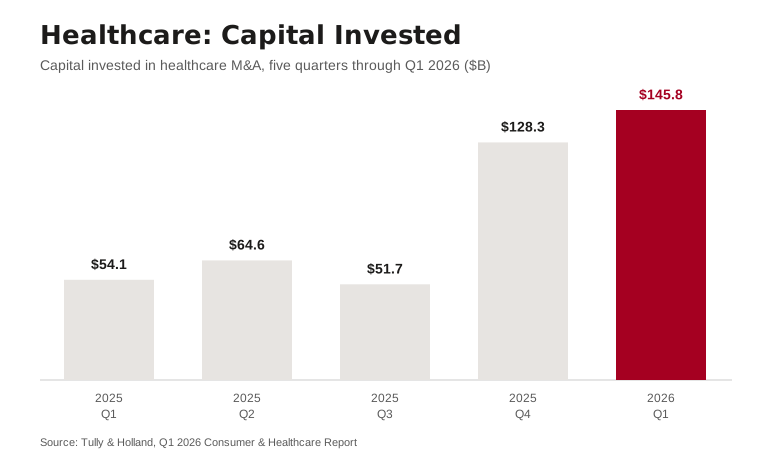
capital invested across 611 healthcare deals, up from $128.3 billion in Q4 2025 and $54.1 billion a year earlier.
the McCormick combination with Unilever's food business, capping a nearly five-year high in Food & Beverage activity.
share of Q1 Food & Beverage deals done by strategic buyers, as Big Food separations dominated the headlines.
share of Q1 venture deal value that was AI-related, with the five largest financings taking roughly 73% of all capital.
General Market Commentary
Global M&A activity reached record levels in Q1 2026 despite geopolitical uncertainty, AI disruption concerns, and rising rate expectations. Total deal value climbed to an estimated $1.6 trillion, increasing 8.8% QoQ and 50.6% YoY. Deal count reached an estimated 13,877 transactions, up 18.3% YoY and matching the record pace set in Q4 2025. Activity was driven by a surge in large-cap transactions, including the largest deal on record, between SpaceX and xAI, as dealmakers accelerated execution amid growing uncertainty around financing conditions and macro volatility. Financing remained available for high-quality assets, though investors became increasingly selective as the quarter progressed and credit markets tightened.
Financial Sponsors
PE Details & Outlook
U.S. Private Equity activity totaled 2,415 announced and estimated transactions in Q1 2026, representing $260.2 billion in aggregate deal value. Deal count increased 4.8% QoQ and 6.2% YoY, while deal value declined 18.3% QoQ and 6.7% YoY, reflecting more deals but less capital deployed.
The quarter saw a shift in capital allocation, with investors rotating toward infrastructure, energy, and industrial assets. HALO sectors, or Heavy Assets with Low Obsolescence, such as utilities, pipelines, and industrial infrastructure, accounted for approximately 31% of capital deployed in Q1. This was driven by large transactions in hard asset industries, while software activity slowed amid uncertainty related to AI-driven disruption.
Take-private activity remained a key contributor to deal value, totaling $64.3 billion during the quarter, driven by fewer but larger transactions.
Market conditions have become more complex, with wider credit spreads and lower private credit inflows contributing to a more selective deal environment. As a result, execution has become more challenging, and valuation gaps between buyers and sellers remain.
VC Details & Outlook
Venture capital activity reached $267.2 billion in Q1 2026, making it one of the strongest quarters on record, though this was driven by a small number of very large transactions. The five largest deals accounted for approximately 73% of total capital deployed, and AI-related investments alone represented nearly 89% of total deal value.
Beneath those headline figures, the broader market remains constrained. Liquidity remains limited, IPO activity has not materially improved, and many companies are still working through elevated prior valuations, all of which continue to weigh on overall market activity.
This concentration is also reflected in deal dynamics, where large financings are pushing average deal sizes higher while median deal sizes remain lower, highlighting that capital is flowing to a narrow set of opportunities rather than the broader market. Exit activity reached record levels during the quarter, but similar to deal activity, it was concentrated in a small number of large transactions rather than representing a broad-based recovery.
Looking ahead, capital is expected to remain concentrated in a limited number of large opportunities, while broader market activity remains more selective.
Key Regions
North America
North American M&A posted a historic Q1 2026, with total deal value reaching a record $1.0 trillion across announced or completed transactions, representing a 22.8% increase QoQ and a 60.2% increase YoY. Deal count rose to 5,539 transactions, increasing 9.5% QoQ and 19.2% YoY, supported by broad activity across sectors and a sharp increase in large-cap transactions.
The quarter was heavily influenced by megadeals, led by the $250 billion xAI transaction, the largest deal on record. Excluding xAI, the top 10 North American deals still totaled $268.5 billion, representing an above-average quarter for deal value. Healthcare led the top 10 with three transactions, followed by energy and financial services. IT activity slowed as investors reassessed software valuations amid AI disruption concerns.
Europe
European M&A activity maintained the strong momentum established in the second half of 2025, with Q1 deal value increasing 5.3% QoQ and 42% YoY as improving macroeconomic conditions and stabilizing interest rates supported dealmaking activity. Market participants appeared increasingly willing to move forward with transactions despite ongoing geopolitical uncertainty, though financing conditions remained sensitive to shifts in investor risk appetite.
Activity during the quarter was concentrated in a small number of large transactions, with the largest deals accounting for a disproportionate share of overall value. Financial services remained a key driver of activity, with deal value in the sector rising 20.1% QoQ amid continued consolidation across asset management, insurance, and wealth management.
Tully & Holland Focus: Consumer
Consumer M&A activity in Q1 2026 was dominated by a concentrated set of mega-cap strategic transactions while the broader middle market remained steady. Large CPG players drove volume through portfolio reshaping, corporate separations, and category-focused consolidations. The strategy of conglomerate structures continued to give way to leaner, more segmented operating models. Deal activity is expected to broaden through the remainder of 2026, supported by PE dry powder deployment, ongoing divestiture supply from legacy CPG restructurings, and improving buyer confidence in premium, functional, and specialized categories.
Food & Beverage
Food & Beverage M&A activity carried momentum into Q1 2026, building on the acceleration seen in the second half of 2025. Q1 2026 activity achieved a nearly five-year high for the F&B segment, with strategic buyers accounting for roughly 75% of deals. The quarter was defined by large-scale portfolio reshaping among incumbent CPG players, with mega-deals and corporate separations dominating headline activity.
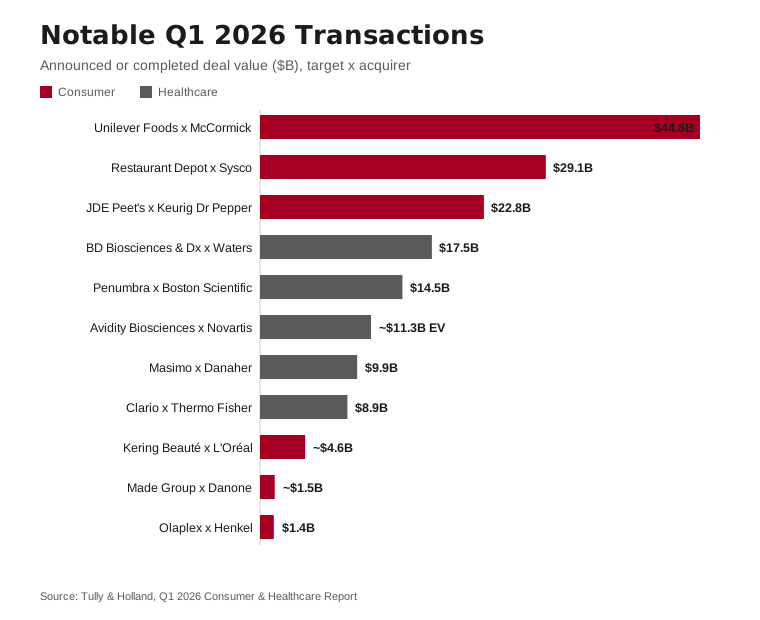
The quarter's largest transaction was McCormick's combination with Unilever's food business in a deal valuing the combined entity at approximately $44.8 billion, announced on the final day of Q1. The transaction unites Unilever's Hellmann's, Knorr, and Frank's RedHot brands with McCormick's spice and condiments platform. For Unilever, the divestiture completes a strategic pivot to a pure-play health and personal care business, with current shareholders retaining a 65% stake in the combined McCormick.
In beverages, Keurig Dr Pepper's $22.8 billion acquisition of JDE Peet's closed March 27. KDP announced its intent to split into two independent U.S.-listed companies by year-end: a dedicated North American refreshment beverage business and a pure-play global coffee company. The transaction is the latest in a series of Big Food separations, reflecting a broad shift toward focused, category-led structures over diversified conglomerates.
Food & Beverage deal activity is expected to stay active through 2026, anchored by continued portfolio reshaping among strategics and sustained PE appetite for better-for-you and functional platforms. Branded products geared toward health-conscious consumers, particularly protein-related products, are likely to drive dealmaking, alongside ongoing activity in alternatives to alcoholic beverages.
Retail & E-Commerce
Retail & E-Commerce M&A activity was selective in Q1 2026, with fewer deals but high demand for quality assets. Dealmaking continued to recalibrate following a 2025 that saw the sector record a 7% decline in overall deal activity and a 29% drop in retail M&A by value. Capital concentrated around scaled platforms with clear differentiation and pricing power.
The quarter's defining e-commerce transaction was eBay's $1.2 billion acquisition of Depop from Etsy, announced February 18. Depop generated approximately $1 billion in gross merchandise sales in 2025, including nearly 60% year-over-year growth in the U.S., with 7 million active buyers. For eBay, the deal extends its position in fashion ecommerce and provides access to a Gen Z customer base.
In DTC e-commerce, strategic buyers drove most of the activity as credit stayed tight for businesses with supply chain exposure to tariff-targeted countries. Sponsors paused new platform pursuits while bolt-ons remained an option for firms with existing sector expertise. Retail deal activity is expected to stay narrow through the remainder of 2026. Premium brands, recommerce platforms, and value-oriented concepts are likely to attract the strongest interest, while mid-priced concepts and heavily leveraged retail formats face a smaller buyer pool and higher execution risk.
Consumer Discretionary
Consumer Discretionary M&A activity stabilized in Q1 2026. 44 transactions were completed during the quarter, an uptick from Q4 2025's close. Several large transactions defined the quarter's headline activity, with deal flow splitting between significant strategic moves at the top and disciplined, fragmented activity in the middle market.
The most significant transaction in the beauty space was L'Oréal's ~$4.6 billion all-cash acquisition of Kering Beauté, completed March 31. The deal brings the House of Creed into L'Oréal's Luxe Division and allows Kering to monetize beauty assets following a ~13% revenue decline in FY2025. Luxury valuations are trading at multi-year lows according to Morningstar, and strategics are taking notice. Henkel's $1.4 billion acquisition of Olaplex, announced March 26, followed similar logic; Olaplex sold at a ~55% premium to its pre-announcement stock price. The deal ended the brand's turbulent four-year public run and giving Henkel a stronger foothold in premium hair care.
Deal activity is expected to stay split through the remainder of 2026, with large strategic transactions in beauty leading deal volume while the middle market recovers gradually. Beauty and clinical skincare are likely to stay the most active subsectors as strategics continue pressing their balance sheet advantage in a soft valuation environment.
Tully & Holland Focus: Healthcare
Q1 2026 healthcare M&A totaled 611 deals and $145.8 billion in capital invested, defined by a handful of large strategic transactions and stable PE activity at 139 announced U.S. deals. Diversified players continued shedding non-core assets to sharpen focus, while sector multiples pulled back modestly alongside a weak equity market. Assets with measurable health outcomes, recurring demand, and differentiated clinical or data capability continued to attract capital.
Consumer Health & Diagnostics
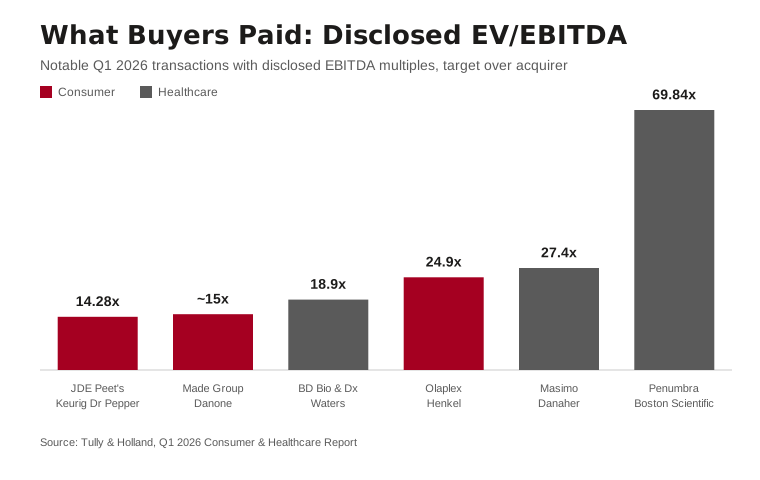
Two deals set the tone for the quarter. Danaher's $9.9 billion acquisition of Masimo at 27.4x EBITDA reflects the premium buyers are paying for diagnostics platforms with recurring revenue and embedded software. BD spun off its Biosciences & Diagnostic Solutions business into a merger with Waters Corporation at a $17.5 billion valuation, consistent with growing pressure on large medtech players to shed non-core operations. Broader sector M&A totaled $26.6 billion across 38 deals in Q1, with EV multiples pulling back modestly across Healthcare Services and Healthcare IT relative to the prior year.
Recurring revenue, clinical data depth, and automation capability remain the primary value drivers heading into Q2. The medtech IPO market is also beginning to open after effectively shutting down in 2024, though access remains limited to a narrow set of later-stage companies.
Wellness & Lifestyle
Q1 2026 wellness M&A was relatively muted by volume, with 16 completed transactions spanning wellness, femtech, sports nutrition, and sleep. Still, several deals highlighted where buyer conviction is strengthening. Europa Sports Partners, a specialty distributor focused on sports nutrition and performance products, reflects continued private equity interest in performance wellness and active lifestyle categories. Movano Health, developer of a medical-grade wearable ring, underscores the growing convergence between consumer health devices and clinical diagnostics. Meanwhile, UroCure’s transaction reinforces urological health as an emerging and increasingly credible M&A subvertical. Across each of these areas, buyers are prioritizing businesses that combine clinical utility, recurring engagement, and differentiated data capabilities over purely lifestyle-oriented brands.
Petcare & Technology
Q1 2026 petcare M&A remained steady, with activity concentrated primarily in premium nutrition and wellness. The quarter’s most notable transactions involved Ollie Pets and Primal Pet Foods, continuing broader consolidation around fresh, raw, and subscription-based pet nutrition platforms. Additional transactions involving Woof Woof and a hemp-based wellness supplement company further reflect growing buyer interest in recurring-consumption and supplement-oriented categories. In contrast, veterinary services were largely absent from Q1 activity, suggesting continued caution toward more operationally intensive healthcare assets. The broader read-through is that investors remain highly constructive on premiumization and wellness trends within petcare, while technology-enabled diagnostics and healthcare platforms continue to represent a more medium- to long-term opportunity set.
Veterinary services was largely absent from Q1 announced activity. Aged sponsor inventory remains meaningful, food premiumization and supplements attract buyers, and technology-enabled diagnostics and monitoring tools remain a longer-term opportunity.
Notable Consumer Q1 2026 Transactions
Unilever Foods x McCormick | $44.8B | 3/31/2026
- McCormick agreed to combine with Unilever's food business in a $44.8B transaction creating a global condiments and seasonings giant with brands including Hellmann's, Knorr, Frank's RedHot, and Cholula; the deal targets $600M in annualized cost synergies.
- For Unilever, the divestiture completes a strategic pivot to a pure-play health and personal care business, with shareholders retaining a 65% stake in the combined McCormick.
JDE Peet's x Keurig Dr Pepper | $22.8B | 3/27/2026
- KDP acquired JDE Peet's at €31.85 per share, creating a global coffee powerhouse at a 14.28x EBITDA and 2.43x revenue multiple.
- Following an interim integration period, KDP plans to separate into two independent U.S.-listed companies: a North American beverage leader and a dedicated Global Coffee Co.
Restaurant Depot x Sysco | $29.1B | 3/30/2026
- Sysco agreed to acquire Jetro Restaurant Depot for $29.1B in cash and stock, gaining access to 166 warehouse locations and ~725k customers.
- The combined company generated nearly $100B in revenue and $6.4B in adjusted EBITDA in the prior year.
- Sysco plans to operate Restaurant Depot as a standalone segment and open 125+ new locations over the next two decades.
Kering Beauté x L'Oréal | ~$4.6B | 3/31/2026
- L'Oréal completed its €4B all-cash acquisition of Kering Beauté, its largest deal to date, bringing the House of Creed into its Luxe Division.
- The deal implies an 11.56x EV/Rev multiple and allows Kering to monetize beauty assets following a ~13% revenue decline in FY2025.
Made Group x Danone | ~$1.5B | 3/4/2026
- Danone acquired Made Group, owner of premium brands Rokeby and Cocobella, from TPG Capital at approximately 15x EBITDA, deepening its foothold in the premium dairy and plant-based categories.
- The deal strengthens Danone's market share in Australia while positioning its portfolio as "better-for-you” growth opportunity.
Olaplex x Henkel | $1.4B | 3/26/2026
- Olaplex sells for $2.06 per share in an all-cash deal at a 24.9x EBITDA and 4.39x EV/Rev multiple, representing a ~55% premium to the pre-announcement stock price.
- The transaction ends Olaplex's turbulent four-year public run and positions Henkel to close the gap with competitors in the premium hair care space.
Notable Healthcare Q1 2026 Transactions
BD x Waters | $17.5B | 2/9/2026
- BD spun off its Biosciences & Diagnostic Solutions business and merged it with Waters Corporation. Valued at $17.5B; BD received $4B in cash and Waters stock representing 39.2% of the proforma company.
- Doubling Waters' total market to approximately $40B, the deal also values BD at an 18.9x EBITDA and 5.15x revenue multiple.
Penumbra x Boston Scientific | $14.5B | 1/15/2026
- The 73% cash / 27% stock transaction at $374 per share, move BSX into mechanical thrombectomy and neurovascular research, two key strategic verticles within the vascular space.
- Penumbra's portfolio centers on its proprietary CAVT systems to remove blood clots as well as solutions for strokes.
- The deal values them at a 69.84x EBITDA and 10.33x revenue multiple.
Avidity Biosciences x Novartis | ~$11.3B EV | 2/26/2026
- The deal at a 46% premium deal brings brings three late-stage RNA programs into Novartis’ xRNA pipeline.
- The deal implies a 604x EV/Rev multiple reflective of Avidity's former VC-stage revenue base and the company’s significant valuation potential.
Masimo x Danaher | $9.9B | 2/17/2026
- Danaher agreed to acquire Masimo – diagnostics provider of pulse oximetry and AI-enabled noninvasive monitoring – for $180 per share, representing 27.4x EBITDA and 6.48x revenue.
- Masimo will operate as a standalone unit within Danaher's Diagnostics segment with expected first-year EPS accretion of $0.15–$0.20.
Clario x Thermo Fisher Scientific | $8.9B | 3/24/2026
- Thermo Fisher completed its acquisition of Clario Holdings, a leading provider of endpoint data solutions for clinical trials
- Clario's platform has supported approximately 70% of FDA and EMA novel drug approvals over the past decade.
- The deal implies a 7.1x revenue multiple and is expected to be accretive to Thermo Fisher's adjusted operating margin, contributing $0.45 in adjusted EPS in year one alone.
Text reproduced from the report as published by Tully & Holland. Photograph: J.N. Eskra, CC BY-SA 4.0, via Wikimedia Commons.
Keep reading

Consumer Industry Update Q4 2025
Global M&A closed 2025 at nearly $5 trillion, the strongest year for dealmaking on record, and the fourth quarter set a ...
Read →
Consumer Industry Update Q3 2025
Global deal value jumped 35.1% year over year to $1.1 trillion, the strongest quarter since late 2021, while consumer de...
Read →
Consumer Industry Update Q1 2023
Global deal value fell by nearly half in the first quarter of 2023, yet consumer M&A closings in the US and Canada slipp...
Read →