
Beverage Industry Update Q3 2025
Big Beverage Buys Its Growth
Energy and functional drinks won the summer of 2025, alcohol kept softening, and the largest strategics answered with their checkbooks. Our September 2025 bulletin on the categories, and the deals, that defined the season.

the reported value of Keurig Dr Pepper's announced acquisition of Peet's Coffee (August 25, 2025), the year's defining beverage transaction.
PepsiCo's acquisition of Poppi, a decisive strategic bet on functional soda.
Celsius Holdings' acquisition of Alani Nutrition, pairing two better-for-you energy brands into one functional-beverage platform.
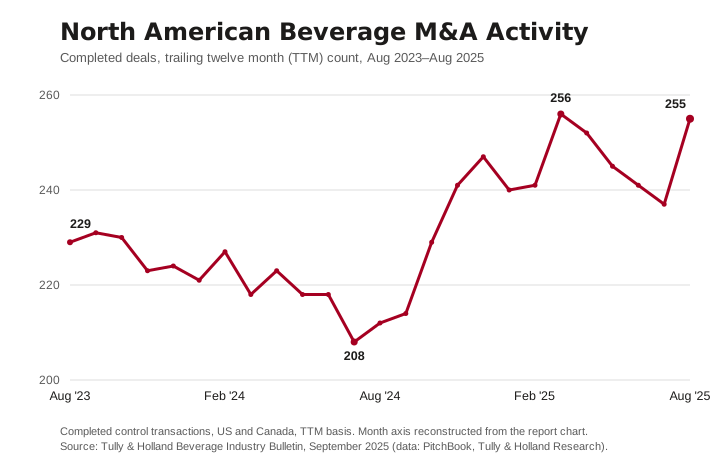
completed North American beverage deals on a trailing-twelve-month basis in the bulletin's final August 2025 reading, up from a low of 208 the prior summer.
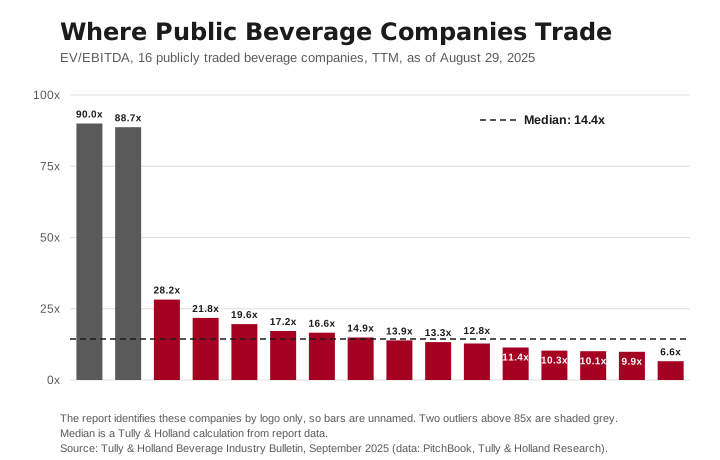
the median EV/EBITDA multiple across the 16 public beverage companies the report tracks (our calculation from report data as of August 29, 2025).
the January 2025 merger of Mass Bay Brewing Co. and Finestkind Brewing, with Tully & Holland advising Mass Bay, a template for craft consolidation.
Notable Industry Trends
Caffeinated & Energy
Summer 2025 saw steady momentum in the caffeinated beverage market, with energy drinks leading growth across convenience and retail channels. Celsius and other major players such as Monster and Red Bull expanded market share, as strong summer demand for hydration-supported energy drinks reinforced the category’s momentum. Given the heat of summertime, Coffee naturally saw increased cold format sales, with iced and ready-to-drink offerings from Starbucks and Dunkin’ remaining resilient despite softer trends in premium whole-bean and specialty café sales. Tea and matcha also benefited from wellness positioning, particularly among younger consumers seeking natural caffeine sources. Beyond traditional formats, innovation across caffeinated and energy beverages continued to blur category lines, with hybrids that combine functional ingredients, natural caffeine, and hydration benefits gaining shelf space. Innovation pipelines remain active heading into the fall, with brands expected to introduce new flavor mashups and more unique seasonal Limited Time Offerings (LTOs). For example, Starbucks announced their Pumpkin Spice Whiskey Barrel-Aged Cold Brew, a bold enhancement to a classic fall flavor.
Bold Fruit Drinks & Refreshers
The refreshers and natural drink segment experienced rapid growth, with aguas frescas, lemonades, and tropical blends proving popular in both retail and foodservice channels. Quick-serve restaurants such as Dunkin’ Donuts, Chipotle, and Taco Bell leaned into seasonal flavors like mango, watermelon, and hibiscus to capture late-summer traffic, while packaged beverage brands emphasized clean label positioning with simple ingredients and reduced sugar. Aguas frescas continued their shift from niche to mainstream, showing up in grocery aisles and national chain promotions as consumers embraced lighter, fruit-forward options. Innovation extended into carbonated variants with functional twists, pairing natural fruit bases with electrolytes or botanicals. Tractor Beverage, known for high quality organic fruit drinks, furthered brand awareness through its Mad Farmer Tour, expanding presence at colleges and universities.
Alcoholic Beverages
Alcoholic beverage sales remained mixed, with category softness putting pressure on larger brands while smaller, consumer-focused players found ways to grow. Inexpensive, single-serve Ready To Drink (RTD) cocktails performed well, with BuzzBallz continuing its dominance this summer thanks to its playful packaging, high ABV, and affordability that resonated strongly with younger drinkers. Craft and niche brands also provided bright spots: Garage Beer continued to expand rapidly, boosted by its alignment with the Kelce Brothers’ media platform, while Busch Light sustained momentum by leaning into flavored innovation through their apple flavored beer, a key preference for younger consumers. Spindrift phased out their spiked seltzers line, citing recalibrated focus on core brand platforms. Beyond the products themselves, alcohol brands increasingly sought to connect with audiences through unique cultural tie-ins and collaborations, signaling new ways of building relevance amidst a slowing category. This environment has reinforced the importance of positioning, as brands that balance affordability, novelty, and cultural resonance are finding room to thrive even as broader industry growth remains tepid.
Low/Non-Alcoholic Beverages
Non-alcoholic beer and emerging RTD alternatives sustained steady growth. Athletic Brewing continued to set the pace in NA craft, leveraging its expanded San Diego facility and seasonal releases to strengthen both retail and taproom presence. Its positioning around wellness and active lifestyles kept the brand at the center of the “sober curious” movement, while broader distribution into grocery and convenience reinforced mainstream appeal. GO Brewing also contributed to category visibility, with its lineup of craft-style NA beers appealing to health-conscious drinkers and extending the reach of moderation into new retail and on-site occasions. Meanwhile, non-alcoholic RTDs gained momentum, particularly mocktail-style spritzers and spirit-free seltzers, as consumers looked for options that fit social occasions without alcohol. It was the mix of NA craft and RTD innovation that defined the month, underscoring how moderation is evolving into a legitimate consumer sector.
Recent M&A Activity
M&A activity in the North American Beverage sector has been trending upwards for the past year, with a considerable uptick in August. Listed below are notable transactions in the space for the year, as well as the monthly number of completed M&A deals on a TTM basis over the last two years.
Keurig Dr. Pepper (KDP) announced its intention to acquire Peet’s Coffee on August 25, 2025. The transaction is reported to be $18 billion. Notably, KDP intends to split the Beverage brands from their Global Coffee brands, post-acquisition. KDP also acquired Dyla Brands this July for $98 million, Dyla owns Stur a producer of drink mixes. KDP’s acquisition further highlights the strategic importance of drink versatility achieved through flavorful water enhancement offerings.
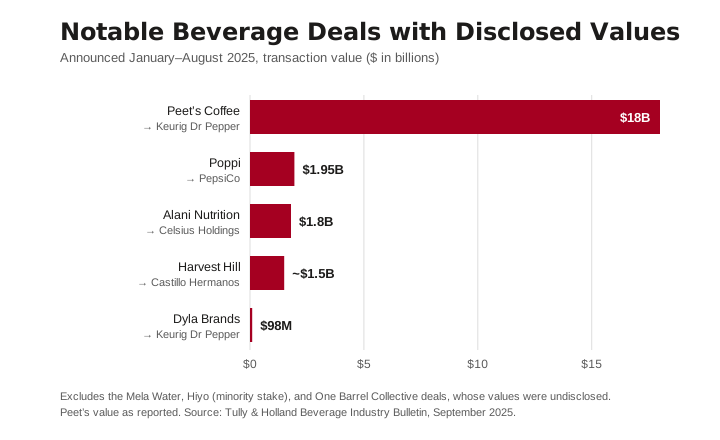
Castillo Hermanos announced an agreement on April 3, 2025 to acquire Harvest Hill. Harvest Hill was valued at approximately $1.5 billion. Castillo Hermanos viewed this as a strategic move to expand their footprint in the U.S. market.
KJ Holding Corp. announced the acquisition of Mela water on April 2, 2025. KJ Holding Corp. seeks to expand its portfolio with the acquisition and grow Mela water through its strong distribution networks via Calypso Lemonades.
Celsius Holding acquired Alani Nutrition on April 1, 2025. The transaction value was $1.8 billion. The acquisition pairs two better-for-you energy drink brands to create a powerhouse platform in the functional beverage space.
PepsiCo announced its acquisition of Poppi on March 17, 2025. The transaction amounted to $1.95 billion and greatly increases Pepsi’s portfolio in the functional beverage category.
Constellation Brands announced it acquired a minority stake in Hiyo on February 20, 2025. Hiyo produces non-alcoholic, RTD cocktails. Constellation Brands aims to appeal to growing demand for NA beverages with this investment.
Mass Bay Brewing Co. and Finestkind Brewing merged to form One Barrel Collective on January 23, 2025. Mass Bay Brewing Co. was advised by Tully & Holland. The new entity proves the importance of consolidation in an industry with many headwinds.
Text reproduced from the report as published by Tully & Holland. Photograph: Wortmagier, CC BY-SA 4.0, via Wikimedia Commons.
Keep reading

Beverage Industry Update Q2 2026
The strategics have stopped waiting for internal innovation to catch the growth brands. From PepsiCo's $1.95 billion pur...
Read →
Healthy Food & Beverage Update April 2019
In every deal-size bracket we measured, healthy food and beverage companies sold at higher EV/EBITDA multiples than thei...
Read →
Consumer Industry Update Q1 2025
Consumer M&A opened 2025 at an estimated $162 billion in global value, food and beverage deal counts jumped 24.1%, and P...
Read →