
Beverage Industry Update Q2 2026
Big Beverage Would Rather Buy Than Build
The strategics have stopped waiting for internal innovation to catch the growth brands. From PepsiCo's $1.95 billion purchase of Poppi to KDP's landmark JDE Peet's close, our June 2026 bulletin maps where beverage M&A is concentrating and who gets the premium.

PepsiCo's purchase of Poppi, the hallmark of an acquisition wave that has carried into 2026 as strategics buy their way into modern soda.
the combined financing behind Keurig Dr Pepper's JDE Peet's acquisition (roughly $9B of debt, $8.5B of equity, and ~$5B of assumed bonds, our sum). It closed in early April 2026 and ranks among the largest beverage transactions on record.
Refresco's enterprise value for SunOpta (~1.4x revenue), closed May 1, 2026. M&A is moving upstream into co-manufacturing and filling.
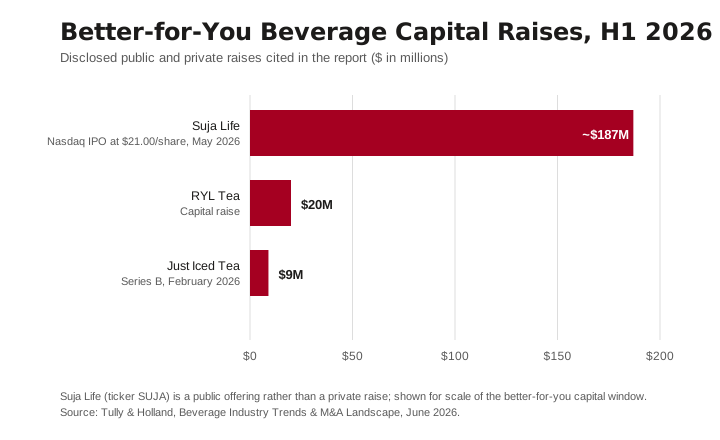
Suja Life's Nasdaq IPO raise at $21.00 per share in May 2026, a selective reopening of the public market for better-for-you brands.
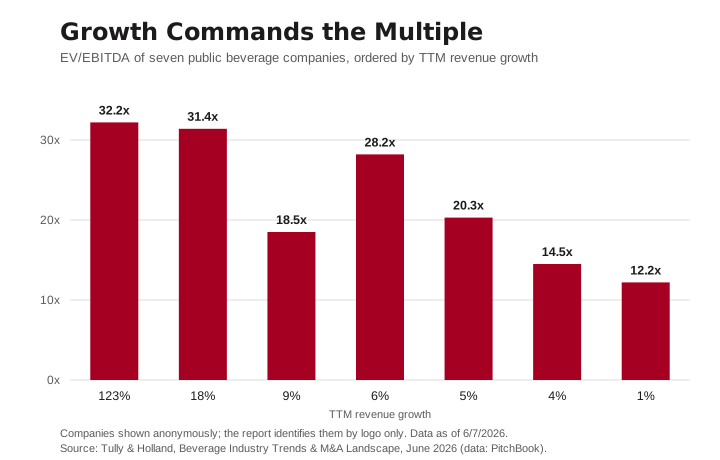
the EV/EBITDA range across the seven public beverage companies we track. The fastest grower carries the highest multiple; the slowest carries the lowest.
Energy, Refreshing Hydration, Modern Sodas, and Anti-Energy/Mindful Beverages are where strategic interest is concentrating as of June 2026.
Executive Summary
Companies within the beverage sector are accelerating consolidation, with differentiated brands selling at premium valuations amid preference for fast, strategic scale over organic brand building. After a multi-year buildout of up-and-coming brands, the vertical is an opportunity for strategics, shown in a wave of acquisitions that have carried into 2026. Hallmark transactions include PepsiCo's $1.95 billion purchase of Poppi, and Keurig Dr Pepper's acquisition of JDE Peet's, which closed in April 2026. Large beverage strategics have moved to own the fastest growing, differentiated sub-segments. Capital remains selective, with acquirers concentrating on brands that combine base velocity consistency, distribution scale and strength, and decent margin profiles.
As of June 2026, four sub-segments within beverages are continuing to attract strategic interest:
- Energy: Strong velocities and TDPs, which are evolving with zero-sugar, botanical energy, and alternative caffeine products.
- Refreshing Hydration: Premium hydration – with products ranging from invigorating juices to elevated coconut drinks – is winning retail distribution.
- Modern Sodas: Prebiotic and better-for-you sodas are becoming mainstream, particularly in QSRs.
- “Anti-Energy” and Mindful Beverages: Calming, nootropic, and functional formats spanning stress relief, cognition, and mood are winning accounts in the "anti-energy" segment.
Looking ahead, we expect continued divergence within the industry. High-growth distinguished brands are likely to command premium multiples, while undifferentiated brands face mounting pressure from private-label entrants.
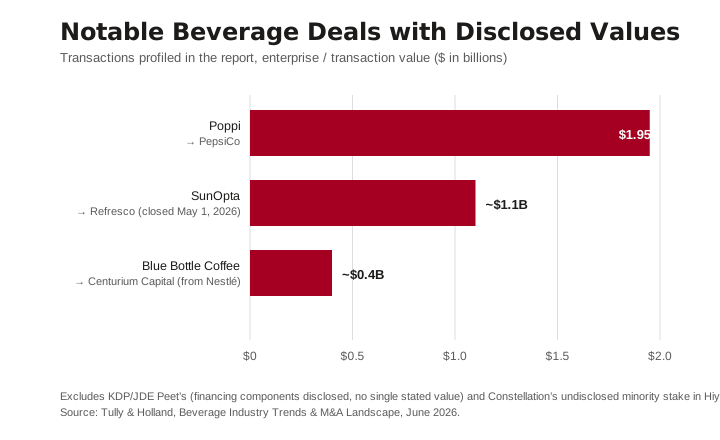
In the first half of 2026, driven by the expansion of beverage category segments, product package formats, and consumer occasions, we have also witnessed increased M&A in “upstream” stages of the supply chain. One example was Refresco’s roughly $1.1 billion purchase of SunOpta, which closed in May 2026, and folded a leading aseptic and plant-based co-manufacturer into the largest independent beverage filler in North America. As brand upstarts more rapidly develop, and established companies face production challenges related to specialty formats, we expect these upstream investments to continue in the foreseeable future.
Industry Trends
Energy
Caffeine continues to command high strategic interest amid elevated commodity coffee bean prices, evidenced by Keurig Dr Pepper's transformational acquisition of JDE Peet's and its planned separation into independent coffee and refreshment companies. In energy drinks, “natural” and “organic” beverages are gaining distribution. Guru Organic Energy, Canada’s leading organic energy drink, gained distribution in Sprouts as of June 2026. The tea category is also gaining distribution seen in RYL Tea’s $20M capital raise. Similarly, Just Iced Tea raised a $9M Series B in February 2026 to fund national retail expansion.
Refreshing Hydration
Authentically clean, uncompromising hydration is proving to be a sub-segment that has lasting velocity and distribution stamina. Products like Coaqua’s viral coconut water (which has been expanding distribution, most recently into Hannaford), or Tractor’s Haymaker “farmers tonic” (which launched in Q1 in Sprouts and has been outpacing incumbents) are proving that consumers desire hydration, with limited, high-quality ingredients. Investor appetite for the clean-functional space is following, Suja's wellness shots came off a ~$187M Nasdaq IPO in May 2026, and with incumbents extending their own electrolyte lines (BODYARMOR Lyte, Vita Coco Electrolytes), hydration is shaping up as a durable, acquirable platform.
Modern Sodas
Prebiotic and gut-health sodas moved firmly into the mainstream, led by Poppi and Olipop, and now chased by a widening field including Culture Pop, Cove, and Bloom Pop. Incumbents responded with internal challengers (Coca-Cola's Simply Pop), signaling strategic position in functional, low-sugar refreshment. Aguas frescas, lemonades, and clean-label refreshers continued their shift from niche to national, increasingly seen in QSRs such as McDonald’s, Cava, and Taco Bell.
Anti-Energy & Mindful Beverages
The “anti-energy” segment is gaining strategic interest. Wellness beverages are evolving beyond natural ingredients toward functional benefits, cognitive performance, mood support, stress relief, and digestive health, creating a new consumption occasion distinct from traditional energy and sports drinks. Strategic interest is following, with brands like Hiyo pairing stress relief, cognitive enhancement, and digestive support in a non-alcoholic RTD, and Recess continuing to build the calm/anti-anxiety side of the emerging space.
Recent Deal Activity
Keurig Dr Pepper completed its acquisition of JDE Peet's in early April 2026, with the shares delisted from Euronext Amsterdam. Financed through roughly $9 billion debt, $8.5 billion of equity, and ~$5 billion of assumed bonds, it ranks among the largest beverage transactions on record. KDP plans to separate into two public companies, a North American refreshment player and a global pure-play coffee leader, by year-end 2026.
Nestlé agreed to sell Blue Bottle Coffee to Centurium Capital, the backer of China's Luckin Coffee, with the deal expected to close in the first half of 2026. The transaction values the roaster and café platform (~140 locations) at approximately $400 million, with Nestlé retaining rights to Blue Bottle's packaged and single-serve products.
Refresco completed its acquisition of SunOpta on May 1, 2026, paying $6.50 per share in cash, an enterprise value of roughly $1.1 billion (~1.4x revenue). SunOpta is a leading North American producer of plant-based and dairy-alternative beverages, significantly broadening Refresco's position in the fast-growing category.
Constellation Brands acquired a minority stake in Hiyo, a non-alcoholic functional RTD positioned around stress relief, cognitive enhancement, and digestive health. The investment gives Constellation exposure to the fast-emerging "anti-energy"/wellness occasion. (No deal value disclosed.)
Suja Life completed its Nasdaq IPO in May 2026, raising approximately $187 million at $21.00 per share under the ticker "SUJA." The Paine Schwartz-backed platform, spanning Suja Organic juices, Vive Organic shots, and Slice sodas, generated roughly $327 million in net sales, signaling a selective reopening of the public market for better-for-you brands.
Text reproduced from the report as published by Tully & Holland. Photograph: www.Pixel.la Free Stock Photos, CC0, via Wikimedia Commons.
Keep reading

Beverage Industry Update Q3 2025
Energy and functional drinks won the summer of 2025, alcohol kept softening, and the largest strategics answered with th...
Read →
Healthy Food & Beverage Update April 2019
In every deal-size bracket we measured, healthy food and beverage companies sold at higher EV/EBITDA multiples than thei...
Read →
Consumer Industry Update Q1 2025
Consumer M&A opened 2025 at an estimated $162 billion in global value, food and beverage deal counts jumped 24.1%, and P...
Read →